“Aluminum’s Black Swan: War and Energy Crisis from the Strait of Hormuz to a Global Supply Shock — March 2026”
Here’s the full English translation of your text:
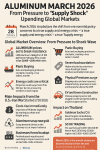
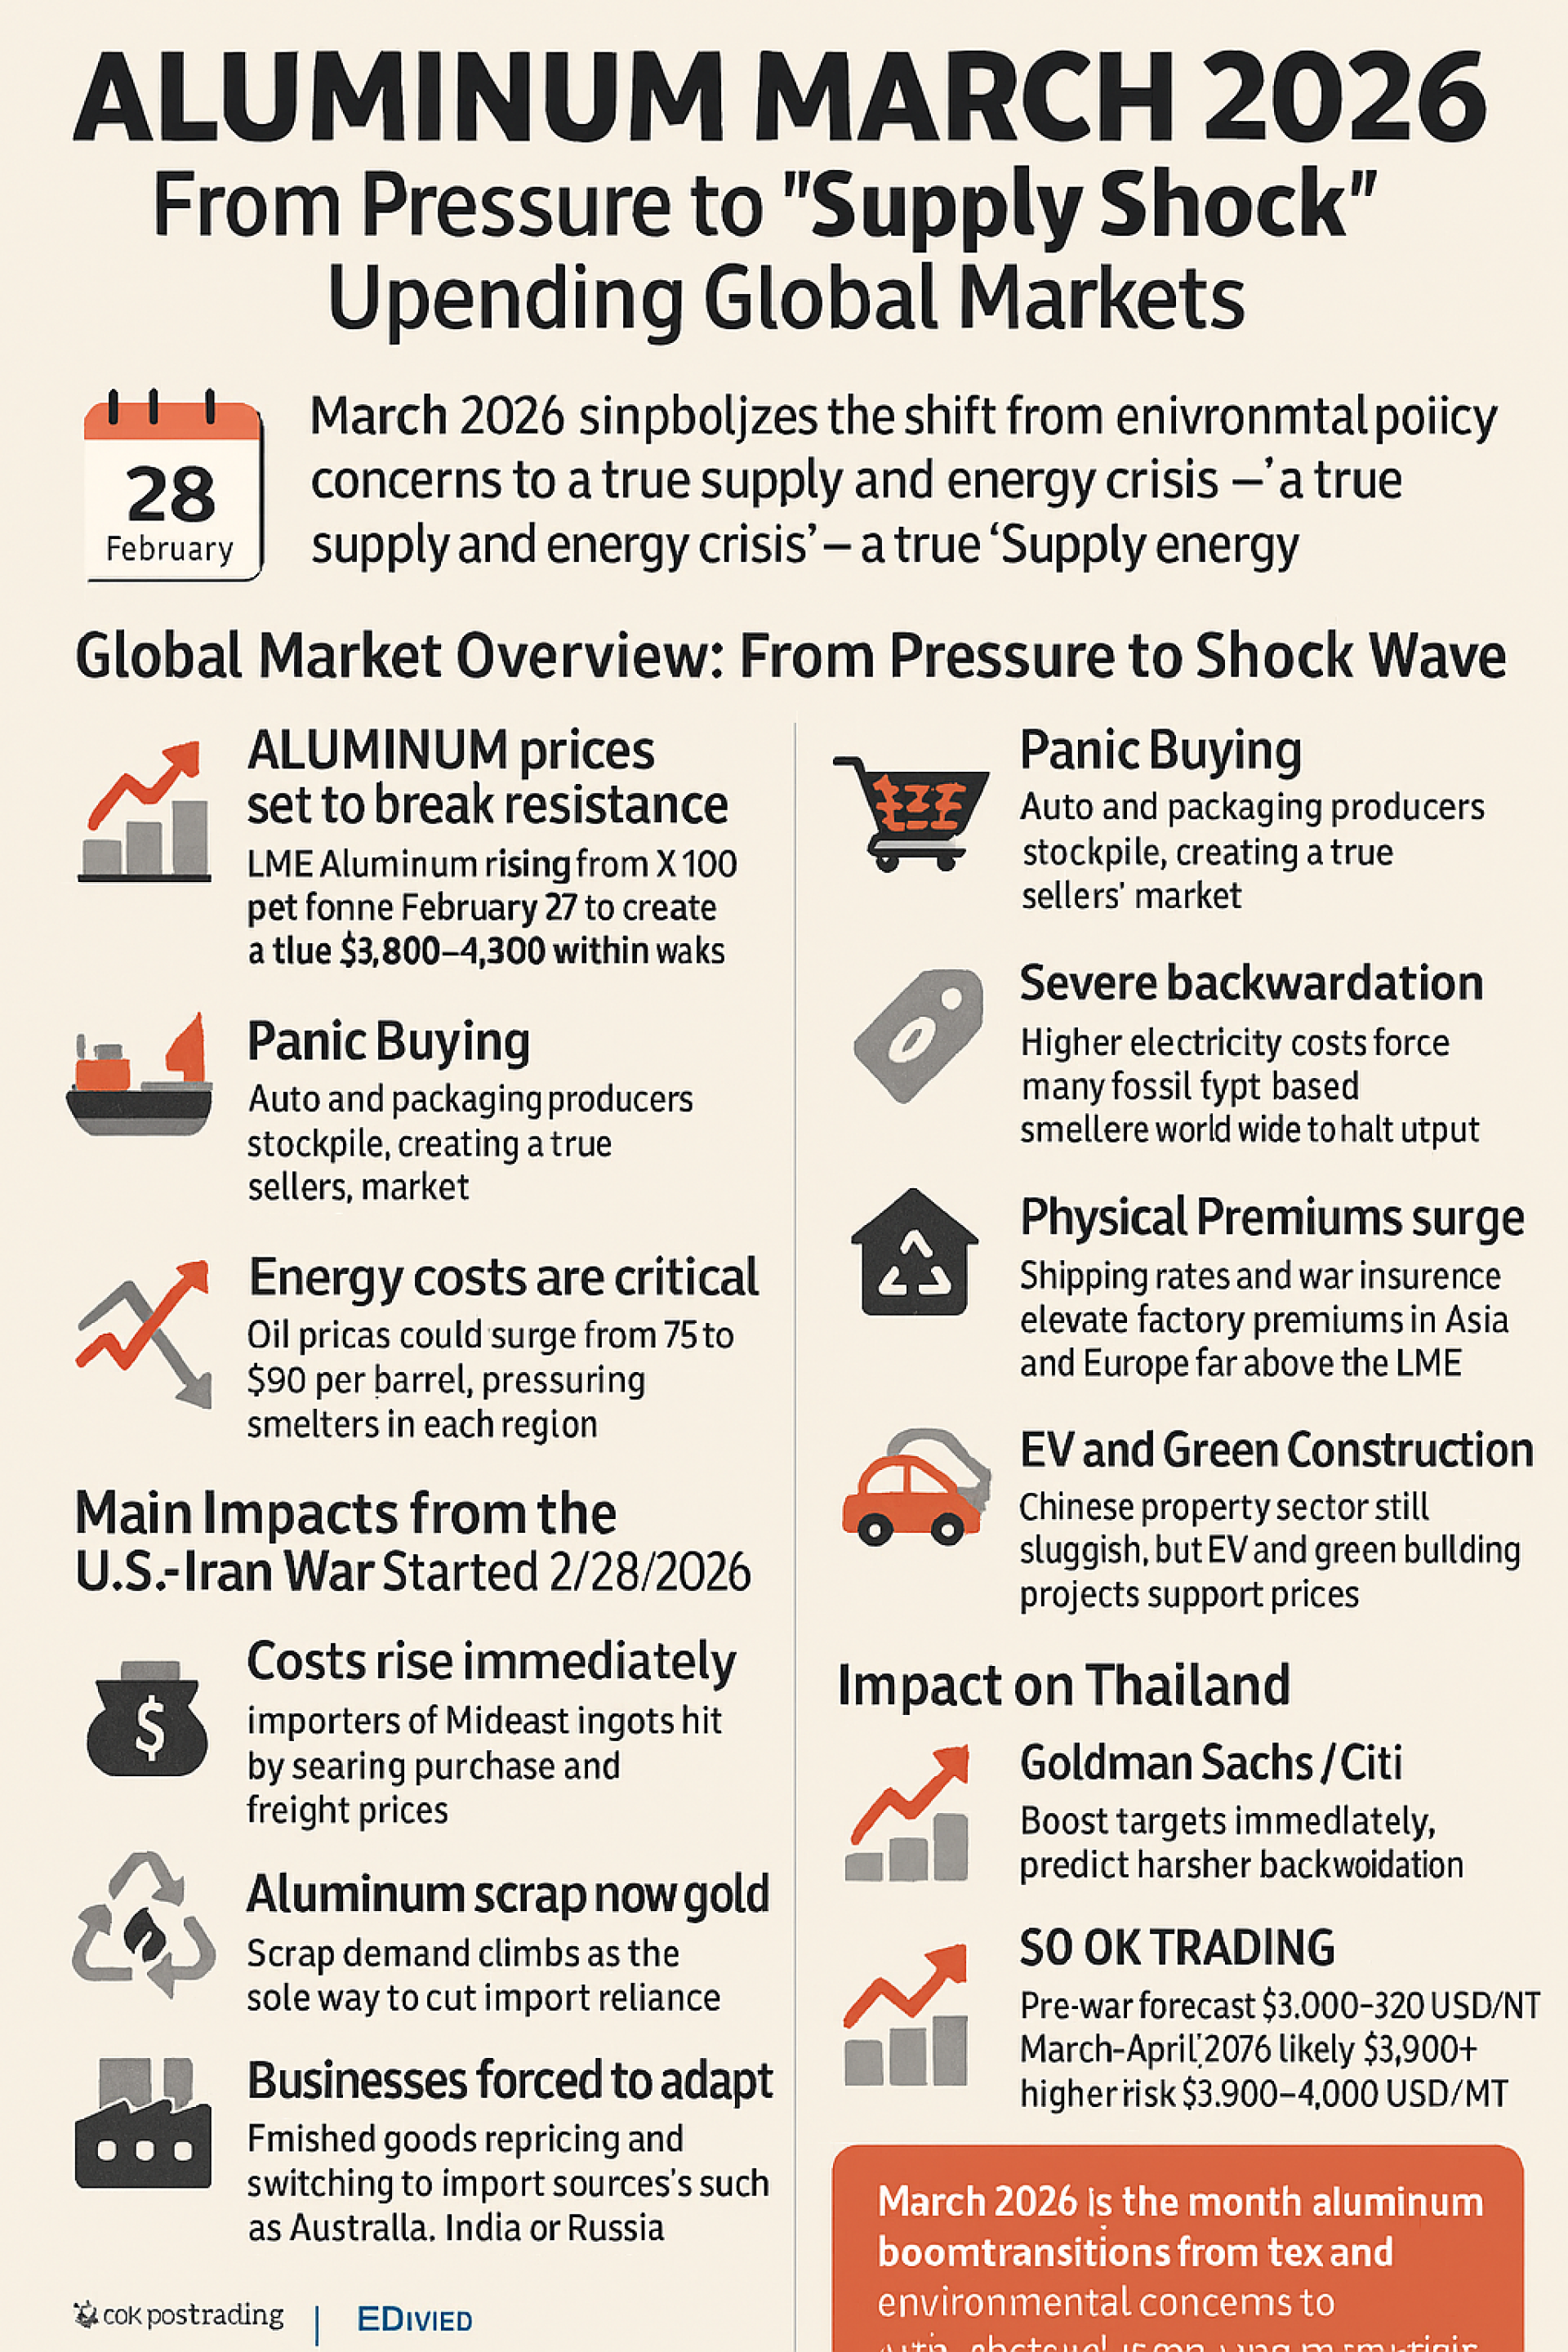
Aluminum in March 2026 – From Pressure to a “Supply Shock” Shaking the Global Market: The Impact of the U.S.–Iran War
March 2026 is not merely a month when the aluminum market must contend with tariffs and environmental measures. It is also the month when the entire world faces a “Black Swan Event” triggered by the closure of the Strait of Hormuz, a consequence of the war between the United States and Iran that began on February 28, 2026. This event has shifted the market equation from policy concerns to a true crisis of supply and energy.
Global Market Overview: From Pressure to Shock Wave
Aluminum prices likely to break resistance: LME aluminum may surge to the range of USD 3,800–4,300 per ton within weeks, from the closing price of USD 3,100 per ton on February 27, 2026. On March 2, the first trading day after the outbreak of the U.S.–Iran war, prices could immediately jump to USD 3,350–3,500 per ton.
Panic buying: Automakers and packaging producers worldwide are rushing to secure raw materials, pushing the market into a true “seller’s market.”
Severe backwardation: Immediate delivery prices are far higher than forward prices, as everyone wants material “right now.”
Energy costs as the decisive factor: Oil prices may rise from USD 75 per barrel to USD 90 per barrel in the short term, exerting heavy cost pressure on smelters across regions.
Key Impacts of the U.S.–Iran War (Beginning February 28, 2026)
Supply disruption: The closure of the Strait of Hormuz instantly removes aluminum supply from the Middle East (UAE, Bahrain, Qatar, Saudi Arabia), which accounts for 10% of global output.
Energy crisis: Rising electricity costs worldwide force many fossil-fuel-dependent smelters to halt production.
Physical premium surge: War insurance and freight costs push factory-gate prices in Asia and Europe far above LME screen prices.
EV and green construction demand: Despite China’s property slowdown, demand for aluminum in EVs and green building projects continues to support prices.
Impact on Thailand
Costs rise immediately: Importers of aluminum ingots from the Middle East face soaring product and shipping costs.
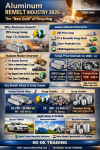
Scrap becomes “gold”: Domestic demand for aluminum scrap surges, as it is the only viable option to reduce import dependence.
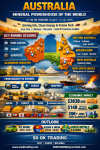
Immediate adaptation required: Manufacturers must adjust finished product prices and seek new import sources from Australia, India, or Russia.
Inventory gains: Those holding old stock benefit from price differentials, but new procurement carries high risk.
Financial Institutions’ View
Goldman Sachs / Citi: Raised price forecasts immediately, expecting backwardation to intensify.
SO OK TRADING’s Aluminum Price Forecast
Pre-war forecast: USD 3,000–3,200 per MT
Post-war (March–April 2026): Likely above USD 3,500 per MT
If conditions worsen: Prices could rise to USD 3,800–4,000 per MT
✨ Conclusion
March 2026 marks the month when the global aluminum market shifted from “concerns over tariffs and environmental measures” to a full-blown “supply and energy crisis.” Those who adapt quickly will not only survive but also seize opportunities from this upheaval.
Recycling is the answer: Investing in aluminum recycling systems ensures cost advantages and sustainability.
Green aluminum carries a premium: Producers complying with CBAM can sell at higher prices.
EV and green construction demand: High-quality aluminum demand remains a long-term driver.
Diversifying import sources: Turning to Australia, India, or Russia reduces reliance on the Middle East.
*** If you require aluminum products, whether ADC12 or primary ingots, please contact SO OK TRADING at www.sooktrading.com → Give Inquiry, or email us at sooktrading@outlook.com.