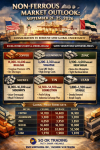
“โลหะนอกกลุ่มเหล็กโลก: การวิเคราะห์แนวโน้มราคาและภาพรวมตลาดสัปดาห์ 21–25 กันยายน 2026 — Supply ตึงตัว ดันราคาทรงตัวสูง”: SO OK TRADING
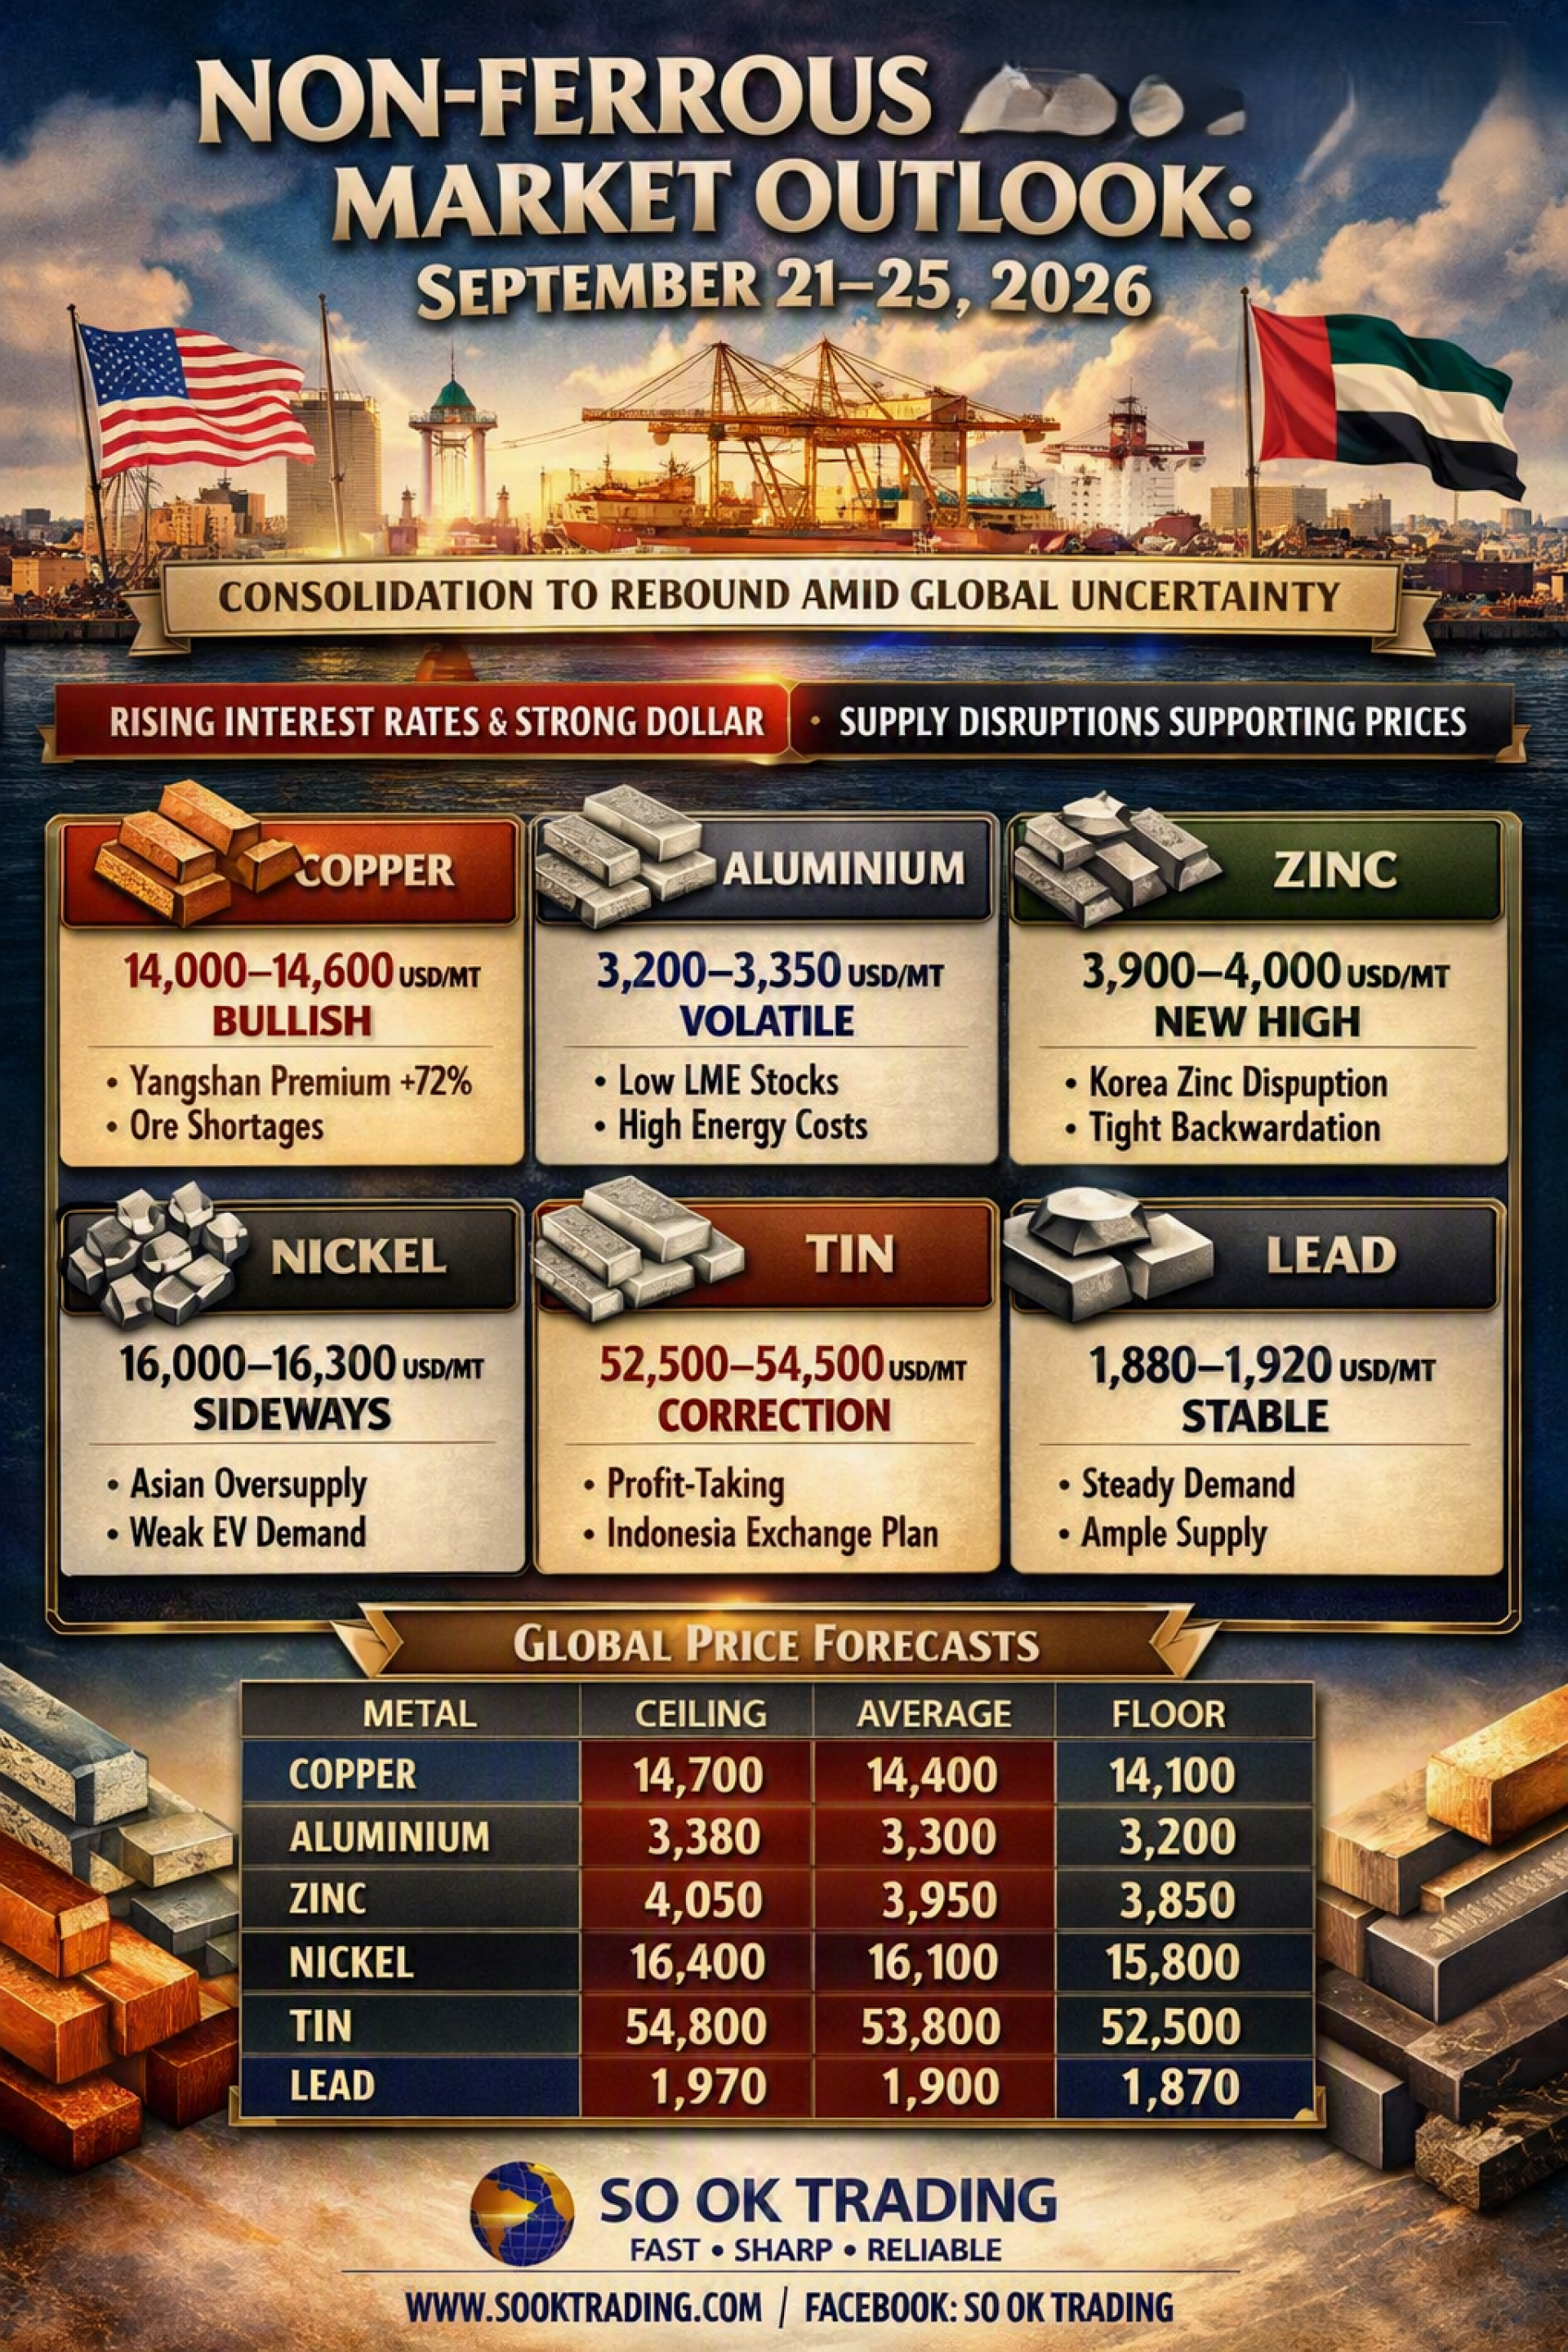
แนวโน้มราคากลุ่มโลหะนอกกลุ่มเหล็ก (Non-Ferrous Metals) สัปดาห์ 21–25 กันยายน 2026: ภาพรวมตลาดโลก พร้อมประมาณการ ราคา Ceiling–Average–Floor : บทความโดย SO OK TRADING : 20 กันยายน 2026
-------------------
บทนำ
ตลาดโลหะนอกกลุ่มเหล็ก (Non-Ferrous Metals) ในสัปดาห์นี้ยังคงเผชิญแรงกดดันจากปัจจัยมหภาค โดยเฉพาะการปรับขึ้นอัตราดอกเบี้ยของธนาคารกลางสหรัฐฯ (Fed) และประเทศกลุ่มอ่าวอาหรับ ส่งผลให้ค่าเงินดอลลาร์แข็งค่าและกดดันราคาสินค้าโภคภัณฑ์ในระยะสั้น อย่างไรก็ตาม โครงสร้างอุปทานที่ตึงตัว (Supply Tightness) ของแต่ละโลหะยังคงช่วยพยุงราคาไม่ให้หลุดกรอบแนวรับสำคัญ
--------------------
Outlook ตลาดโลหะ
ภาพรวมตลาดโลก (LME) อยู่ในภาวะ “Consolidation to Rebound” หลังจากราคาถูกกดดันกลางเดือน แต่สามารถฟื้นตัวได้ในช่วงปลายสัปดาห์ก่อนด้วยแรงซื้อทางกายภาพที่ยังแข็งแกร่ง โดยเฉพาะทองแดงและสังกะสีที่มีปัจจัยเฉพาะตัวด้าน Supply disruption หนุนราคา
-------------------
แนวโน้มและทิศทางรายโลหะ
-------------------
ทองแดง (Copper)
กรอบราคา: 14,000–14,600 USD/ตัน
แนวโน้ม: Sideways / Bullish Bias
ปัจจัยหนุน: พรีเมียม Yangshan พุ่งขึ้นกว่า 72%, Supply Concentrate ขาดแคลนรุนแรง , เหมืองทั่วโลกขาดของเนื่องจาก Overall Demand สูงกว่า Supply ขาดแคลนแร่ดิบ
--------------------
อลูมิเนียม (Aluminium)
กรอบราคา: 3,200–3,350 USD/ตัน
แนวโน้ม: High Volatility / Correction Risk
ปัจจัยหนุน: Stock LME ต่ำสุดในรอบศตวรรษ, ความเสี่ยงภูมิรัฐศาสตร์ตะวันออกกลาง
ราคาสูงเกินไป และ ของขาด โดยราคาพลังงาน (น้ำมัน) กดดันทำให้ต้นทุนการผลิตสูงต่อเนื่อง
------------------
สังกะสี (Zinc)
กรอบราคา: 3,900–4,000 USD/ตัน
แนวโน้ม: Bullish
ปัจจัยหนุน: อุบัติเหตุโรงหลอม Korea Zinc, โครงสร้าง Backwardation ชี้ตลาดตึงตัว --> ราคา NEW HIGHสูงสุดในรอบหลายๆปี และทรงตัวในระดับสูงแบบเสถียร ไม่ย่อ
-----------------
นิกเกิล (Nickel)
กรอบราคา: 16,000–16,300 USD/ตัน
แนวโน้ม: Sideways
ปัจจัยกดดัน: ซัพพลายล้นตลาดเอเชีย และดีมานด์จากแบตเตอรี่ EV
-----------------
ดีบุก (Tin)
กรอบราคา: 52,500–54,500 USD/ตัน
แนวโน้ม: Correction จากแรงขายทำกำไร
ปัจจัยบวก: อินโดนีเซียเตรียมเปิด Commodity Exchange สำหรับดีบุกและนิกเกิล
----------------
ตะกั่ว (Lead)
กรอบราคา: 1,880–1,920 USD/ตัน
แนวโน้ม: Stable เนื่องจากดีมานด์ปลายน้ำยังนิ่ง ---> และ SUPPLY ยังไม่ขาด
---------------
ปัจจัยภายนอกและภายในที่เกี่ยวข้องกับ NON FERROUS : SEP 2026
---------------
ภายนอก (External Factors)
EU เสนอข้อจำกัดการส่งออกเศษโลหะ → กระทบตลาดรีไซเคิลในเอเชีย ---> SCRAP ขาด
ตัวเลขเศรษฐกิจจีน (PMI) → กำหนดทิศทาง Physical Demand --> ทิศทาง DEMAND
ค่าเงินดอลลาร์แข็งค่า → กดดันราคาสินค้าโภคภัณฑ์ ---> Dollar ขึ้น กดดันราคา Non Ferrous ให้ย่อตัวลง
---------------
ภายใน (Internal Factors)
Stock LME ต่ำมาก โดยเฉพาะ Aluminium และ Zinc → เสี่ยง Supply Shortage
ค่าพรีเมียมสูงผิดปกติ:
Copper Cathode: 145–160 USD/ตัน (CIF TH)
Aluminium Ingot (P1020): MJP Q3 Settlement สูงสุดในรอบ 11 ปีที่ 395 USD/ตัน , Q4 MJP กำลังเจรจาคาดว่าจบราวๆ 350-370 USD/ตัน กรณีน้ำมันยังคงวิงขึ้นสูงแบบนี้ อาจจะได้เห็นราคา MJP เดิมที่ 395-400 USD/ตัน
----------------
กลยุทธ์สำหรับผู้จัดซื้อไทย และ โลก
Copper: หลีกเลี่ยง Spot ปริมาณมาก เนื่องจากพรีเมียมสูงเกินไป → ใช้ Monthly Average หรือ Term Contract
Aluminium: ตรวจสอบเทอมส่งมอบ หากเปลี่ยนเป็น FOB อาจลดต้นทุน Freight ได้
Zinc & Copper: ระวังความผันผวนจาก Supply disruption
กลยุทธ์ Hedging: ทยอยซื้อหรือล็อกราคาบางส่วนในช่วงราคาอ่อนตัว เพื่อป้องกันความเสี่ยง
-----------------
ประมาณการราคา Non-Ferrous Metals (Ceiling–Average–Floor) สัปดาห์หน้า (21-25/9/2026)
Copper: Ceiling 14,700 / Average 14,400 / Floor 14,100 USD/ตัน
Aluminium: Ceiling 3,380 / Average 3,300 / Floor 3,200 USD/ตัน
Zinc: Ceiling 4,050 / Average 3,950 / Floor 3,850 USD/ตัน
Nickel: Ceiling 16,400 / Average 16,150 / Floor 15,800 USD/ตัน
Tin: Ceiling 54,800 / Average 53,800 / Floor 52,500 USD/ตัน
Lead: Ceiling 1,930 / Average 1,900 / Floor 1,870 USD/ตัน
----------------
บทสรุปส่งท้าย
ตลาดโลหะนอกกลุ่มเหล็กในสัปดาห์หน้าแม้ยังถูกกดดันจากดอกเบี้ยและค่าเงิน แต่ปัจจัยด้านอุปทานที่ตึงตัวทำให้ราคายังมีแนวโน้มฟื้นตัว โดยเฉพาะทองแดงและสังกะสีที่ได้รับแรงหนุนจาก Supply disruption ขณะที่อลูมิเนียมยังเสี่ยงจาก Stock ต่ำสุดในรอบศตวรรษ
---------------
SO OK TRADING : พันธมิตรทางธุรกิจของคุณ
SO OK TRADING : FAST SHARP RELIABLE
VISIT US AT : WWW.SOOKTRADING.COM
FACEBOOK : SO OK TRADING
--------------
SO OK TRADING : ตัวจริงในธุรกิจ Non Ferrous จากประเทศไทย