「2026霍尔木兹战争:全球能源沸腾 —— 原油、化肥、石脑油与铝震撼世界经济」 SO OK TRADING|2026年8月18日
最后更新: 18 8月 2026
1207 浏览量
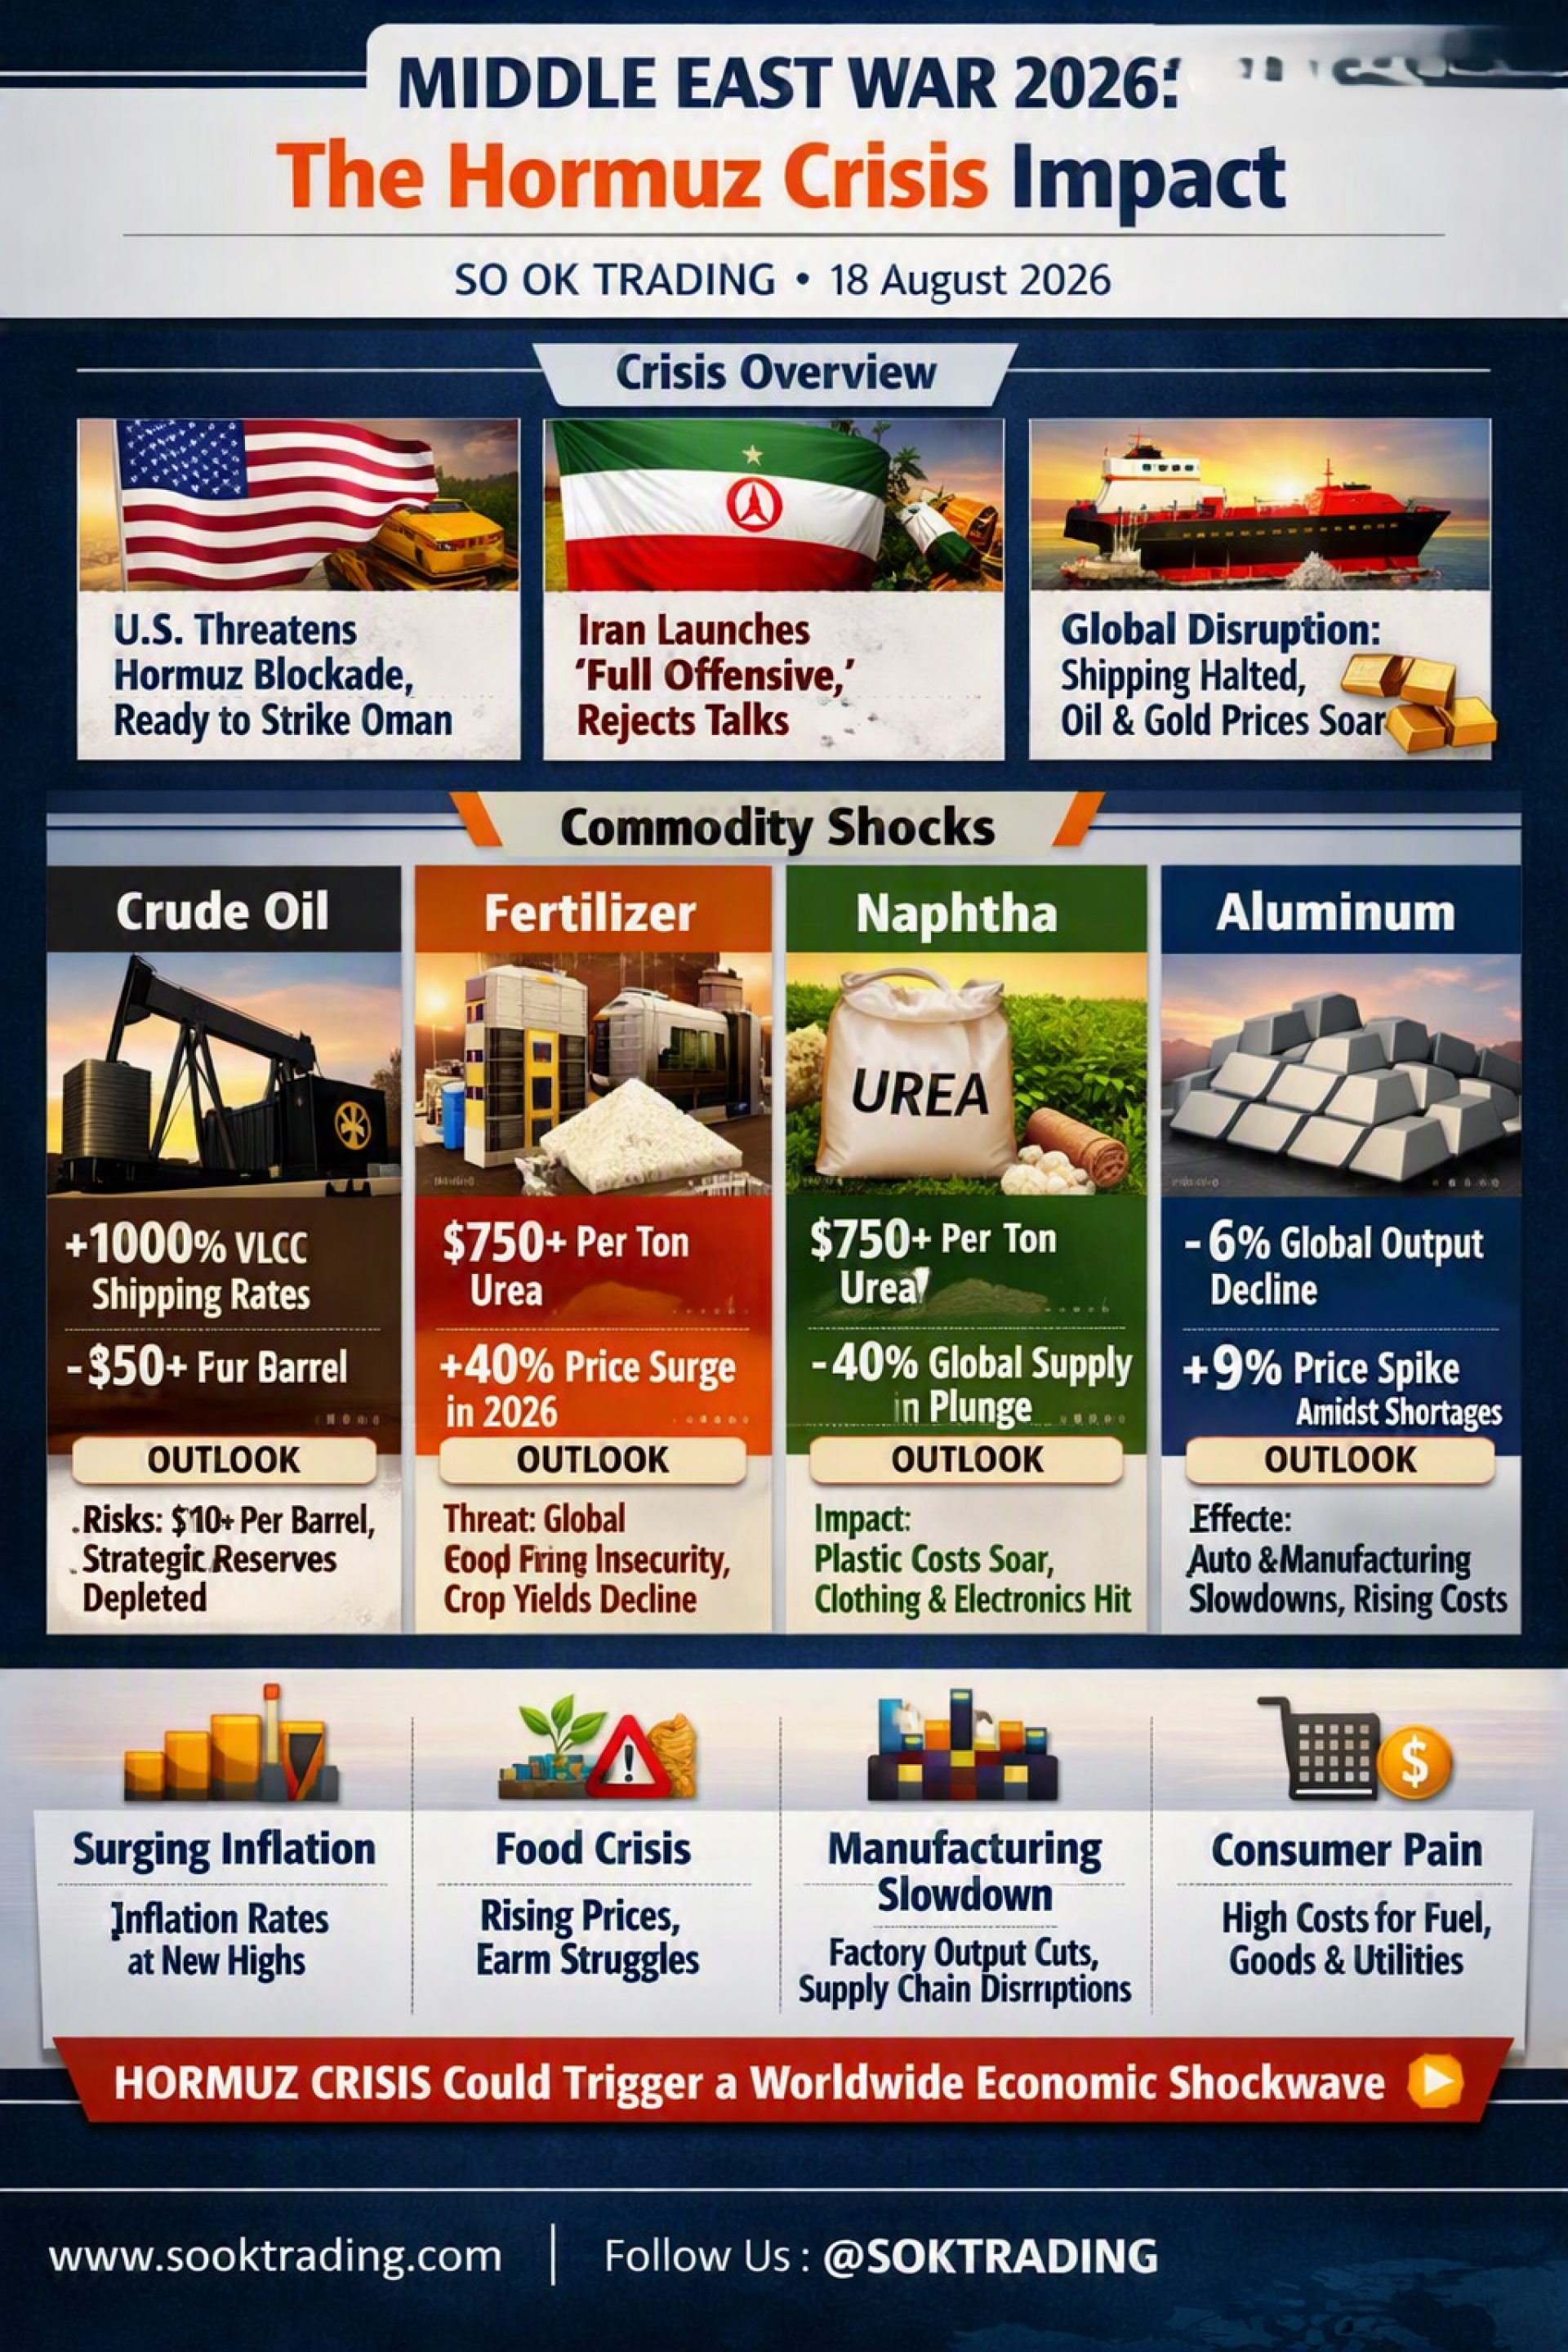
中东战争2026:霍尔木兹的定时炸弹 —— 石油、化肥、石脑油与铝震撼全球
SO OK TRADING : 2026年8月18日
形势概览
美伊之间的60天停火谅解备忘录(MoU)于8月17日到期,紧张局势骤然升至最高点:
美国:拒绝延长停火,威胁控制霍尔木兹海峡,并警告若阿曼与伊朗合作将发动攻击
伊朗:战略转向“全面进攻”,拒绝秘密谈判,推进与阿曼的协议
全球经济:航运几乎停滞,石油与黄金价格飙升,全球能源贸易结构面临严重风险
各商品影响
⛽ 原油
VLCC(超大型油轮)租金飙升10倍 → 成本增加每桶5美元
布伦特原油突破90美元 → 全球通胀再度加剧
展望:若霍尔木兹海峡持续封锁,油价可能突破100美元/桶,各国战略储备或将耗尽。
石脑油 (Naphtha)
现货价格:747.24美元/吨(同比 +34.78%)
全球供应减少40% → 亚洲与欧洲的石化工厂减产至70%
展望:塑料原料与纺织品成本持续上涨 → 包装、服装、家电等消费品全球范围内价格走高。
化肥(尿素)
泰国进口价突破24,000–25,000泰铢/吨
预计2026年平均价格较去年上涨40%
展望:全球农业成本高企、产量下降 → 食品安全风险加剧,尤其在发展中国家。
铝
阿联酋EGA工厂遭袭后仅维持18%产能
巴林Alba工厂减产20%
全球产能下降5% → 铝价即时上涨8%
展望:汽车、家电、包装等铝需求产业面临成本上升与供应短缺风险。
对泰国的影响
农业:尿素肥料成本高企 → 农民利润下降
消费者:面临“物价高、工资不变” → 电费、燃油、食品与生活用品全面上涨
✅ 2026年下半年展望总结
原油:全球通胀居高不下,运输成本上升
石脑油:消费品价格上涨,工厂减产
化肥:农业产量下降,食品价格上涨
铝:金属与制造业供应不足风险
只要霍尔木兹海峡局势未能缓解、停火协议未能重启,这四大关键商品将继续成为“全球经济的定时炸弹”,在2026年下半年持续推高生活成本。
SO OK TRADING : 您的商业合作伙伴 FAST | SHARP | RELIABLE www.sooktrading.com Facebook: SO OK TRADING

相关文章
An analysis of the aluminum market in 2026 indicates a likely continued market deficit and upward price pressure, driven by constrained supply and resilient demand from green energy sectors. However, significant volatility is expected due to policy uncertainties and the potential for new Indonesian supply to eventually balance the market.
Key Drivers and Projections for 2026
Supply Side Analysis
Capacity Constraints: China's primary aluminum output is approaching its self-imposed 45 million-tonne capacity cap, limiting global supply growth.
Power Challenges: Smelters outside of China face intense competition for power from energy-intensive sectors like AI data centers, which are willing to pay higher prices for long-term contracts. This has kept significant capacity offline in Europe and the US.
Production Disruptions: Outages and potential shutdowns at existing smelters in Iceland and Mozambique further tighten the market.
Scrap Supply Pressure: The EU's planned implementation of the Carbon Border Adjustment Mechanism (CBAM) and potential scrap export tariffs in spring 2026 are expected to impact global scrap flows, creating regional shortages and price volatility.
New Capacity: Indonesia is a key source of new supply, with several projects in the pipeline. However, analysts suggest the pace of the ramp-up may be slower than expected due to infrastructure and policy challenges, meaning it is unlikely to fully offset near-term tightness.
Demand Side Analysis
Green Transition Demand: Demand from "green" sectors such as solar panels, new energy vehicles, and energy transition infrastructure remains strong, providing fundamental support for the market.
Substitution Effect: Aluminum's wide price discount relative to copper has encouraged substitution in electrical applications, acting as a tailwind for demand and prices.
Construction and Automotive: The construction and automotive industries continue to be major consumers, with growing demand for lightweight, low-carbon aluminum products.
Price Forecasts and Volatility
The market is expected to remain in a deficit in 2026, with estimates ranging from 200,000 to 600,000 tonnes. This structural tightness is leading most analysts to forecast sustained or rising prices.
Bullish Views: Analysts at Bank of America project prices of $3,000/tonne as early as 2026. J.P. Morgan also expects prices to approach $3,000/tonne in Q1 2026. ING forecasts an average price of $2,900/tonne for the year.
Bearish/Conservative Views: Goldman Sachs is an outlier, forecasting prices to decline to $2,350/tonne by Q4 2026, anticipating a market surplus later in the year. SMM forecasts a "high first, then lower" pattern, with prices finding equilibrium in the $2,700–$2,800/tonne range by year-end.
Premiums: Regional premiums, particularly the US Midwest premium, are expected to remain high and volatile due to tariffs and regional supply dynamics, creating a disconnect from the LME benchmark price.
In essence, 2026 is projected to be a year of high volatility where participants need to focus on scenario readiness rather than relying on a single price forecast, as geopolitical and energy policies significantly influence regional supply and costs
31 12月 2025
铝市场 Q3/2026 – 全面深入展望
BY SO OK TRADING | 2026年7月7日
2026年第三季度,成为亚洲铝采购商和使用者的“重大考验”
7 7月 2026
