《2026年泰国海产品与饮料产业展望:SEAFOOD & BEVERAGE THAILAND —— 经济视角与全球舞台上的角色》
最后更新: 19 7月 2026
2059 浏览量
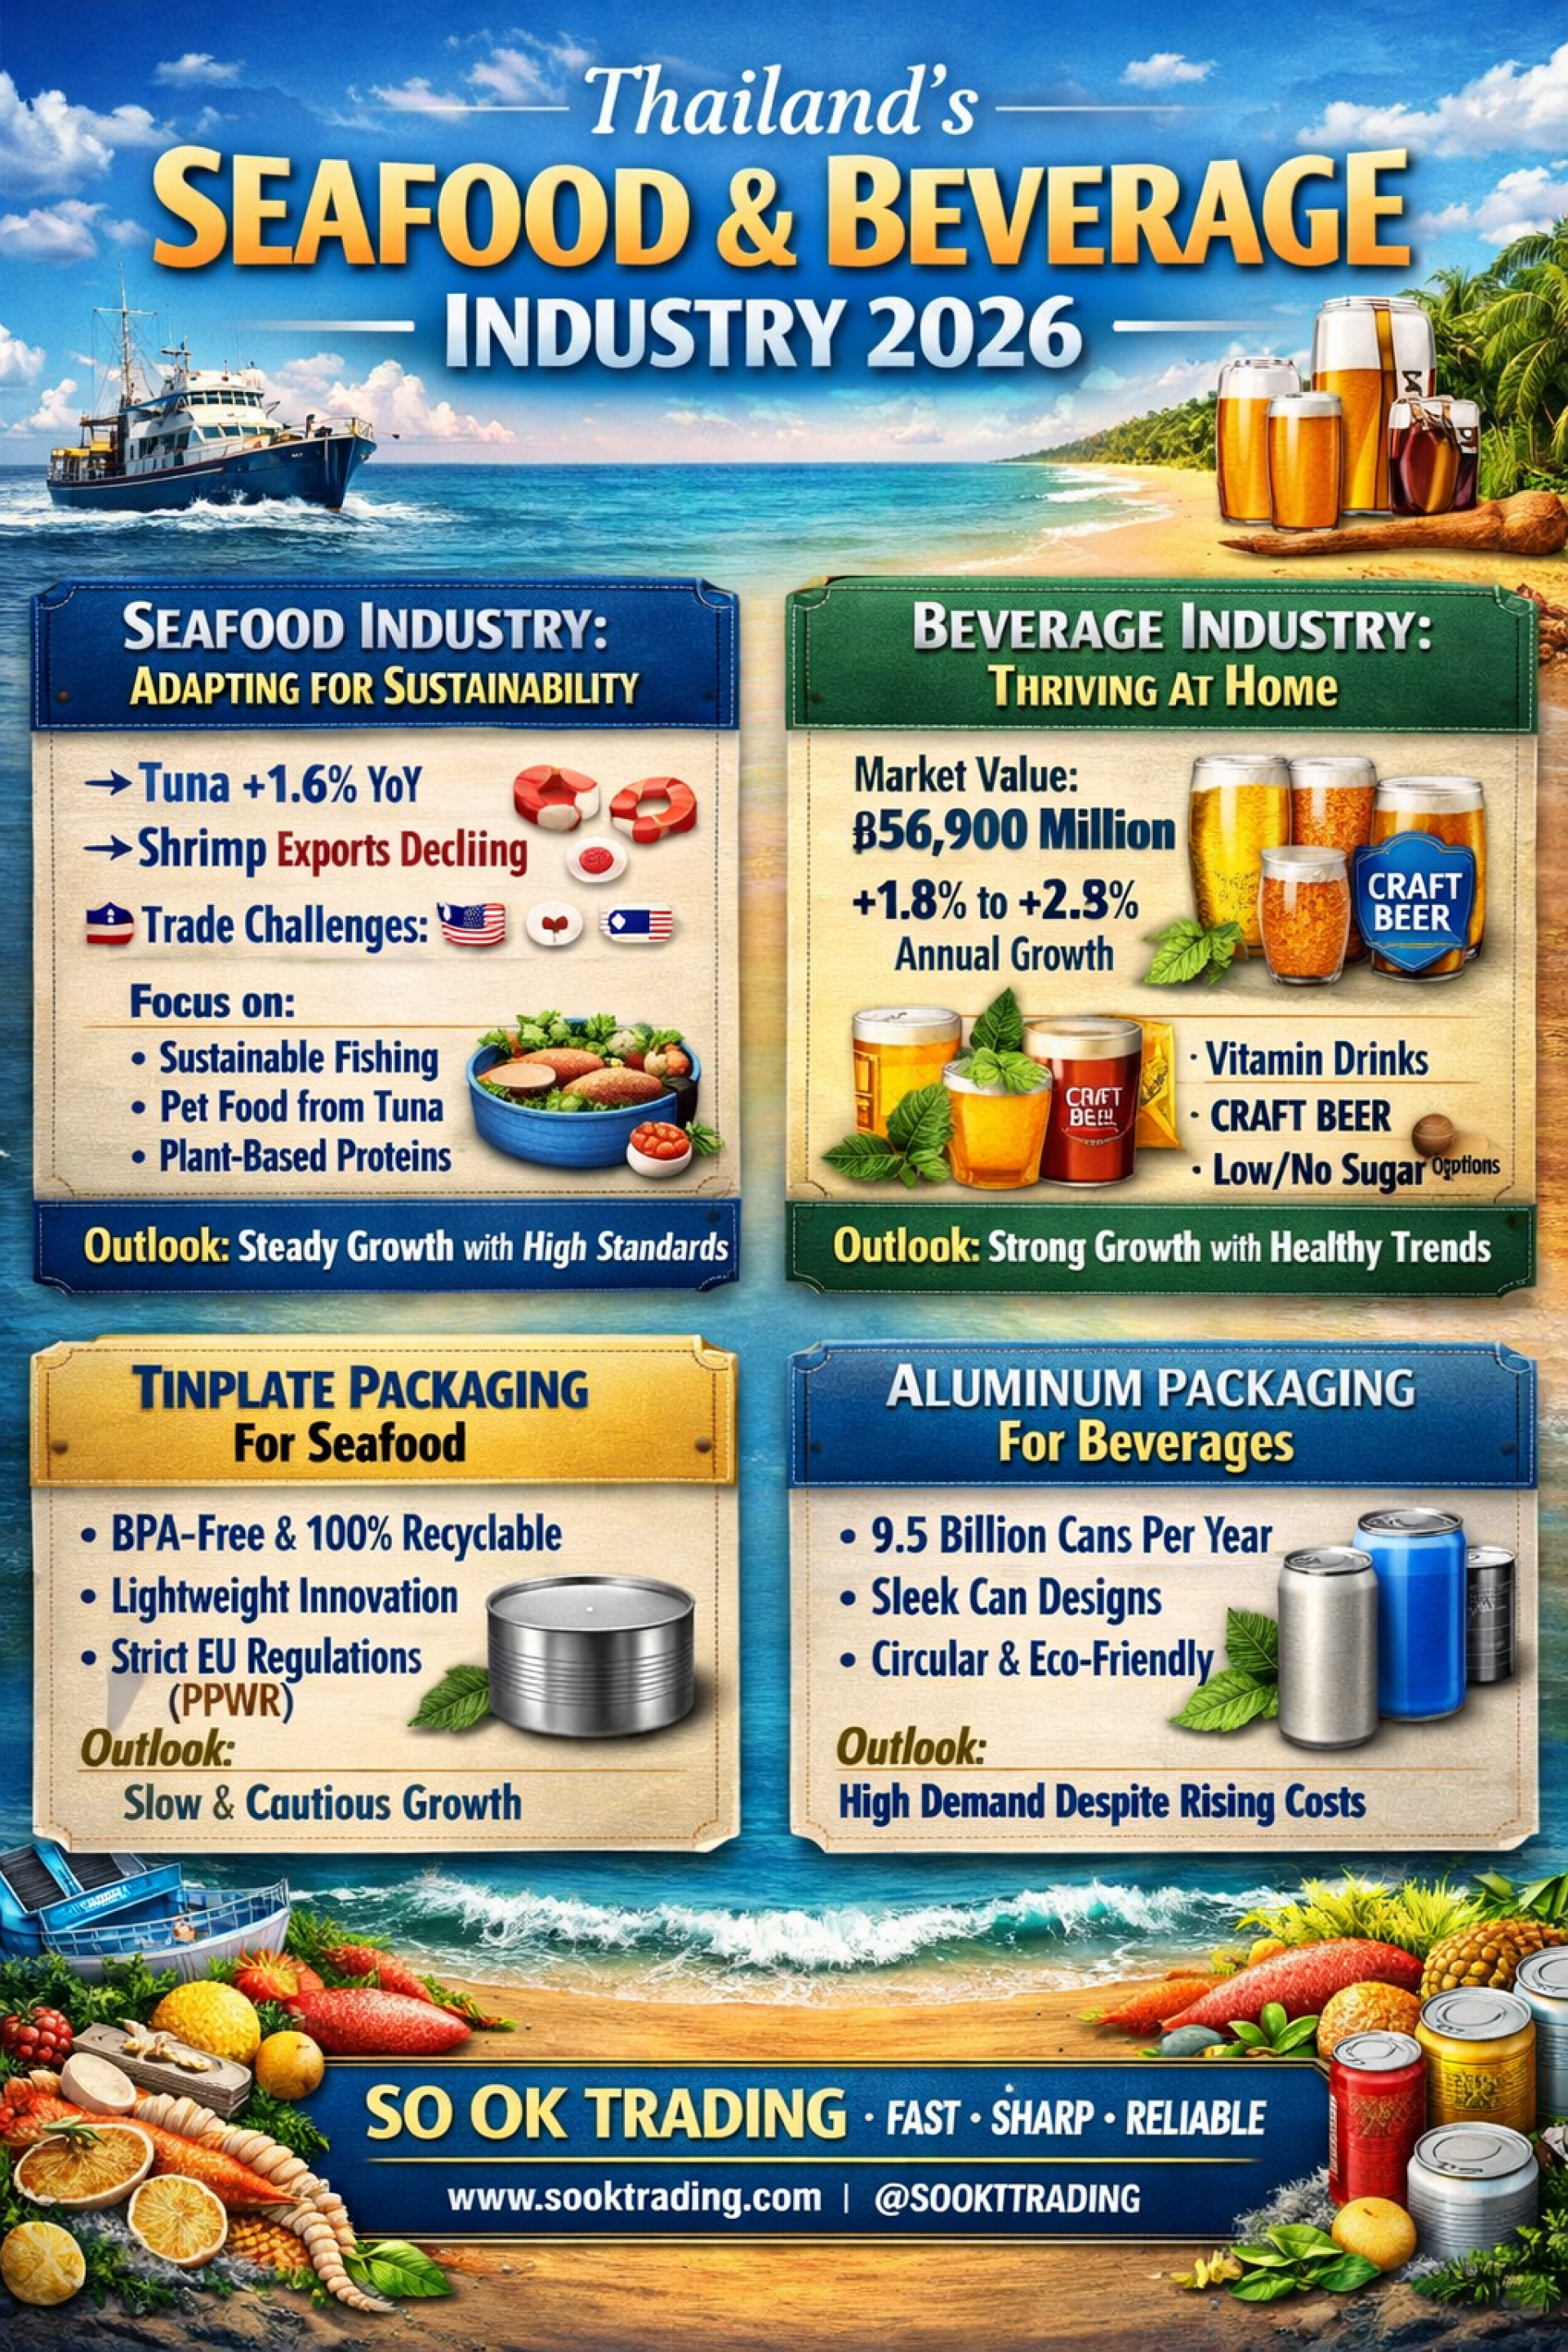
泰国海产品与饮料产业概览 2026
SO OK TRADING | 2026年7月19日
2026年是泰国海产品与饮料产业的重要转折点。两大产业依然是国家经济的支柱,但同时也面临全球经济放缓、贸易壁垒,以及消费者偏好逐渐转向“健康与可持续”的挑战。
海产品产业:从海洋到可持续发展
泰国海产品出口正面临巨大压力。主要市场如美国、日本和中国需求疲软,进口关税进一步加剧了挑战。曾经的主力产品泰国虾在成本竞争力上已被厄瓜多尔和印度超越,而金枪鱼罐头则保持了约+1.6%的小幅增长。
值得关注的是,Thai Union 等大型企业正在转向合法捕捞、提升可持续标准,并开发高附加值的新产品,如金枪鱼宠物食品和植物性替代蛋白。这表明泰国海产品产业的未来不再是价格竞争,而是创造符合健康与环保趋势的新价值。
展望: 虽然增长有限,但如果泰国能够坚持可持续与创新之路,仍将在全球市场中保持高标准和可信赖的地位。
饮料产业:国内市场依然强劲
与海产品不同,泰国饮料产业展现出更为积极的前景。旅游业和健康趋势推动国内市场增长。消费者越来越偏好维生素饮料、碱性水以及低糖/无糖饮料。同时,酒精饮料市场也因服务业和娱乐业的复苏而回暖,精酿啤酒和社区酒开始受到欢迎。
尽管出口至 CLMV 市场有所放缓,但国内市场依然稳步增长,总规模突破569亿泰铢,预计年均增长率为1.8%–2.8%。
展望: 健康导向和便利性的产品将继续推动增长。若生产商能调整配方以符合甜味税,并应对包装成本上升,将能保持竞争优势。
金属包装:值得关注的转折点
锡板(Tinplate)— 海产品包装
金枪鱼和沙丁鱼罐头仍主要使用 锡板/TFS,但随着出口下降,需求趋缓。欧盟 PPWR 法规 要求罐头必须不含 BPA 并且实现100%可回收。轻量化(Lightweighting)研究也在进行,以降低运输成本和碳足迹。然而,原材料价格波动仍是主要挑战。
展望 Tinplate: 市场增长缓慢且脆弱,但若能满足安全与环保标准,泰国仍可维持出口市场。然而,未来的关键在于创造附加价值,而非单纯的价格竞争。
铝罐(Aluminum)— 饮料包装
饮料罐市场前景更为乐观。铝罐 符合现代消费者“随时随地”的消费习惯,并契合循环经济理念,可无限次回收。泰国市场规模超过95亿罐/年,随着精酿啤酒、无糖碳酸饮料和即饮咖啡的流行而持续扩大。新趋势 Sleek Cans(直接在罐体印刷图案)也正在兴起,有助于减少塑料混合废弃物。
挑战在于供应限制和地缘政治紧张导致的铝价飙升,生产商需承担高昂成本。
展望 Aluminum: 尽管成本上升,铝罐仍将是饮料市场的核心材料。若能有效控制成本并推动包装创新,将成为建立竞争优势的重要机会。
总结
2026年,泰国海产品与饮料产业面临重大挑战。整体出口预计仅增长1.3%–2.0%(约360.9亿美元)。然而,值得关注的是产业正从 价格竞争 转向 附加价值创造 ——通过健康产品、精品产品以及环保包装实现转型。
若能成功适应,这两大产业仍将是泰国经济的坚实支柱,并有能力应对快速变化的全球环境。
SO OK TRADING — FAST • SHARP • RELIABLE 您在金属包装与铝罐产业中的商业伙伴 www.sooktrading.com Facebook: SOOK TRADING
拥有超过15年经验,我们是泰国金属与铝包装行业的真正专家

相关文章
「中国放缓,世界再平衡 —— 2026年下半年全球经济转折点与泰国新机遇」
SO OK TRADING | 2026年6月17日
在2026年下半年,中国经济进入“稳定放缓”阶段。政府首次将GDP目标设定在 4.5%–5.0%,这是三十年来首次低于5%。这一举措意味着中国正从数量型增长转向质量型增长,强调“创新与可持续发展”。
中国政府正在推进第十五个五年计划,重点打造“新质生产力(New Quality Productive Forces)”,加快人工智能、清洁能源和智能制造等领域的技术升级。
在中国推动全球再平衡的背景下,泰国迎来了新的黄金机遇:
17 6月 2026
An analysis of the aluminum market in 2026 indicates a likely continued market deficit and upward price pressure, driven by constrained supply and resilient demand from green energy sectors. However, significant volatility is expected due to policy uncertainties and the potential for new Indonesian supply to eventually balance the market.
Key Drivers and Projections for 2026
Supply Side Analysis
Capacity Constraints: China's primary aluminum output is approaching its self-imposed 45 million-tonne capacity cap, limiting global supply growth.
Power Challenges: Smelters outside of China face intense competition for power from energy-intensive sectors like AI data centers, which are willing to pay higher prices for long-term contracts. This has kept significant capacity offline in Europe and the US.
Production Disruptions: Outages and potential shutdowns at existing smelters in Iceland and Mozambique further tighten the market.
Scrap Supply Pressure: The EU's planned implementation of the Carbon Border Adjustment Mechanism (CBAM) and potential scrap export tariffs in spring 2026 are expected to impact global scrap flows, creating regional shortages and price volatility.
New Capacity: Indonesia is a key source of new supply, with several projects in the pipeline. However, analysts suggest the pace of the ramp-up may be slower than expected due to infrastructure and policy challenges, meaning it is unlikely to fully offset near-term tightness.
Demand Side Analysis
Green Transition Demand: Demand from "green" sectors such as solar panels, new energy vehicles, and energy transition infrastructure remains strong, providing fundamental support for the market.
Substitution Effect: Aluminum's wide price discount relative to copper has encouraged substitution in electrical applications, acting as a tailwind for demand and prices.
Construction and Automotive: The construction and automotive industries continue to be major consumers, with growing demand for lightweight, low-carbon aluminum products.
Price Forecasts and Volatility
The market is expected to remain in a deficit in 2026, with estimates ranging from 200,000 to 600,000 tonnes. This structural tightness is leading most analysts to forecast sustained or rising prices.
Bullish Views: Analysts at Bank of America project prices of $3,000/tonne as early as 2026. J.P. Morgan also expects prices to approach $3,000/tonne in Q1 2026. ING forecasts an average price of $2,900/tonne for the year.
Bearish/Conservative Views: Goldman Sachs is an outlier, forecasting prices to decline to $2,350/tonne by Q4 2026, anticipating a market surplus later in the year. SMM forecasts a "high first, then lower" pattern, with prices finding equilibrium in the $2,700–$2,800/tonne range by year-end.
Premiums: Regional premiums, particularly the US Midwest premium, are expected to remain high and volatile due to tariffs and regional supply dynamics, creating a disconnect from the LME benchmark price.
In essence, 2026 is projected to be a year of high volatility where participants need to focus on scenario readiness rather than relying on a single price forecast, as geopolitical and energy policies significantly influence regional supply and costs
31 12月 2025
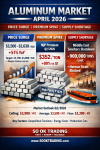
铝市场 2026年4月 —— 价格飙升 Premium 高企 供应短缺
2026年4月,全球铝市场迎来了“近四年来最火热的时刻”。
价格飙升至历史高位,波动剧烈,企业必须高度关注!
16 4月 2026
