“Aluminum: The Future of Global Packaging — From Coil to Can, Exploring Market Growth and New Perspectives 2026–2035 by SO OK TRADING”
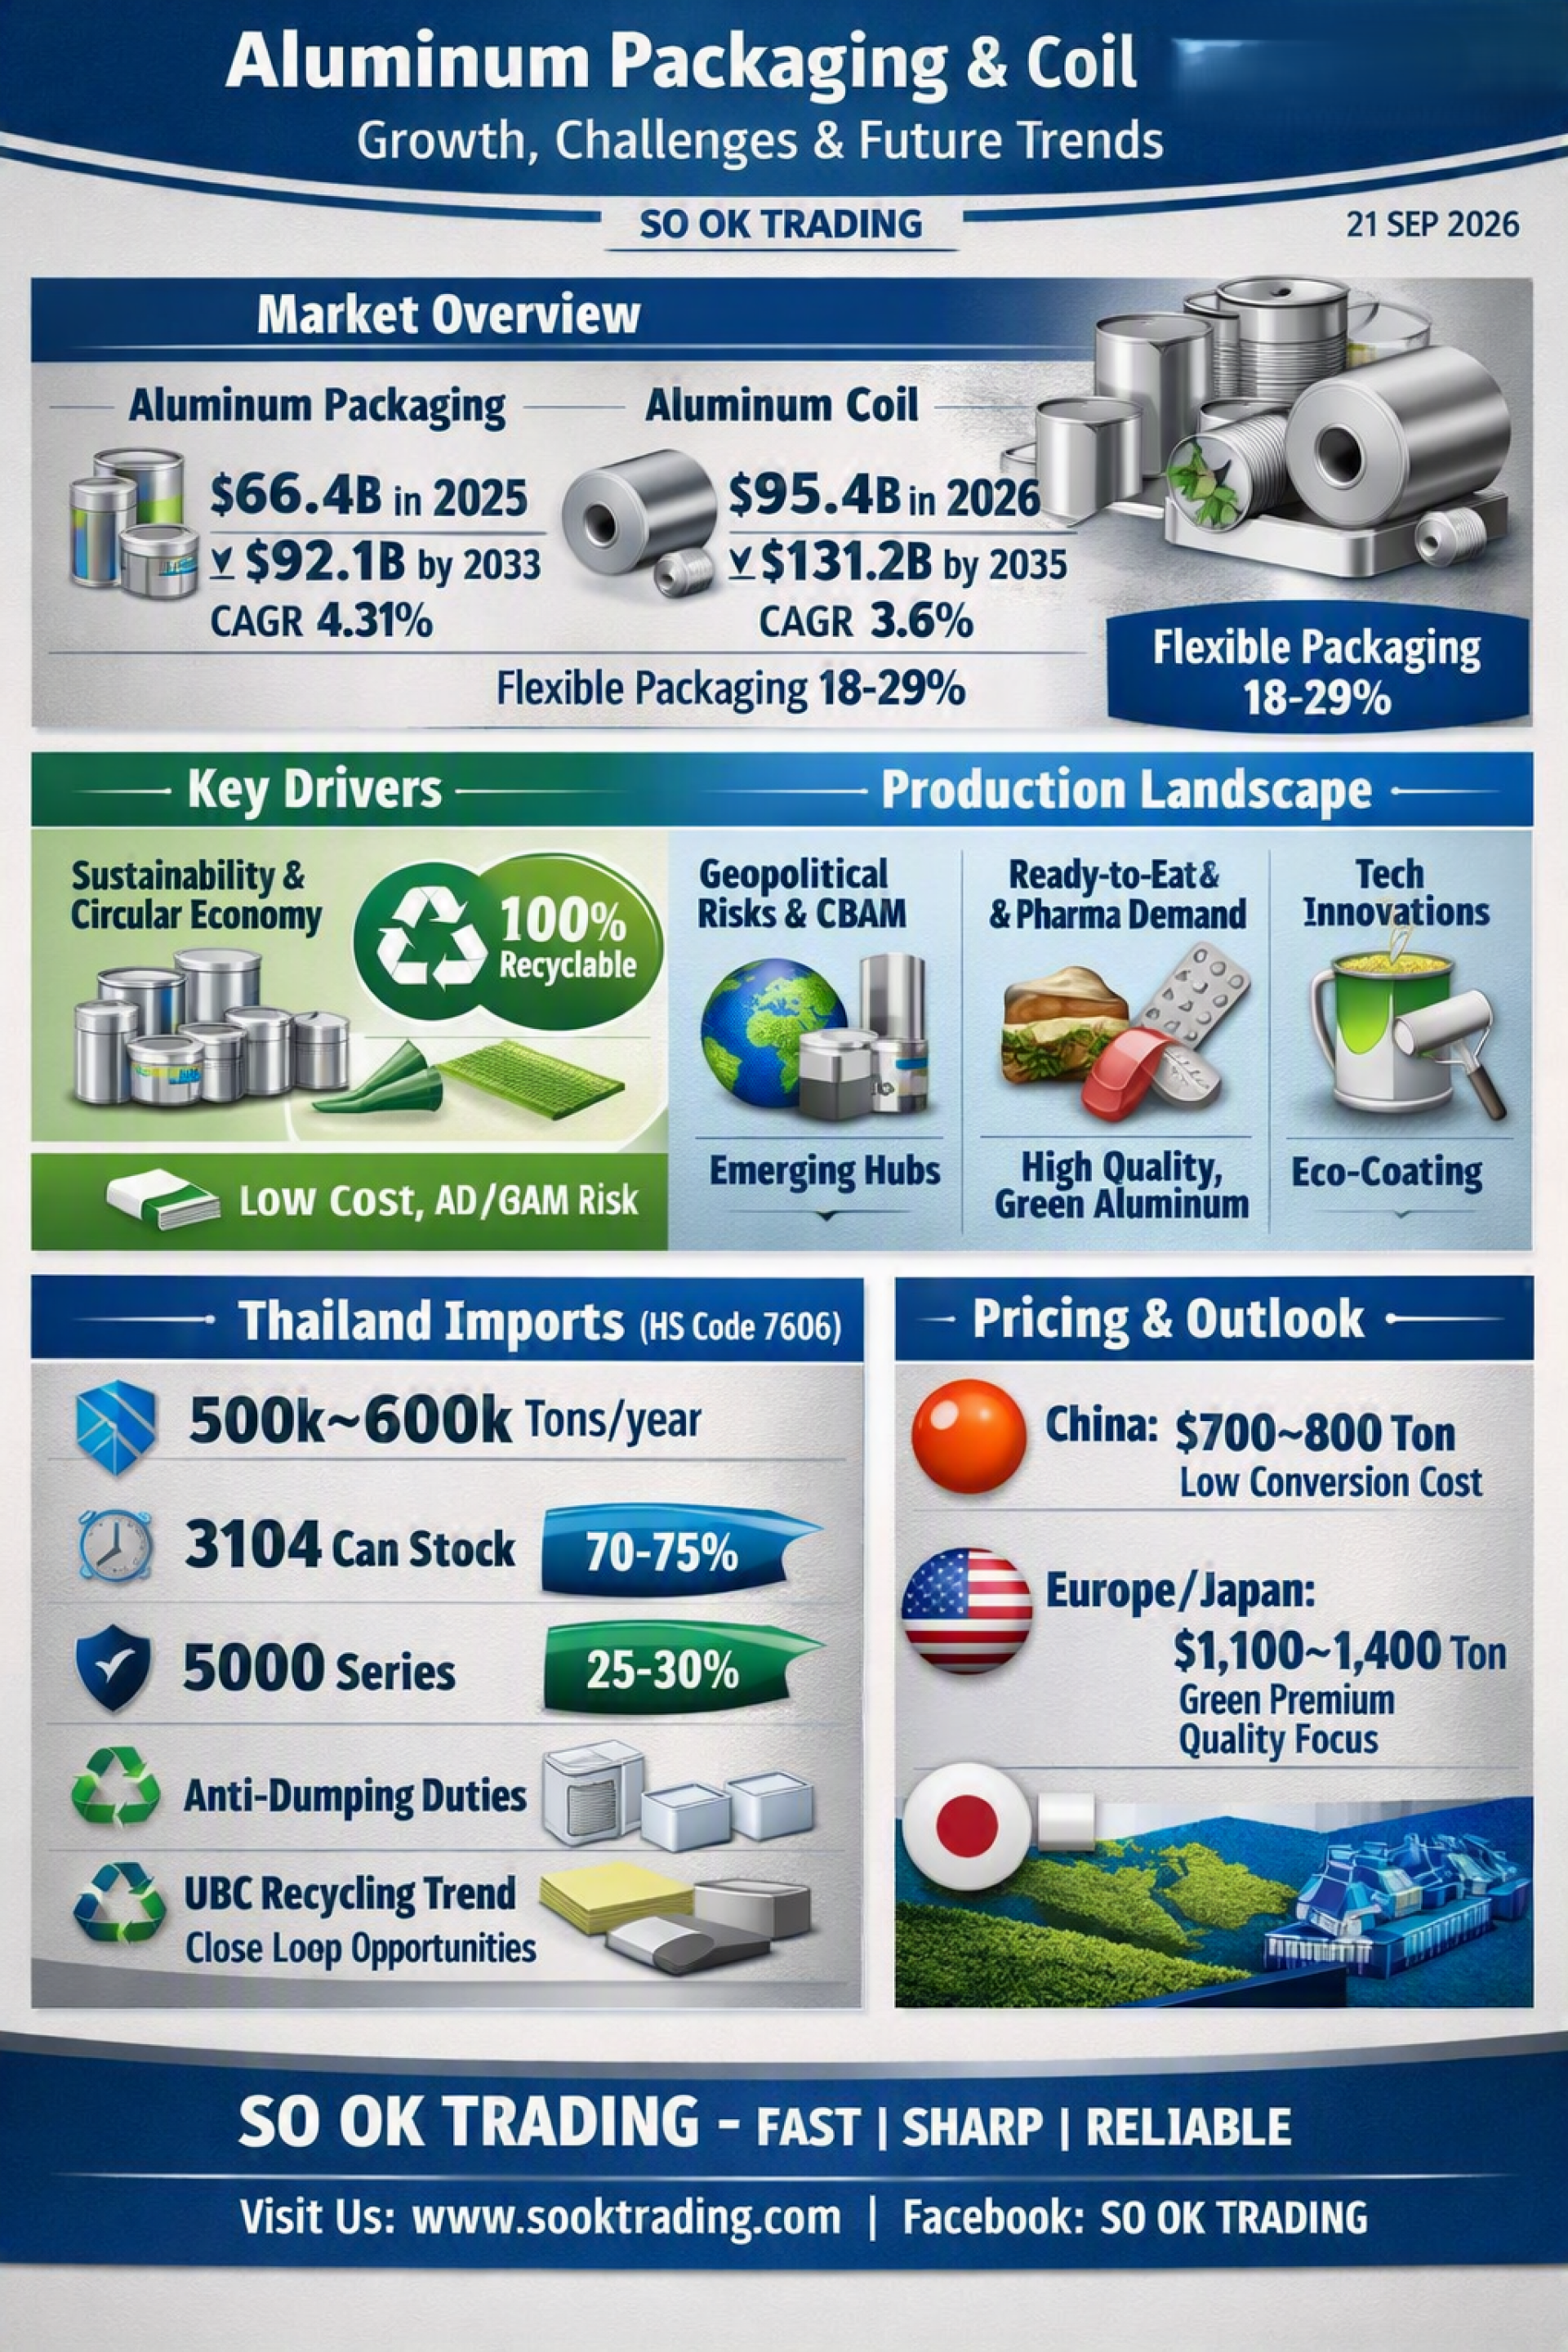
Aluminum Packaging & Coil Market: Growth, Challenges, and Future Outlook
SO OK TRADING | September 21, 2026
The aluminum packaging and coil industry is undergoing a major transformation. Driven by sustainability and the circular economy, aluminum has become the “material of the future” in global packaging. With its ability to be 100% recycled without loss of quality, aluminum is meeting the rising demand in the food, beverage, and pharmaceutical sectors worldwide.
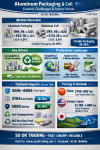
Global Market Overview
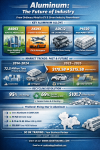
Aluminum Packaging: USD 66.4 billion (2025) → USD 92.1 billion (2033), CAGR ~4.31%
Aluminum Coil: USD 95.4 billion (2026) → USD 131.2 billion (2035), CAGR ~3.6%
Flexible Packaging: Accounts for 18–29% of demand
Key Drivers & Trends
Circular Economy & Sustainability: Global brands shifting from PET and glass to aluminum cans
Supply Risk & Geopolitics: Middle East instability, EU CBAM, U.S. tariffs
Ready-to-Eat & Pharma Growth: Rising demand for aluminum foil rolls and blister packs
Tech Innovation:
Downgauging: Thinner yet stronger coils
Eco-friendly Coating & Printing: Corrosion resistance and premium packaging design
Production Landscape
China: Largest producer, low cost but facing CBAM and anti-dumping risks
Thailand & India: Emerging hubs for diversified sourcing
Europe & Turkey: Focus on Green Aluminum, higher costs
Japan & South Korea: High precision and quality, limited supply
Major Manufacturers
China: Henan Zhongfu, Henan Mingtai, CHAL Aluminium, Shanghai AIYIA
Global Tier-1: Novelis (US), Constellium (France), UACJ (Japan/Thailand), Alcoa (US/Australia)
Thailand Import Trends (HS Code 7606)
2011–2015: 100% import dependency (250k–350k tons/year)
2016–2021: Rapid growth (400k–550k tons/year), UACJ plant established in Thailand + surge of Chinese coils
2022–Present: Stable (500k–600k+ tons/year), valued at USD 1.5–1.8 billion
Aluminum Can Stock Usage in Thailand
3104 Can Body Stock: ~70–75% (beer & beverage cans)
5000 Series (5182/5052): ~25–30% (food cans, lids, tabs) — still heavily imported
Future Considerations
Anti-Dumping (AD): Stricter measures on Chinese imports, plus environmental tariffs (CBAM)
UBC Recycling Trend: Thailand imports >USD 800 million in aluminum scrap annually, opening opportunities for close-loop recycling and domestic coil production
B2B Pricing Structure
Net Price = LME Cash Base + Regional Premium (MJP) + Conversion Premium
China: Lowest conversion premium (USD 700–800/ton)
Europe/Japan: Higher premium, Green standards and quality focus (USD 1,100–1,400/ton)
Outlook & Industry Direction
Sourcing: China remains dominant, but Thailand and India are rising as alternative hubs; Europe and Japan lead in Green Aluminum
Thailand Imports: Stable volumes, continued reliance on 5000 Series
Pricing: China retains cost advantage, while Europe/Japan differentiate with sustainability and quality
Industry Trends: Expansion of UBC recycling, alloy innovation (e.g., 3000 Series for can ends and tabs) to improve recyclability
✅ Conclusion
The global aluminum packaging and coil market is set for steady growth, powered by sustainability, recycling, and the circular economy. While China remains the primary supplier, regions like Thailand, India, and Europe are carving out new roles. The future of competition will shift from price to quality, technology, and carbon footprint reduction, defining the industry’s trajectory in the coming decade.
SO OK TRADING — FAST | SHARP | RELIABLE www.sooktrading.com Facebook: SO OK TRADING