“China Aluminum Market 2026: From Price Wars to a Low-Carbon Era — Transforming with New Power from EVs and Renewable Energy, Towards the Future of Green Aluminum & Global Expansion” SO OK TRADING | 16 OCT 2026
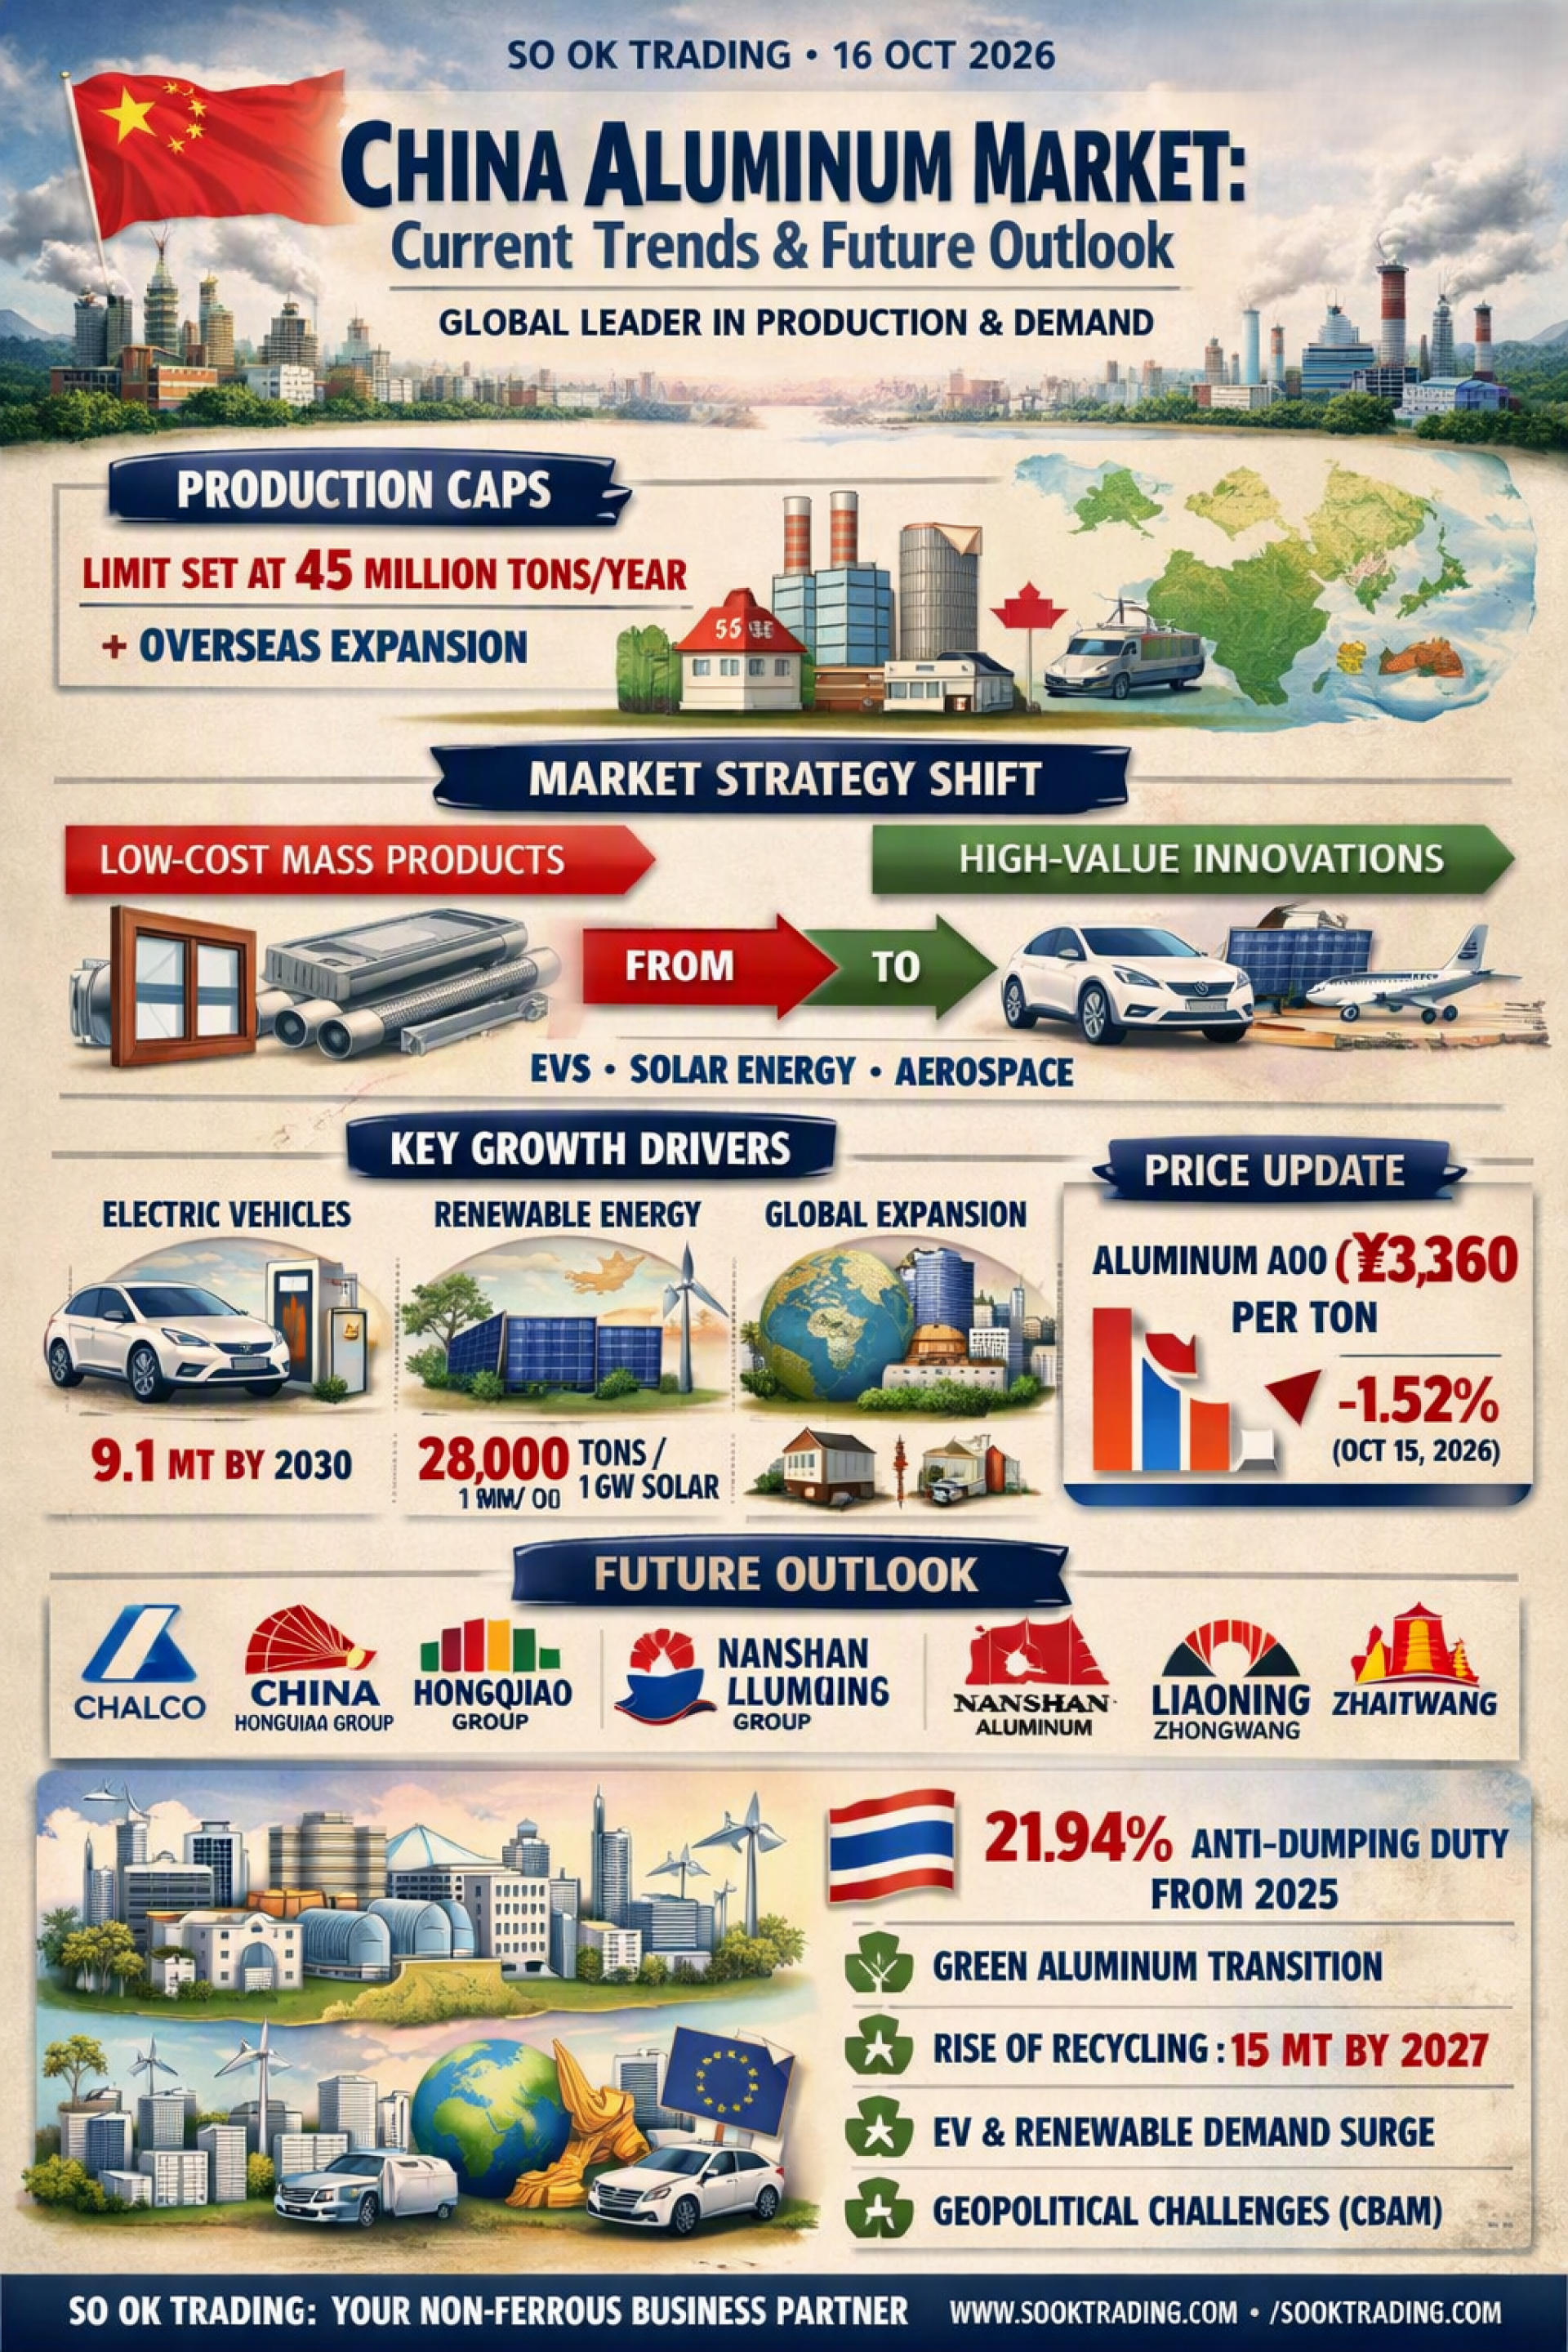
China Aluminum Market: Current Situation and Future Outlook
SO OK TRADING | 16 OCT 2026
Introduction
China’s aluminum industry stands at the heart of the global market, both in terms of production and consumption. With the world’s largest capacity and immense domestic demand, the sector is now facing a profound structural transformation. Production caps, price competition, environmental measures, and geopolitical pressures are reshaping the industry. This article explores the latest developments, key drivers, and future outlook for China’s aluminum market.
Overview and Production Policy
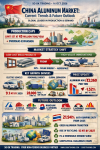
The Chinese government has capped primary aluminum production at 45 million tons per year to control energy use and reduce emissions. This restriction prevents unlimited expansion as in the past. As a result, major companies such as China Hongqiao Group and Nanshan Aluminum are investing abroad, particularly in Indonesia and the Middle East, to secure bauxite resources, access clean energy, and avoid Western tariff barriers.
Escaping the Price War
China’s economic slowdown and the slump in the real estate sector have sharply reduced demand for general-grade aluminum products such as window frames and door handles. In response, producers are shifting strategies from low-cost mass production to high-value innovations — aluminum for Electric Vehicles (EVs), renewable energy infrastructure, and aerospace components.
Demand Drivers
Electric Vehicles (EVs)
EVs use 1.5–2 times more aluminum than internal combustion cars.
In 2025, China’s NEV sales reached 16.49 million units, with over 48.97 million units on the road.
Automotive aluminum demand rose from 3.8 million tons (2018) to 7.5–8 million tons (2026), and is expected to reach 9.1 million tons by 2030.
Renewable Energy (Solar PV & Wind)
A 1 GW solar project requires about 28,000 tons of aluminum.
Despite a slowdown to ~200 GW of new installations in 2026, annual demand remains high at 2–3.5 million tons.
Overseas Investment
Chinese producers are expanding into ASEAN and the Middle East to secure resources and mitigate trade risks.
Key Players and Production Bases
Chalco (Aluminum Corporation of China) – largest state-owned enterprise
China Hongqiao Group – world-leading private producer
Shandong Nanshan Aluminum & Liaoning Zhongwang Group – major market players
Guizhou, Yunnan, Sichuan – strategic bases with bauxite and hydropower resources
Market Prices and Impact on Thailand
As of 15 October 2026, aluminum ingot A00 was priced at ¥23,260 per ton, down -1.52% from the previous day due to weaker downstream orders. In Thailand, the influx of cheap Chinese aluminum prompted the government to impose an anti-dumping duty of 21.94% (since 2025). This raised import costs and encouraged local producers to rely more on domestic raw materials.
Future Outlook: Low-Carbon & High Value-Added
Production Caps & Overseas Expansion – Domestic capacity is saturated, driving new investments abroad.
Green Aluminum Transition – Smelters are relocating to clean-energy provinces, while recycled aluminum grows rapidly.
Demand Structure Shift – From construction to EVs, Solar PV, and aerospace.
Geopolitical Challenges – EU’s CBAM and trade frictions push China toward high-value, low-carbon products.
Key Statistics
Average aluminum use per EV: 128.4 kg → 283.5 kg by 2030
Recycled aluminum share: 35% of supply (2026), targeting 15 million tons annually by 2027
U.S. market: 80–85% recycled aluminum, while China lags but grows fastest globally
Conclusion
China’s aluminum market is transitioning from quantity-driven production to quality-focused, low-carbon, high-value manufacturing. EVs, renewable energy, and overseas investments are the main growth pillars, while environmental regulations and global trade measures will define the industry’s new trajectory.
✨ SO OK TRADING — FAST • SHARP • RELIABLE Your trusted partner in the dynamic non-ferrous metals business.