“SO OK TRADING Global Metals Outlook (10–14 August 2026) — Tracking Broad-Based Bullish Signals in a CPI-Driven Week as Dollar Weakness, Tight Supply, and Market Momentum Converge.”
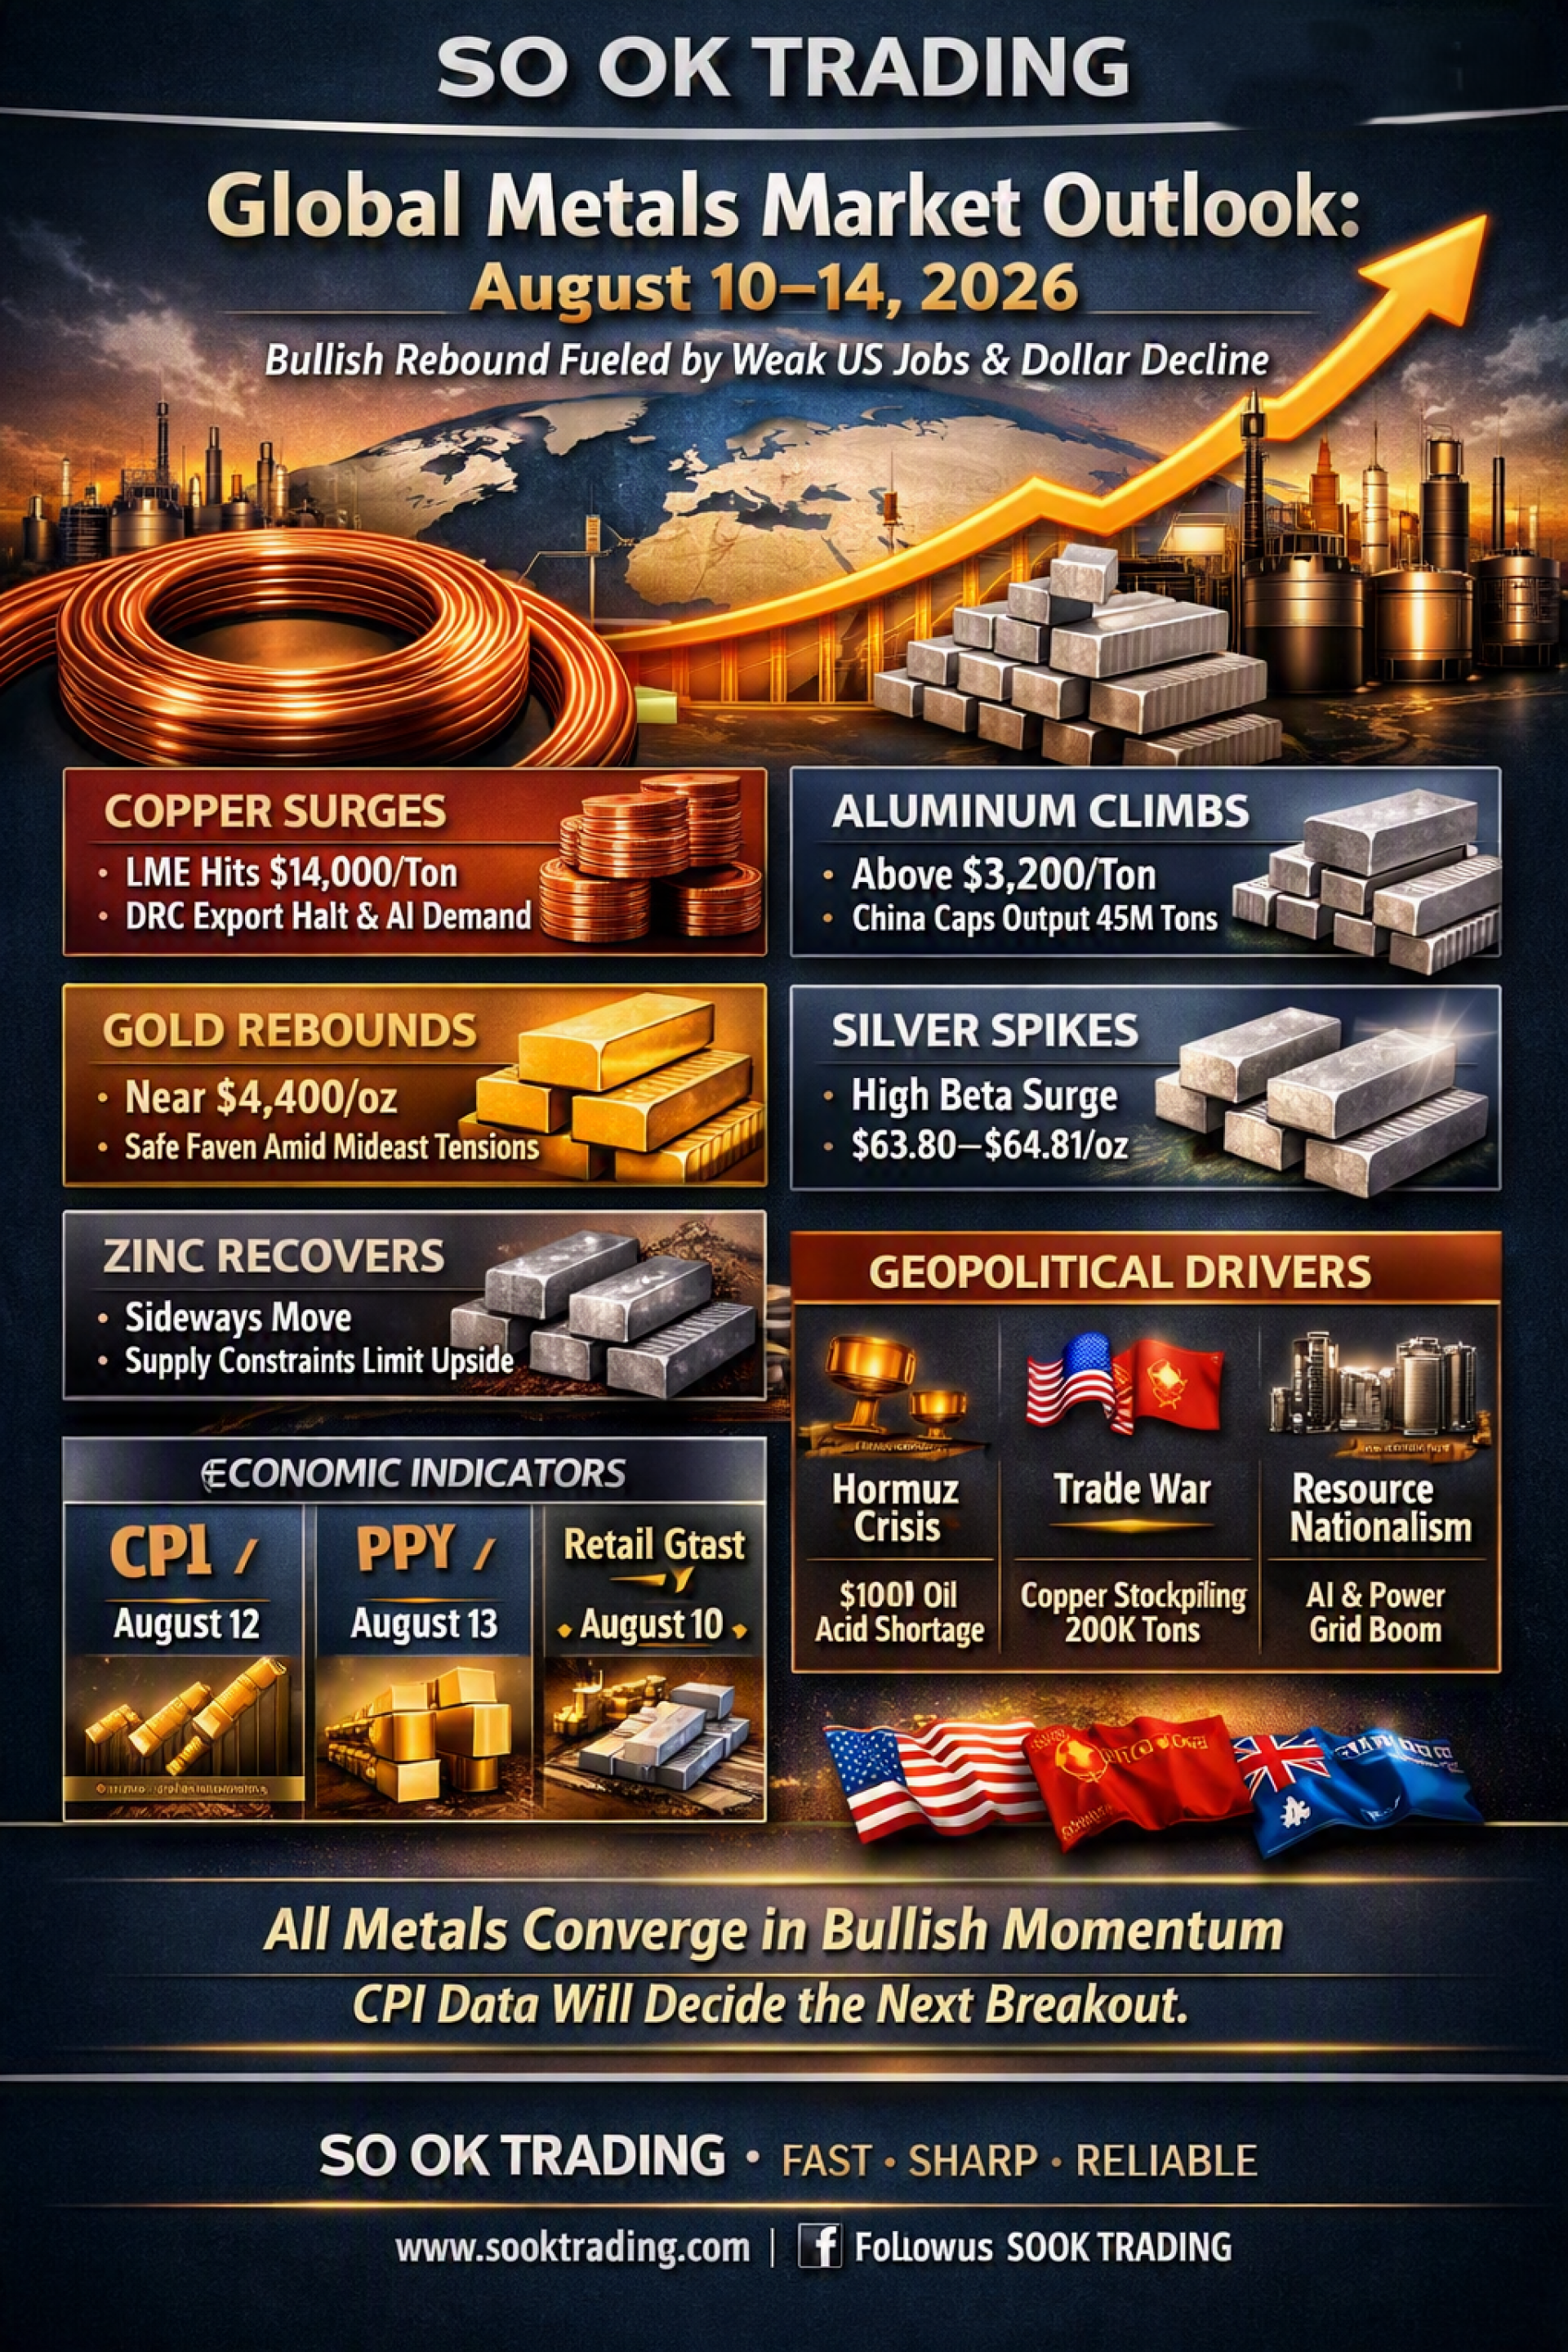
Industrial & Precious Metals Market Outlook — Next Week (10–14 August 2026)
Report by SO OK TRADING | 9 August 2026
Next week, the global metals market is entering a particularly critical phase. The unexpected downturn in U.S. nonfarm payrolls (-23,000 jobs) triggered an immediate weakening of the U.S. dollar, opening the door for a broad-based rebound across global commodities. Gold, silver, copper, and aluminum all surged simultaneously, supported by both macroeconomic factors and intensifying geopolitical tensions.
COPPER — The Star Performer, Strong and Sustained Upside Momentum
Copper continues to dominate the market. LME copper futures have surged past $14,000/ton, marking the strongest weekly gain in nearly three months.
Key drivers include:
LME copper inventories falling to an 8‑month low
The Democratic Republic of Congo (DRC) halting exports of copper and cobalt concentrates to enforce domestic processing
Rising global demand from AI infrastructure expansion and power grid upgrades
All signals point to one conclusion: “Copper’s rally is far from over.” Next week, copper may test major resistance levels, and a breakout could send prices toward previous highs.
ALUMINUM — Steady Upside, Following Copper’s Lead
Aluminum prices continue to climb, holding firmly above $3,200/ton, the highest level in several weeks.
Key factors:
China maintaining its production cap at 45 million tons, keeping Asian supply tight
Manufacturers increasingly substituting aluminum for copper due to cost advantages, boosting demand
Aluminum is expected to continue its upward trajectory alongside copper and other base metals next week.
GOLD — Strong Rebound After Negative NFP, but Still Range‑Bound
Gold has rebounded toward $4,400/oz following the shock negative U.S. jobs report, which pushed bond yields and the dollar sharply lower.
However, gold remains in a “Sideways Up” pattern — recovering but still facing periodic profit‑taking, especially near the $4,450 zone.
Geopolitical tensions in the Middle East, particularly around the Hormuz Strait and Red Sea, continue to support gold’s role as a safe‑haven asset heading into next week.
SILVER — High‑Beta Surge, Outperforming Gold
Silver, known for its amplified market response, jumped more than 4.5% on Friday, closing between $63.80–$64.81/oz.
Next week, silver may test the $65–$68/oz resistance zone, though volatility will remain significantly higher than gold.
ZINC — Recovering, but Capped by Rising Mine Supply
Zinc has rebounded on improved market sentiment, but rising global mine output is creating a potential oversupply situation.
As a result, zinc is likely to trade sideways to slightly higher, without the strong momentum seen in copper or aluminum.
Geopolitics: The Most Powerful Price Driver Right Now
1) Hormuz Strait Crisis — Deeper Impact Than Expected
Tensions between the U.S.–Israel and Iran have pushed Brent crude to $100/barrel. More critically, a global sulfuric acid shortage has emerged — a key chemical used in copper refining in Chile and the DRC.
This shortage is severely constraining global refined copper output, providing strong fundamental support for copper’s price surge.
2) Trade War — Artificial Demand Boosting Copper Prices
The U.S. delayed its decision on refined copper import tariffs, creating uncertainty. Traders responded by stockpiling copper in U.S. warehouses to hedge against future risks.
U.S. copper inventories have now surged above 200,000 tons, the highest level ever recorded, tightening global supply even further.
3) Resource Nationalism + AI Infrastructure — Long‑Term Demand Reshaping the Market
Resource‑rich nations such as the DRC and Venezuela are restricting raw ore exports to force domestic processing. Meanwhile, major economies are accelerating AI data center construction and power grid modernization.
These combined forces are pushing copper, aluminum, and silver into a prolonged phase of structural supply shortage.
U.S. Economic Data: The Decisive Factor for Gold
Next week’s CPI release will be the ultimate determinant for gold prices:
Below expectations → Gold could surge immediately
Above expectations → Fast profit‑taking likely
PPI and retail sales will also matter. If consumer spending weakens following the labor market downturn, recession fears will rise — further supporting gold as a safe‑haven asset.
Currencies to Watch: DXY, CNY, and AUD
DXY: Sharp decline. A break below 101.50 could lead to a test of 100, directly supporting gold, silver, and copper
CNY: Strengthening, boosting Chinese import demand for metals
AUD/USD: Rebounding; if the RBA holds rates and the dollar stays weak, commodity‑linked capital inflows may increase
Metals Market Summary (10–14 August 2026)
The metals market is currently experiencing a “convergence of powerful bullish forces”:
Economic slowdown
Weakening U.S. dollar
Escalating geopolitical tensions
Tight supply conditions
Copper and aluminum are leading the market. Gold and silver are supported by inflation and risk sentiment. Zinc is recovering but constrained by rising mine supply.
Next week’s CPI will determine the overall direction. If CPI comes in lower than expected, the metals market could enter a new synchronized bullish phase.
SO OK TRADING — Your Trusted Partner in the Metals Industry
FAST • SHARP • RELIABLE www.sooktrading.com Facebook: SO OK TRADING