Share

“Base Metal Outlook 2026–2027: Tin & Copper as Rising Stars in the AI Era — An In‑Depth Analysis of LME Prices, Stocks, and Premiums Amid Geopolitical Shifts by SO OK TRADING; 6 July 2026”

Last updated: 6 Jul 2026
3025 Views

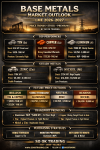
 BASE METAL MARKET OUTLOOK: LME 2026–2027
Price Trends · Stock Levels · Premiums BY SO OK TRADING : 6 JULY 2026

 
The world of Base Metals is heating up like never before. Geopolitical tensions, conflicts in the Middle East, and surging energy costs are shaking global markets, causing sharp divergences in Supply and Stock across different metals — directly shaping future price directions.

 
Rising Stars
Tin (Sn)
Stock: ~8,455–8,525 MT → Crisis-level shortage
Demand: Solder materials for semiconductors, AI, and data centers
Price Outlook: Strongly Bullish $52,000–55,394/MT, the strongest rally among base metals
Premium: Extremely high due to low stock and limited liquidity
 
Copper (Cu)
Stock: ~318,900–324,850 MT; rising cancelled warrants reflect strong physical demand
Demand: High-voltage power grids, EV charging stations, data centers
Price Outlook: Bullish Consolidating $13,100–13,500/MT; backwardation signals tight near-term supply
Premium: Freight premiums rising in Asia with infrastructure expansion
 
Aluminium (Al)
Stock: ~298,775 MT, mostly Russian origin restricted by EU, Japan, and South Korea sanctions
Demand: Lightweight EV and aerospace components, infrastructure projects
Price Outlook: Stable-to-Bullish $3,080–3,450/MT; supported by high alumina and energy costs
Premium: Asian MJP Premium surging → Q3 estimated at $400/MT (up from $353/MT in Q2/2026), a 12-year high
 
⚖️ Steady Metals
Zinc (Zn)
Stock: ~118,675–118,950 MT → Stable
Demand: Galvanizing steel; limited by China’s real estate slowdown
Price Outlook: Sideways-up $3,480–3,546/MT; short-term recovery from reduced smelter output outside China
Premium: Stable, largely dependent on Chinese demand
 
Nickel (Ni)
Stock: ~274,620 MT → Elevated due to Indonesia’s production surge
Demand: EV batteries, stainless steel
Price Outlook: Bearish $16,500–18,500/MT; oversupply keeps prices subdued
Premium: Low due to market saturation
 
Transport Premiums
Aluminium: MJP Premium ~ $400/MT → 12-year high
Copper: Freight premiums rising with infrastructure and data center demand
Tin: Highest premium among base metals due to extreme shortage
Nickel & Zinc: Relatively stable, regionally dependent
 
Future Price Outlook
Bullish: Tin & Copper → AI and clean energy demand driving new highs
Stable-to-Bullish: Aluminium → Supported by energy costs and Russian sanctions
Neutral: Zinc → Limited by China’s real estate slowdown, $3,450–3,550/MT
Bearish: Nickel → Oversupply from Indonesia continues to weigh on prices
 
Purchasing Strategies
Copper & Tin: Hedge forward contracts to mitigate price risk
Aluminium: Monitor Asian MJP Premium for strategic procurement
Zinc & Nickel: Buy hand-to-mouth to minimize volatility exposure
 
✨ Summary
The Base Metal Market 2026–2027 is entering a phase of clear divergence:

Tin & Copper → Rising stars, fueled by AI and clean energy demand
Aluminium → Recovering under geopolitical and energy cost pressures
Zinc & Nickel → Facing headwinds from weak demand and oversupply
 
SO OK TRADING — FAST • SHARP • RELIABLE Your trusted metals business partner in a time of change

www.sooktrading.com Facebook: SO OK TRADING

Related Content
Global Plastic Crisis! Naphtha Shortage Shakes Industries Worldwide — From Petrochemical Shock, War, Energy, and Environment to a Major Transformation of the Plastic Industry   : SO OK TRADING : 29 APR 2026
Global Plastic Crisis! Overlapping Shocks Shake the Industry At the beginning of 2026, the world faced a “Petrochemical Shock” that sent plastic raw material prices soaring by more than 37%. Conflicts in the Middle East and the closure of the Strait of Hormuz caused a severe shortage of naphtha—the lifeblood of the plastic industry—across the globe. Japan and South Korea were forced to cut production, while China accelerated its shift to alternative energy. Europe and the United States also struggled under surging costs. At the same time, the world is grappling with an environmental crisis from overflowing plastic waste. Recycling rates remain at only 10%, while the other 90% is landfilled, incinerated, or leaked into the environment. Alarmingly, microplastics have already entered the food chain and the human body. This is not just a “temporary crisis” but a structural turning point for the global plastic industry. Companies that adapt quickly—embracing Bio-based Plastics, Chemical Recycling, and the Circular Economy—will emerge as leaders in the new era now taking shape. SO OK TRADING is ready to be your trusted business partner. FAST • SHARP • RELIABLE
29 Apr 2026
“Copper Momentum 2026 – Strategic Metal Driving the Future | SO OK TRADING Insight: Copper in the AI Era Transforming Industries | Copper Price Outlook – August 24, 2026”
opper Price Situation Summary – August 24, 2026 : SO OK TRADING In an era where artificial intelligence (AI) and clean energy are driving the world forward, copper has emerged as a strategic metal playing a vital role in the global economic structure — from wiring systems in data centers to smart grids and electric vehicles (EVs) that are reshaping the energy industry. This article, prepared by SO OK TRADING, provides a comprehensive overview of both the global and Thai copper markets. It covers price trends, bullish and bearish factors, and strategic analysis for stakeholders in the metals and energy industries, based on the latest data from COMEX and LME as of August 24, 2026. The content includes:
24 Aug 2026
“Steel Price War 2026: Asia Falls, the West Rises — Thai Buyers Gain the Edge While Producers Battle with New Strategies, Exploring Global Trends and Green Steel Opportunities”
“Steel Price War 2026: Asia Falls, the West Rises — Thai Buyers Gain the Edge While Producers Struggle to Survive, Analyzing Global Trends and Green Steel Opportunities” The global steel market has entered one of the fiercest “two‑world battles” of the year: Asia: Oversupply and China’s slowdown have pushed iron ore prices down to around $101–102 per ton, dragging rebar, hot‑rolled coil, and wire rod prices lower across the region. The West: The US and EU imposed import tariffs of up to 50%, while energy and coking coal costs surged by 16%, driving steel prices upward despite weak demand. Thailand’s situation: Buyers benefit: Cheaper imports from China and Vietnam have pulled retail prices down by more than 8%. Producers under pressure: Electricity and shipping costs have soared by over 50%, squeezing margins and forcing reliance on state measures such as Anti‑Dumping and CBAM. Tin Plate packaging: Sales dropped by -1.2% to -4.5%, but raw material costs fell 9–10%. With a recycling rate of 92%, Tin Plate remains aligned with ESG and Green Steel trends.
5 Jun 2026
This website uses cookies for best user experience, to find out more you can go to our Privacy Policy and Cookies Policy
Powered By MakeWebEasy Logo MakeWebEasy