“Global Market Pulse 2026: Oil, Metals & Currencies in a Volatile Week Ahead of LME Week — In-depth Analysis by SO OK TRADING” October 18, 2026
Global Market Overview: Oil, Metals & Currencies (October 12–23, 2026)
SO OK TRADING | October 18, 2026
✨ Introduction In mid-October 2026, global markets are facing heightened volatility driven by several critical factors — geopolitical tensions in the Middle East, expectations surrounding U.S. Federal Reserve interest rate decisions, and the upcoming LME Week 2026, a pivotal annual event for global metals trading negotiations.
Movements in oil, metals, and currencies this week reflect alternating pressures and supports from both macroeconomic conditions and geopolitical risks. With markets in a state of “close watch,” investors must adopt cautious and strategic approaches to navigate the uncertainty across all directions.
Analysis & Outlook
️ Crude Oil
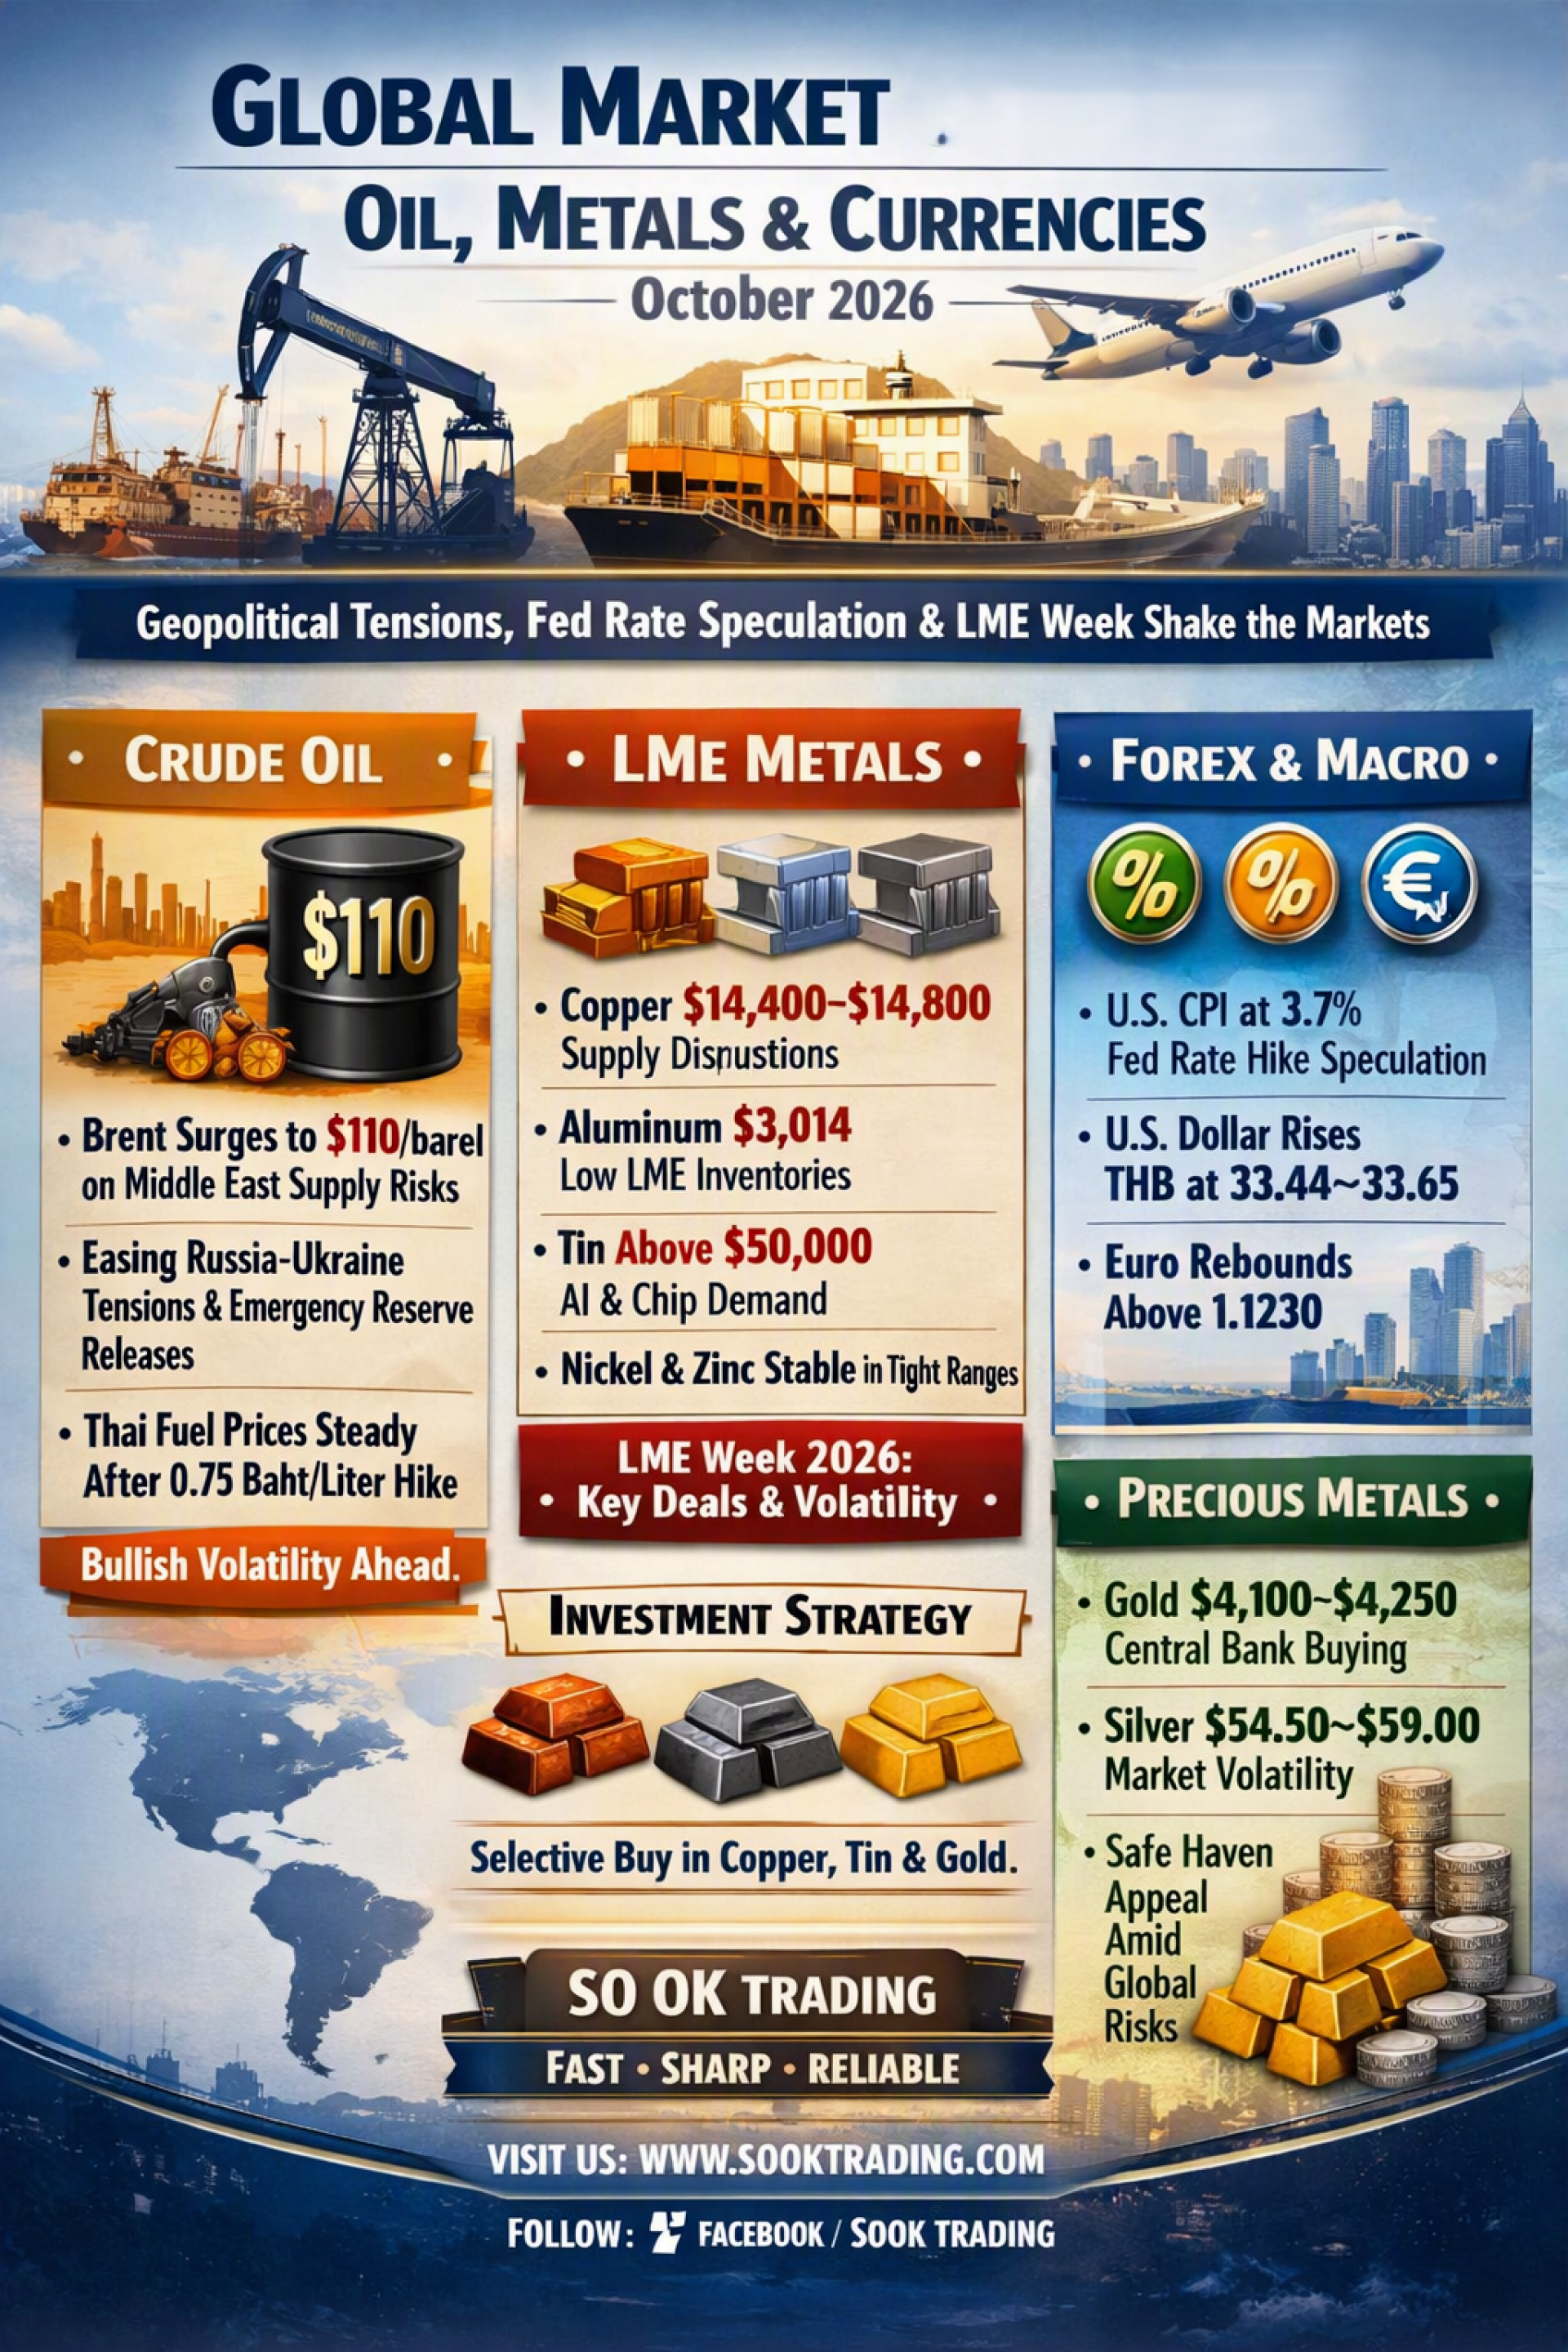
Current Situation: Brent crude surged to $110/barrel due to supply risks in the Middle East following attacks on energy infrastructure and tankers near the Strait of Hormuz and Saudi Arabia.
Pressure Factors: Reports of a ceasefire agreement between Russia and Ukraine, along with the release of over 20 million barrels of emergency reserves by the U.S. and IEA, temporarily pressured prices downward.
Thailand Situation: Domestic retail fuel prices stabilized after a 0.75 THB/liter increase. The government subsidized diesel by 2.25 THB/liter and gasohol by 1.09 THB/liter.
Outlook (Oct 19–23): Oil prices are expected to remain in bullish volatility, supported by Middle East instability, but capped by slowing demand expectations and Fed rate hike concerns.
⚙️ LME Metals
Overview: Mixed movements driven by a stronger U.S. dollar and individual supply-demand factors.
Copper: Strong upward trend, $14,400–$14,800/ton, supported by mine disruptions and historically low smelting fees.
Aluminium: Weakening, $2,980–$3,120/ton, despite LME inventories at century-low levels.
Tin: The strongest performer, holding above $50,000/ton, driven by AI and semiconductor demand, alongside supply recovery issues in Myanmar.
Nickel: At $15,170/ton, supported by Indonesia’s production quota restrictions.
Zinc & Lead: Zinc pressured by China’s property sector, while lead remains the most stable within a narrow range.
Forex & Macro
U.S. CPI: September inflation at 3.7%, above expectations, raising prospects of a 0.25% Fed rate hike to 4.00–4.25%.
U.S. Dollar (USD): Continued strength on rate hike expectations, but pressured by tech stock sell-offs and dovish Fed signals.
Dollar Index (DXY): Temporarily weakened, closing at 101.78.
Thai Baht (THB): Closed at 33.44–33.45/USD, supported by capital inflows and lower import oil costs. Expected to trade within 33.15–33.65 next week.
Euro (EUR/USD): Rebounded above 1.1230, though medium-term outlook remains fragile.