“Non‑Ferrous Metals Sell‑Off After CPI Surge — Copper & Aluminium Remain Tight as Fed Policy and Geopolitical Risks Shake Global Prices | SO OK TRADING Latest Analysis”; 15 OCT 2026
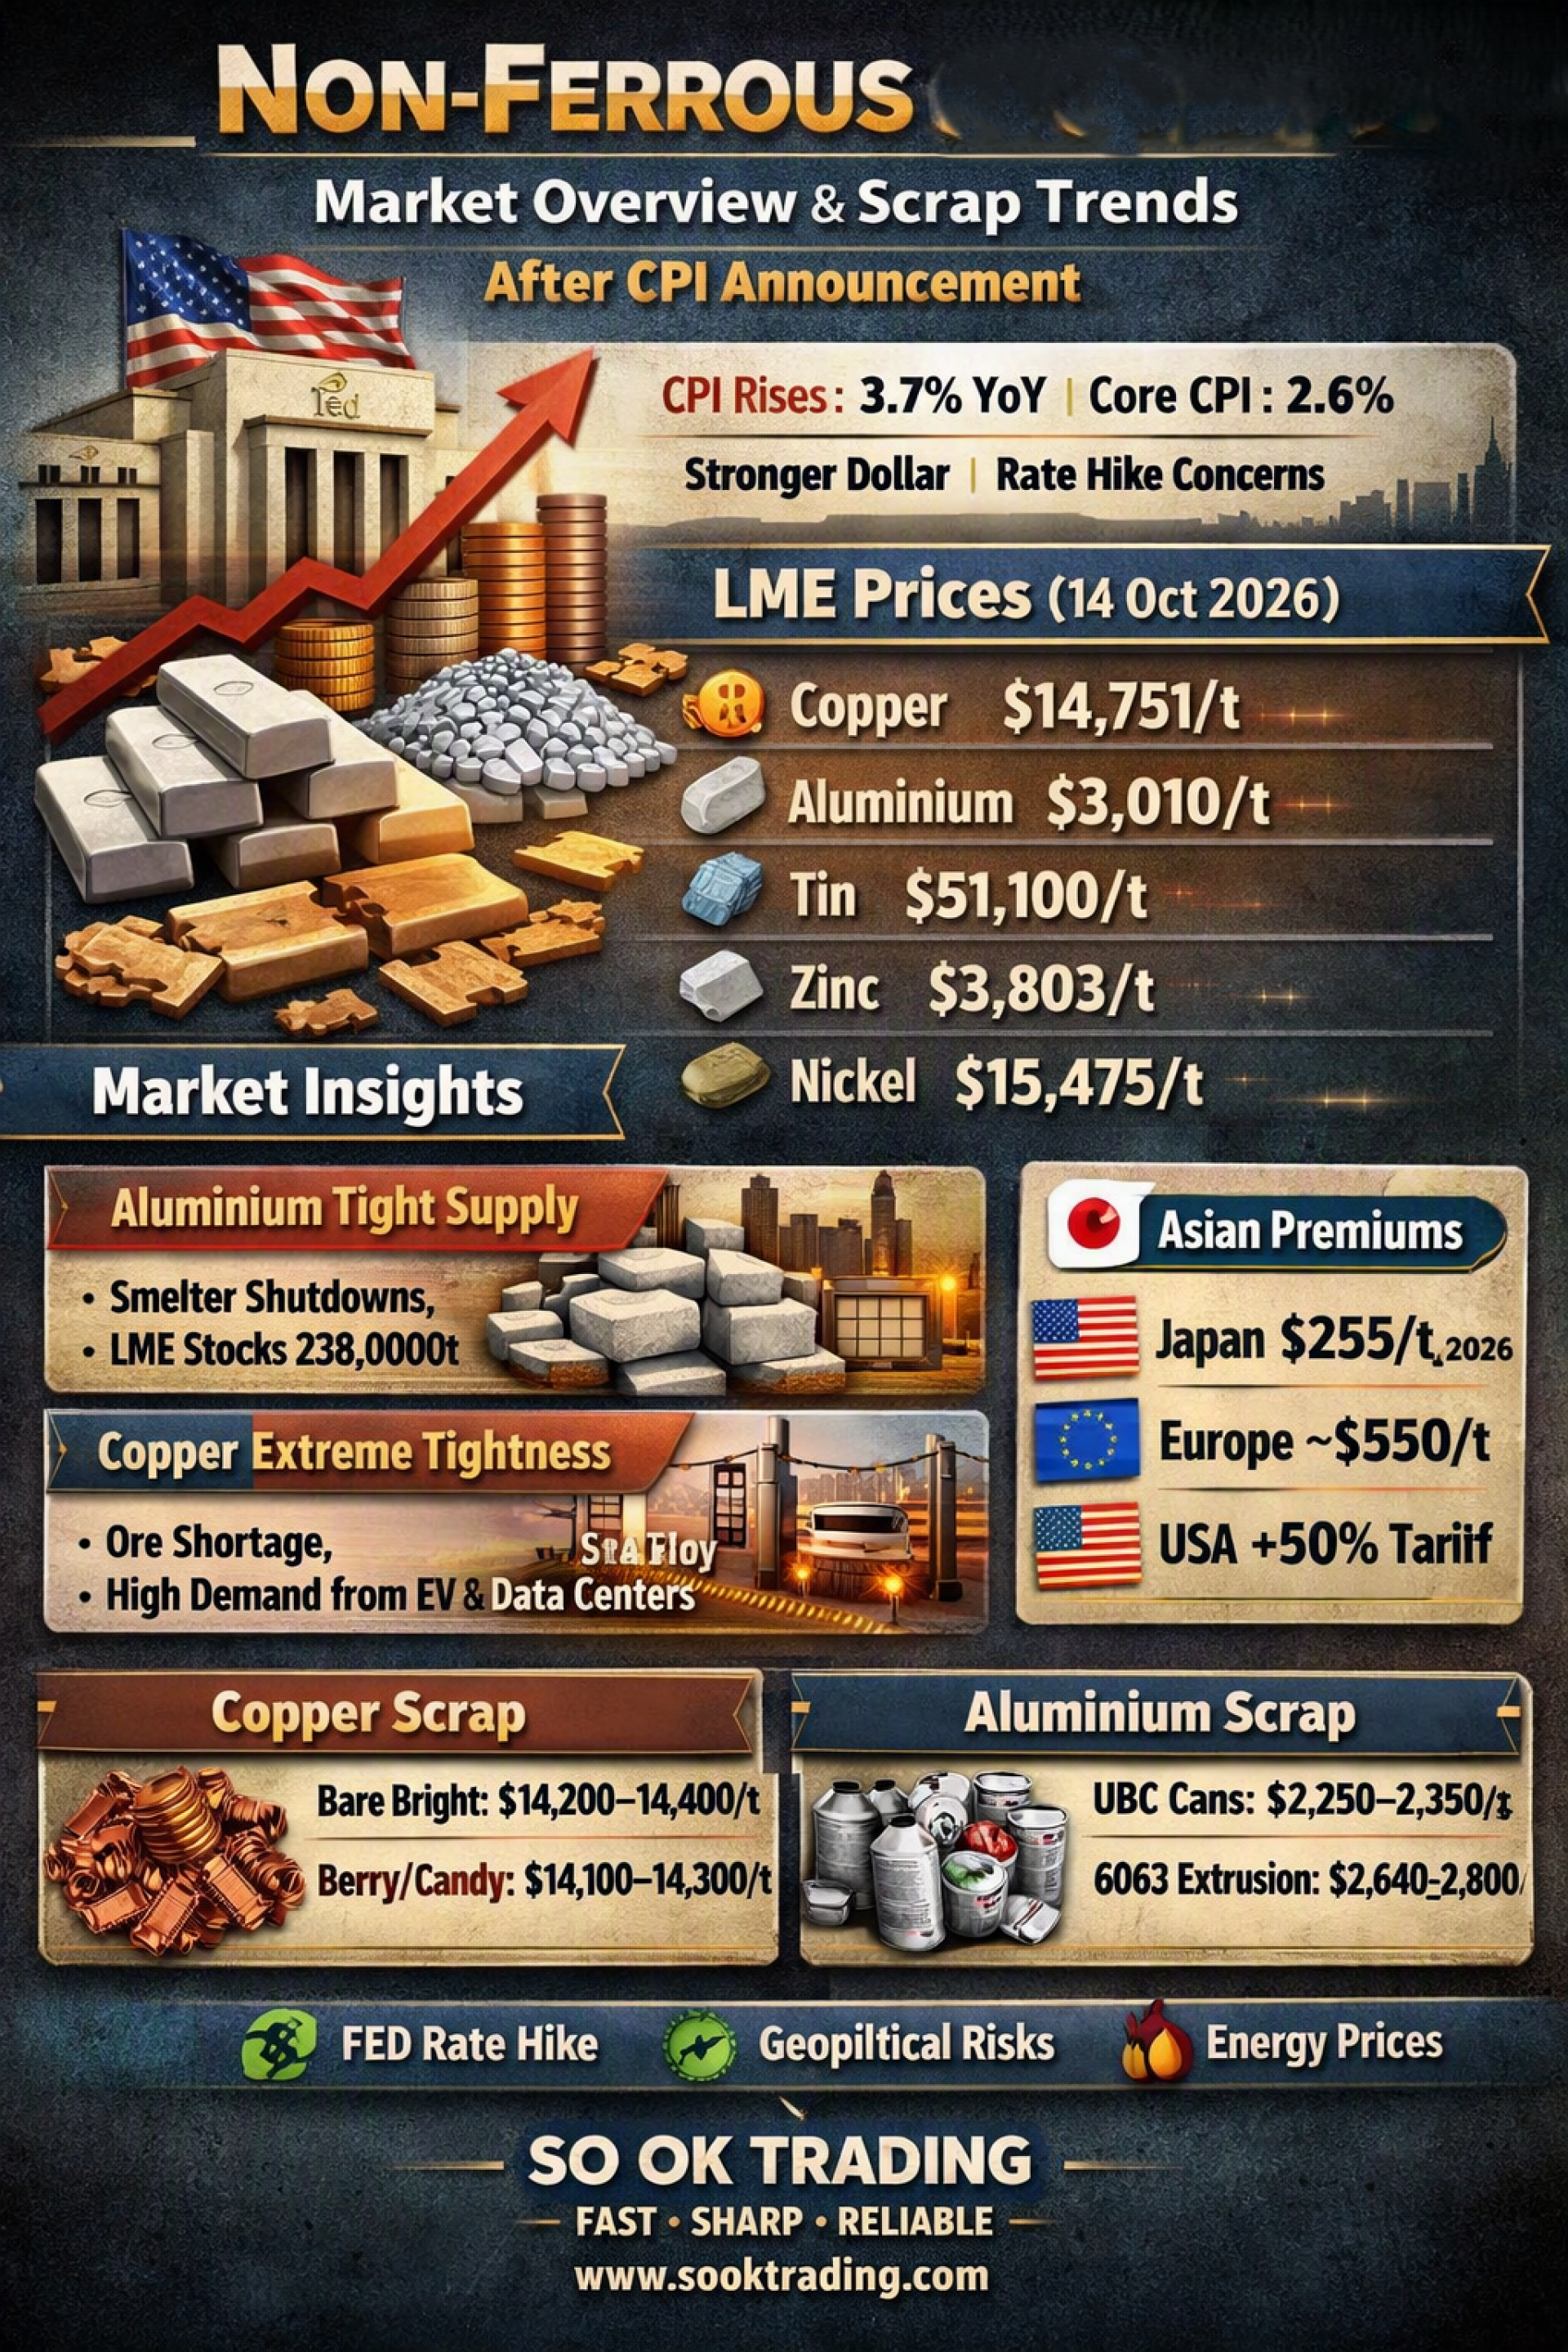
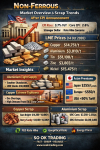
Non‑Ferrous Metals Market Overview & Scrap Trends in Asia
After CPI Announcement | SO OK TRADING | 15 OCT 2026
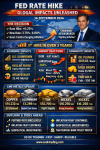
The global non‑ferrous metals market faced broad sell‑offs in mid‑October 2026 after the United States reported September CPI figures higher than expected. Headline CPI rose to 3.7% YoY and Core CPI to 2.6% YoY. This fueled concerns that the Federal Reserve may raise interest rates again or keep them elevated for longer. The stronger U.S. dollar immediately pressured risk assets, including industrial metals traded in USD.
LME Closing Prices (14 Oct 2026)
Copper: $14,751/t — Down on macro pressure, though Escondida mine (Chile) reached a labor agreement avoiding strike action
Aluminium: $3,010/t — Fell to year‑low, futures briefly broke below $3,000 amid oversupply in Europe
Tin: $51,100/t — Down 2.4–3%, but still above $50,000 on supply chain concerns and Middle East tensions
Zinc: $3,803/t — Slight decline (~0.4%) as treatment charges (TCs) hit record lows
Nickel: $15,475/t — Lowest since Dec 2025, supported by ample LME stocks
Market Insights
Aluminium: Futures weakened, but the physical market remains extremely tight. Smelter shutdowns in the Middle East cut nearly 3 million tons of annual capacity. LME stocks fell to ~238,625 tons, the lowest in the 21st century. Structural support remains strong in Europe and the U.S.
Copper: Short‑term sell‑offs followed dollar strength, but the market is in “Extreme Tightness.” TCs/RCs dropped to historic lows, reflecting severe concentrate shortages. Ore grades globally are declining 2–3% annually. EV and data center demand provide long‑term support.
Asian Premiums
Japan (MJP Q4 2026): ~$255/t — Down ~35% QoQ, but still above pre‑crisis (~200/t)
Europe (Rotterdam): ~$550–585/t — Higher premiums attract metal flows out of Asia
USA (Midwest): Elevated due to 50% tariff impact
♻️ Scrap Prices in Asia
Copper Scrap
Barley (Bare Bright): $14,200–14,400/t (−$250–450 vs LME)
Berry/Candy (No.1 Copper Wire): $14,100–14,300/t (−$350–550 vs LME) → Strong demand as smelters substitute scrap for scarce concentrate.
Aluminium Scrap
UBC (Used Beverage Cans): $2,250–2,350/t (down from >$2,400)
6063 Extrusion: $2,640–2,800/t (CIF Asia) → Prices track 70–85% of primary aluminium ($2,980/t). ASEAN import controls tighten supply flows.
⚠️ Key Watch Factors
Fed Policy: ~50% probability of rate hike at end‑October meeting
U.S. Data: Upcoming PPI and retail sales figures
Geopolitics: Middle East unrest and Hormuz Strait closure driving oil prices higher
✨ Summary
Despite macro headwinds from inflation and a stronger dollar, structural supply tightness continues to support copper and aluminium prices. Scrap markets in Asia adjust in line with primary metals: copper scrap remains firm due to concentrate shortages, while aluminium scrap faces more pressure from falling primary prices and stricter import inspections.
SO OK TRADING — FAST • SHARP • RELIABLE Your trusted partner in Non‑Ferrous Metals from Thailand www.sooktrading.com Facebook: SO OK TRADING