“Aluminum & Copper Market Outlook in the U.S.: Costs, Supply Chains, and the Drive of AI & Clean Energy” SO OK TRADING | October 4, 2026
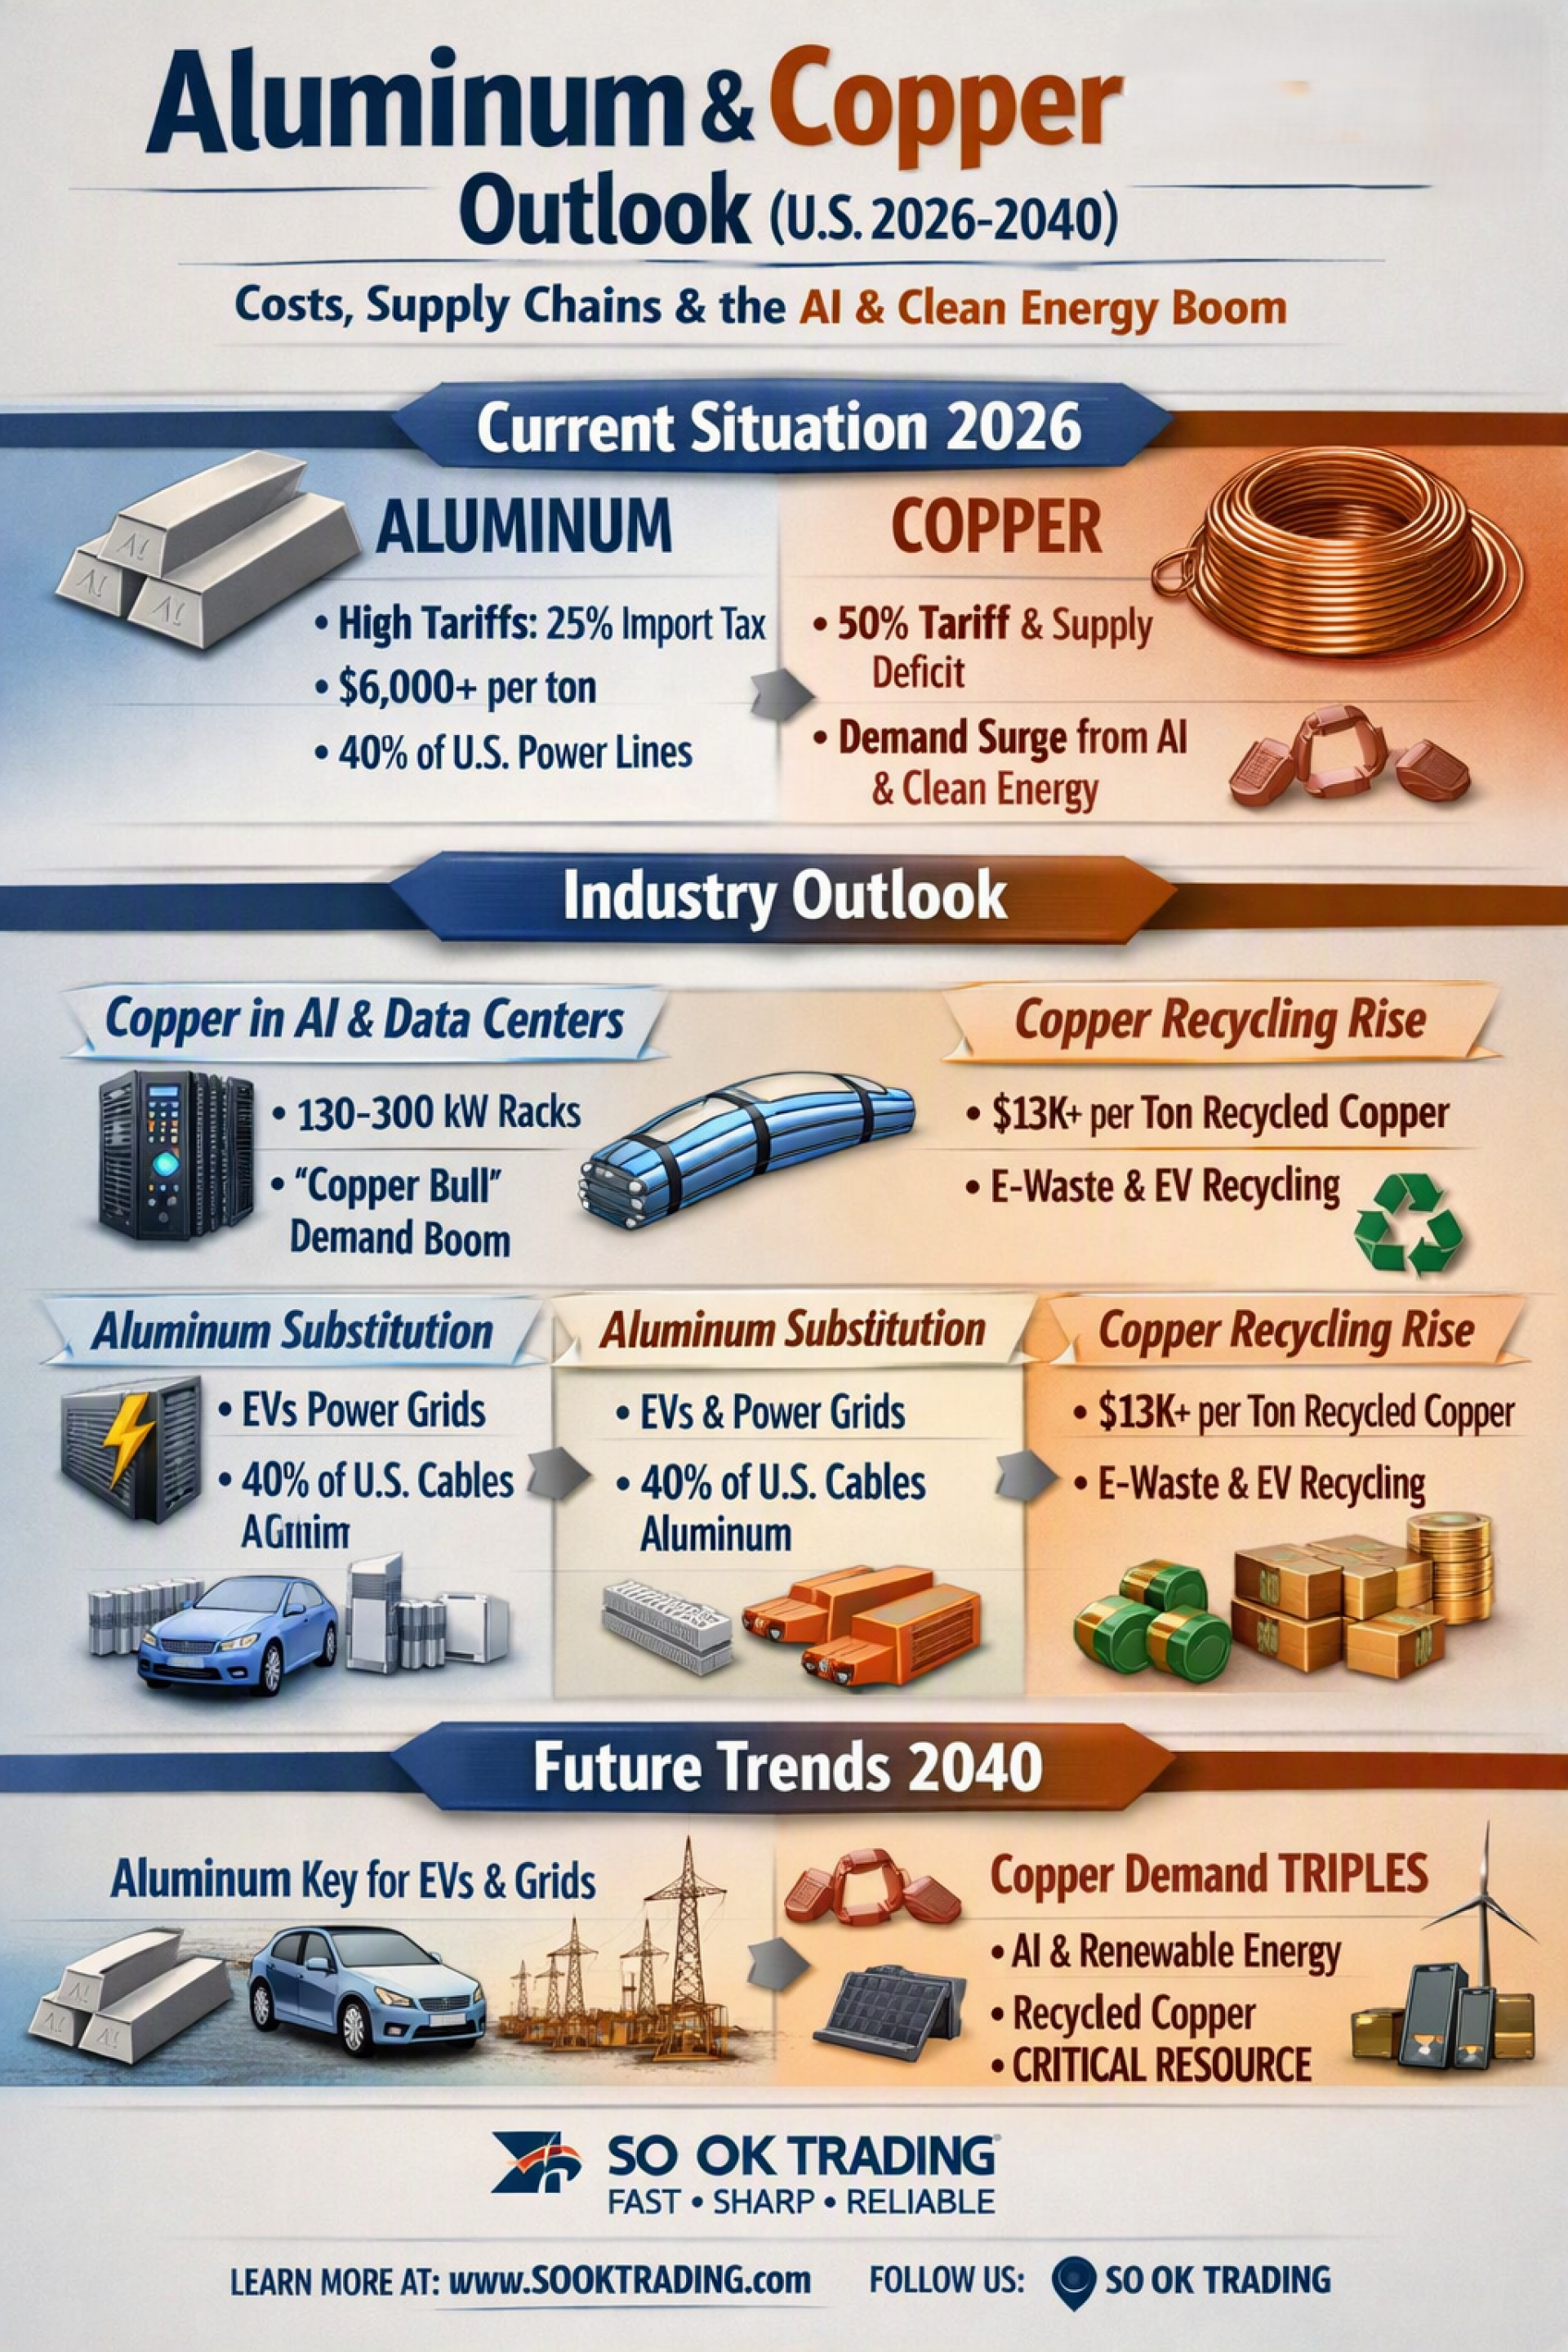
Aluminum & Copper Market Outlook in the U.S.: Costs, Supply Chains, and the Drive of AI & Clean Energy
SO OK TRADING | October 4, 2026
■ Introduction
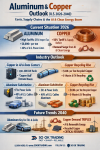
The United States is facing mounting pressure on costs and supply chains due to import tariffs and surging demand in the era of Artificial Intelligence (AI) and clean energy. Aluminum and copper have become strategic metals, playing a vital role in the future of the economy and industry. Yet, both face distinct challenges in terms of pricing, sourcing, and trade policy.
■ Current Situation
✦ Aluminum
Key Demand Drivers: EV body structures, beverage packaging, and large-scale transportation.
Price Situation: Prices have soared above $6,000 per ton due to supply chain crises and Middle East conflicts — nearly double the global market average.
Tariff Policy: A 25% import tariff has raised domestic production costs, pushing some manufacturers to switch to PET bottles.
Copper Substitution: Industries are increasingly using aluminum as a cost-effective alternative to copper.
✦ Copper
Key Demand Drivers: AI data centers, power grids, and EV motors.
Supply Situation: U.S. production is only about 1 million tons, while demand reaches 3.5 million tons → over 30% import dependency.
Tariff Policy: A 50% import tariff aims to boost domestic production but has sharply increased costs for wires and transformers.
Resource Competition: Fierce rivalry with China over access to major copper mines, such as in Peru.
Market Behavior: Businesses and traders are stockpiling copper to hedge against supply chain risks.
■ Industry Outlook
✦ Copper in AI & Data Centers
Rack power density has surged to 130–300 kW, requiring thicker, more durable copper cables.
Liquid cooling systems and high-speed data transmission rely heavily on copper.
S&P Global forecasts copper demand in this sector will triple by 2040.
This trend is often described as the “Copper Bull Narrative.”
✦ Aluminum Substitution
Aluminum conducts at 61% efficiency compared to copper but is three times lighter and about four times cheaper.
Over 40% of U.S. high-voltage transmission lines and cables now use aluminum.
AA-8000 alloys have solved past safety issues, enabling use in buildings and factories.
Automakers and HVAC manufacturers are adopting aluminum in EV wire harnesses and cooling coils.
✦ Copper Recycling Investments
Global copper prices have surged to $13,000–14,500 per ton, making recycling a strategic necessity.
Recycling consumes 85% less energy than new mining and significantly reduces greenhouse gas emissions.
Target Industries:
E-waste recycling from data centers and AI hardware.
EV battery and motor recycling.
Grid modernization under the Inflation Reduction Act (IRA).
New Technologies: Advanced hydrometallurgy, AI-driven sorting, and joint ventures between automakers/tech firms and recyclers.
■ Future Trends
Aluminum: Will remain a key substitute for copper, especially in EVs and power grids.
Copper: Demand will continue to surge due to AI and clean energy, but supply constraints will persist.
Recycling: Both aluminum and copper recycling will become pillars of U.S. technological and energy security.
■ Conclusion
The U.S. aluminum and copper markets reflect a critical turning point in the global economy. These metals are not just raw materials — they are the foundation of AI, EVs, and clean energy infrastructure.
Aluminum: Despite high prices, it remains a lightweight, cost-effective solution.
Copper: Despite shortages, it is indispensable for modern infrastructure.
Recycling: A strategic path to reduce risks and secure sustainable resources.
SO OK TRADING: Your Trusted Business Partner FAST • SHARP • RELIABLE Visit: www.SOOKTRADING.com Facebook: SO OK TRADING