Share

“Global Oil Prices Break $100: Geopolitical Crisis and Chain Reactions Across Petrochemical Industry and World Economy” SO OK TRADING | September 10, 2026
Last updated: 10 Sept 2026
1784 Views

 Global Oil Market Situation and Impacts on Related Industries (September 10, 2026)
SO OK TRADING | FAST • SHARP • RELIABLE

 
Introduction
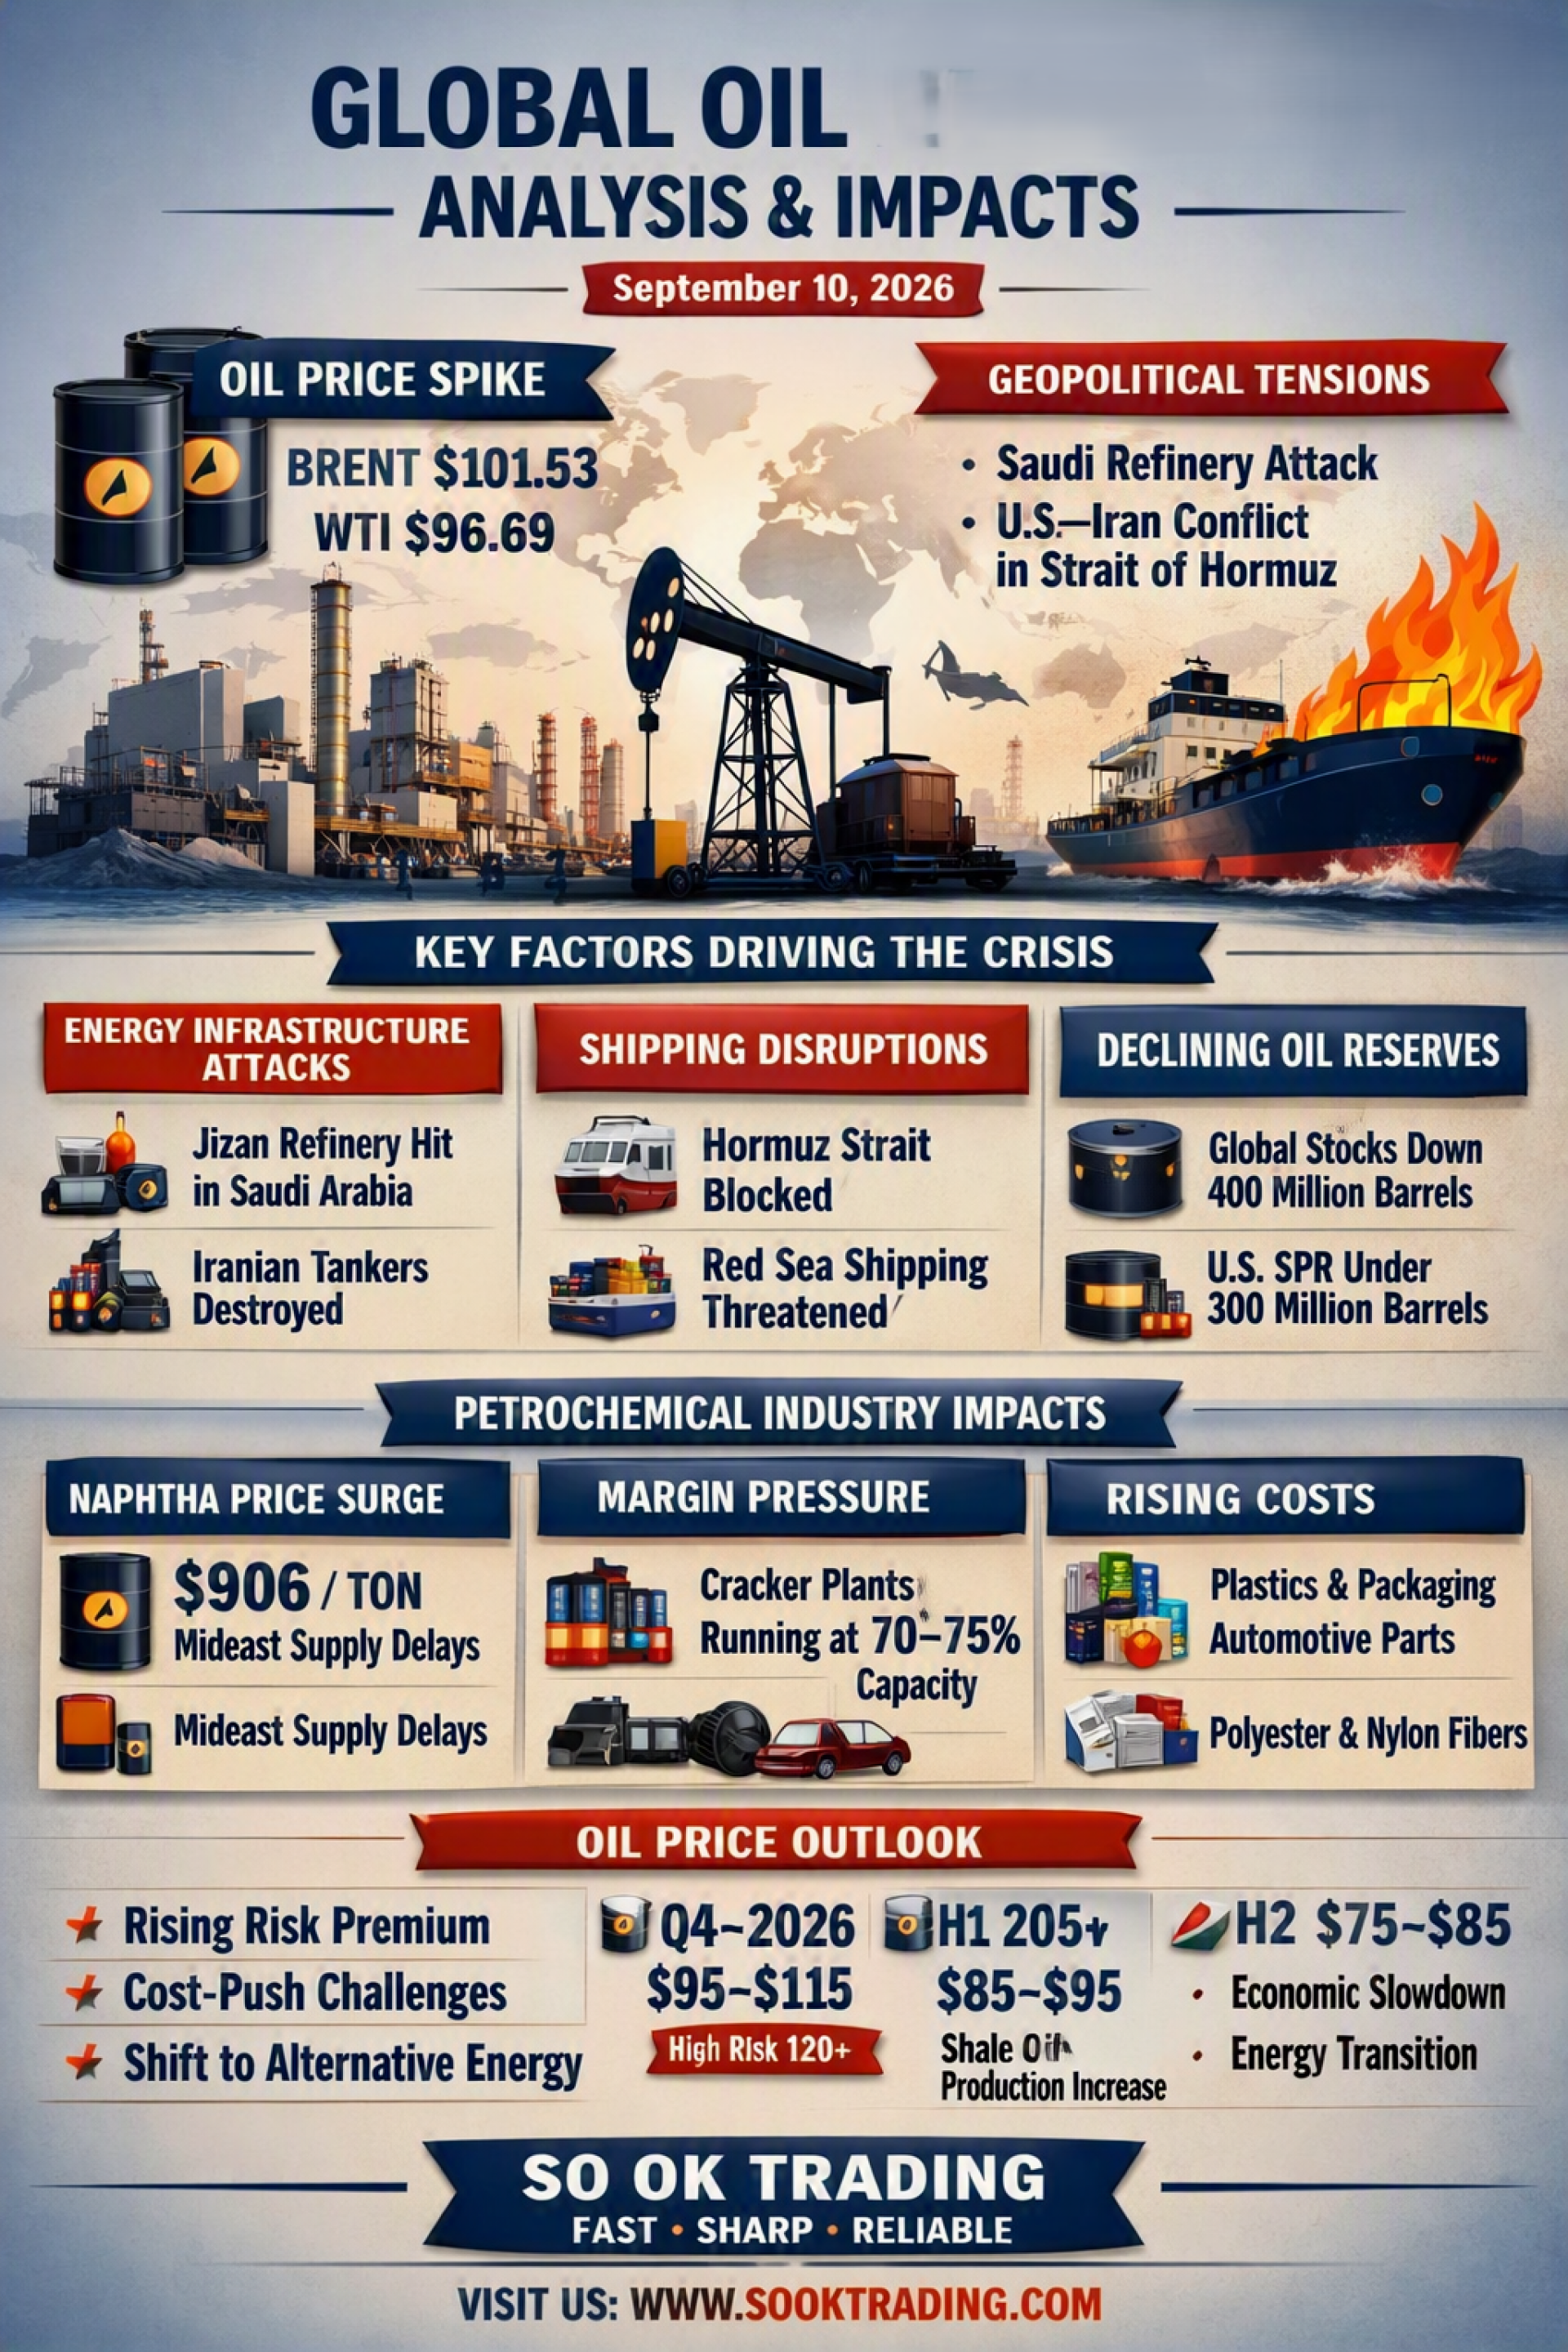
The global oil market is facing one of its most turbulent periods in recent years. Brent crude has surged past the psychological threshold of $100 per barrel, while WTI jumped more than 4% in a single day. The main driver is escalating geopolitical tension in the Middle East: the Jizan refinery of Saudi Aramco was attacked by Houthi forces, and clashes between the U.S. and Iran in the Strait of Hormuz — a route that carries over 20% of the world’s oil — have further disrupted supply chains. This situation not only pressures oil prices upward but also shakes the global energy supply chain and downstream industries.

 
Key Drivers of Oil Prices
Energy Infrastructure Attacks

Jizan refinery (400,000 barrels/day) hit and set ablaze
U.S. destroyed five Iranian oil tankers
Transport Bottlenecks

Strait of Hormuz nearly paralyzed
Red Sea shipping routes attacked, delaying oil and naphtha exports
Shrinking Global Oil Stocks

Global inventories down by 400 million barrels since the start of the year
U.S. SPR below 300 million barrels, limiting intervention capacity
 
⚠️ Impacts on Petrochemical Industry and Related Products
Naphtha: Prices surged to $906/ton, with Middle East supply delays forcing Asian and European plants to compete for feedstock
Spread Compression: Costs rising faster than product prices; cracker plants cut operating rates to 70–75% to avoid losses
Ripple Effects on Products:

Plastic packaging: prices up 15–20% in Q4 2026
Automotive & synthetic rubber: higher costs for parts and materials
Textiles: polyester and nylon prices rising due to PX shortages
 
Outlook and Future Trends
Crude Oil

Q4 2026: $95–115 range, risk of $120–130 if tensions worsen
H1 2027: correction to $85–95 with shale oil expansion and SPR measures
H2 2027: stabilization at $75–85 as global economy slows and energy transition accelerates
Petrochemicals & Related Industries

Olefins (Ethylene/Propylene): prices remain high, spreads below $250–300/ton, continued losses for Asian & European crackers
Plastics & Packaging (PE, PP, PET): prices up 15–20% in Q4 2026, but demand temporarily weak
Synthetic Fibers (Polyester/Nylon): sustained price increases from costly naphtha and PX shortages
Automotive & Textiles: rising costs, shrinking margins, urgent need for production restructuring
 
Conclusion
The current oil price surge reflects a heightened Risk Premium driven by geopolitical uncertainty and declining inventories. The petrochemical industry is clearly entering a Cost-Push Supercycle, forcing producers to rethink strategies in production and raw material sourcing.

In the short term, businesses must cope with high costs and compressed spreads. In the medium to long term, oil price corrections and the accelerating shift toward alternative energy will define the new trajectory of global markets and downstream industries.

 
SO OK TRADING — Your Trusted Business Partner VISIT US: www.sooktrading.com FACEBOOK: SO OK TRADING

Related Content
“Aluminum Recycling (Remelt): Thailand Aluminum 4.0 – Powering a Low‑Carbon Economy and Building a Sustainable Green Future”   SO OK TRADING Insight | 30 SEP 2026
Thailand’s Aluminum Industry: Structure, Production, and Future Outlook SO OK TRADING | 30 SEP 2026 Thailand’s aluminum industry is emerging as a vital pillar in the global supply chain, particularly in the automotive, construction, and packaging sectors. Although the country does not possess bauxite mines or primary smelters, it has built strong competitiveness through secondary production, recycling aluminum scrap, and producing billets for extrusion. This approach reduces energy consumption by up to 95% compared to primary production, aligning perfectly with global decarbonization and sustainability goals. As the world accelerates toward a Low‑Carbon Economy and stricter environmental measures such as the EU CBAM (Carbon Border Adjustment Mechanism) take effect, Thailand’s aluminum industry must adapt rapidly. This includes advancing production technologies, improving waste management, and integrating renewable energy to maintain competitiveness in international markets. SO OK TRADING, as a trusted partner in Thailand’s non‑ferrous metals sector, provides deep insights into production structures, smelting processes, popular aluminum grades, and both global and domestic market outlooks. These perspectives highlight the industry’s transformation toward a sustainable, value‑added future.
30 Sept 2026
“Thailand Agriculture’s Dual Battle 2026: Durian’s Golden Year VS Rice’s Challenging Era — From Farms to the World, A New Path Forward”   SO OK TRADING | 4 JUNE 2026
Thailand Agriculture Market 2026 – Rising Stars VS Global Challenges By SO OK TRADING | 4 June 2026 2026 marks a year of “dual realities” for Thai agriculture. On one side, production is gradually recovering thanks to favorable weather
4 Jun 2026
“Nickel Outlook 2026–2036: The Global Nickel Market Revolution — A Turning Point Toward the Golden Era of Clean Energy Metals”   SO OK TRADING’s Insight: October 2, 2026
Global Nickel Market Outlook (Nickel Outlook) October 2026 – 2036 SO OK TRADING | FAST | SHARP | RELIABLE | October 2, 2026 ✨ Introduction The year 2026 marks a pivotal turning point for the global nickel market — a strategic metal driving the clean energy economy and future technologies. Nickel is not only a key raw material in the stainless steel industry but also the backbone of electric vehicle (EV) batteries and advanced energy storage systems. In October, the nickel market is shifting from a state of oversupply to a more balanced and tightening market, reflecting a restructuring of the global supply chain. At the center of this transformation is Indonesia, the dominant producer shaping global price direction. ⚙️ Industry Overview Supply: Indonesia has cut mining quotas by over 30%, reducing output to 250–270 million tons in 2026 → tightening supply and raising costs. Demand: Recovery across regions: Europe +1.8% United States +0.9% Africa +26.3% Geopolitics: With North and South America’s share of production down to just 7%, the U.S. and its allies are accelerating long-term agreements to secure supply chains.
2 Oct 2026
This website uses cookies for best user experience, to find out more you can go to our Privacy Policy and Cookies Policy
Powered By MakeWebEasy Logo MakeWebEasy