“Aluminium Transforms the EV World: Lightweight Power, Strategic Future” SO OK TRADING|14 AUG 2026
Aluminium for the Global Automotive Industry
Article by SO OK TRADING | 14 August 2026
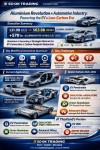
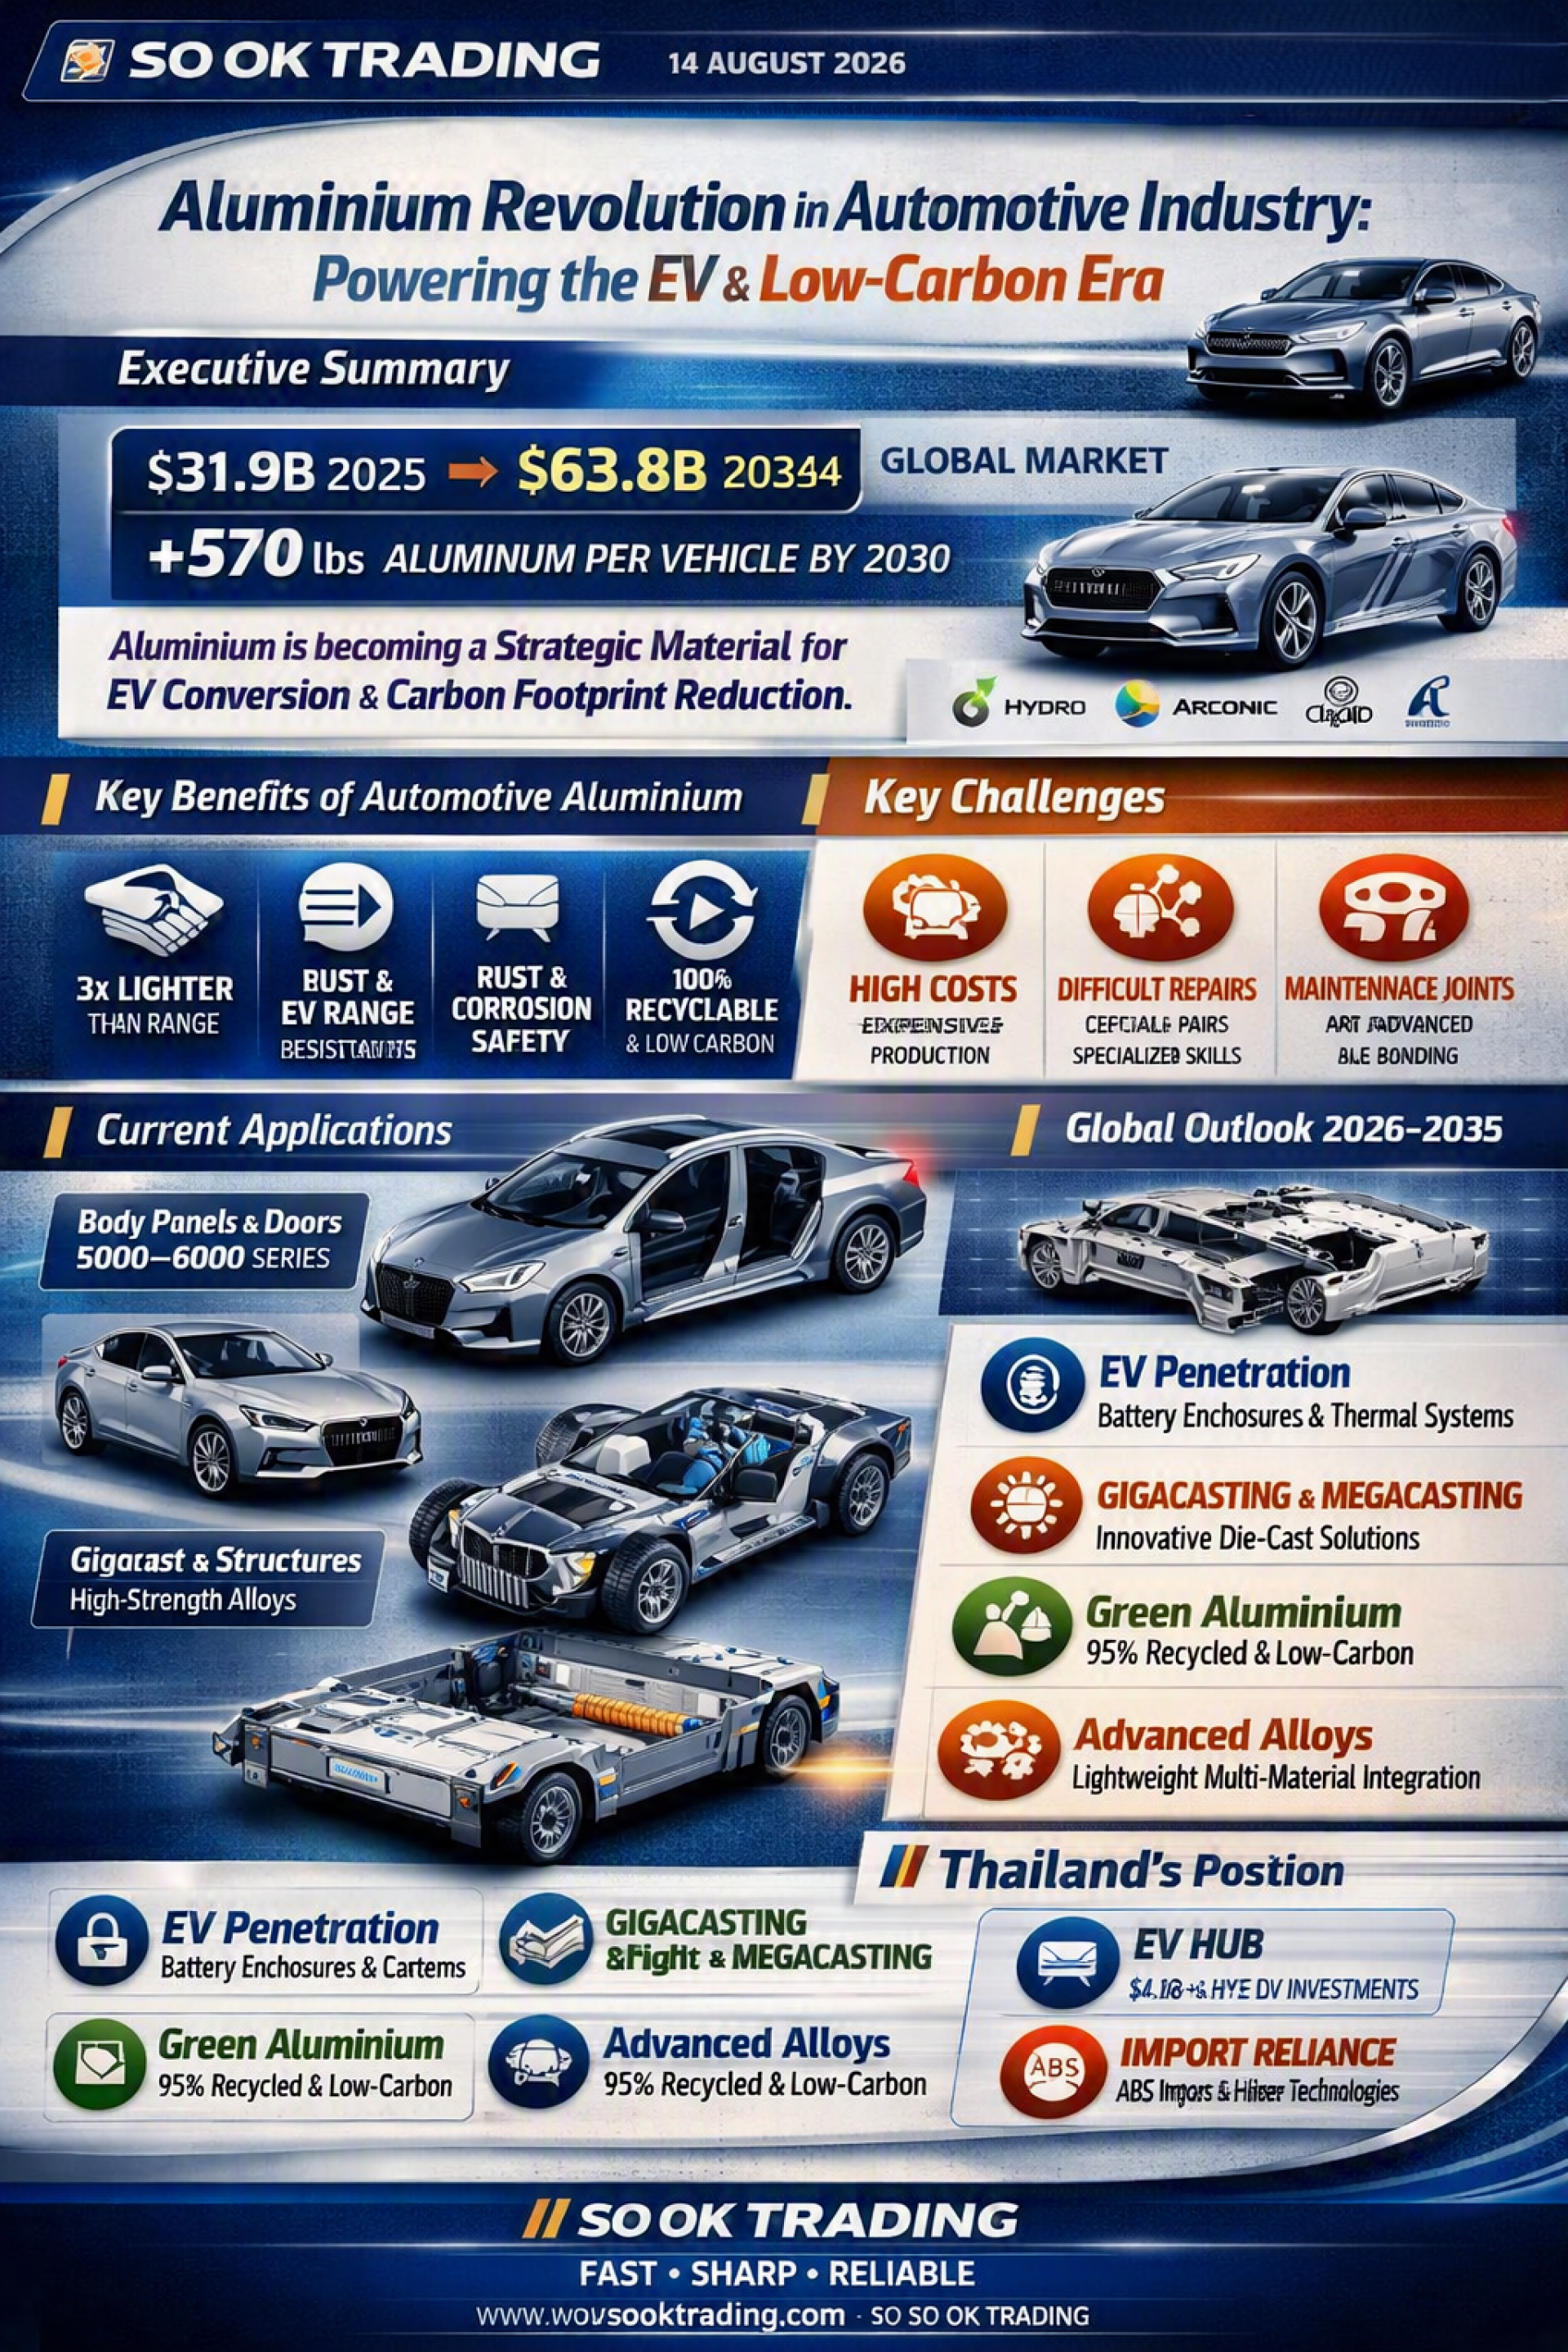
Aluminium Revolution in Automotive Industry: Driving EV & Clean Energy Future
Executive Summary
Aluminium is rapidly becoming a strategic material in the global automotive industry—not only because of its lightweight properties, but also because it directly supports the transition to electric vehicles (EVs) and the reduction of carbon footprints under increasingly strict global regulations.
Global Market: Projected growth from USD 31.9 billion in 2025 → USD 45.1 billion in 2031, surpassing USD 63.8 billion in 2034, with a CAGR of ~6%.
Per Vehicle Usage (PPV): Expected to exceed 570 lbs per vehicle by 2030 (+24% compared to the previous decade).
Key Players: Novelis, Constellium, Hydro, Arconic, Chalco, and Alcoa competing in low-carbon aluminium and Gigacasting technologies.
Thailand: Despite lacking upstream smelting, the country has strong potential in processing and component manufacturing, especially within the Eastern Economic Corridor (EEC) and companies such as Thai Summit Group.
Purpose of Aluminium in Automotive
The use of aluminium in car bodies aims to reduce weight, improve energy efficiency, and extend driving range—particularly crucial for EVs, which must offset the heavy weight of batteries.
✅ Key Advantages
Lightweight: Nearly three times lighter than steel
Energy Efficient: Improves fuel economy and extends EV range
Corrosion Resistant: Naturally protected by oxide layer
Safety: Excellent crash absorption properties
100% Recyclable: Low energy consumption in recycling
⚠️ Key Challenges
High Costs: More expensive than steel in both material and processing
Repair Difficulty: Requires specialized technicians
Maintenance Costs: Often necessitates part replacement
Complex Joining: Advanced bonding techniques such as adhesives or laser welding required
Current Applications
Body Panels & Doors: 5000–6000 series alloys (e.g., 5182, 6014)
Chassis Structures: High-strength aluminium alloys
Gigacasting: Large single-piece casting technology pioneered by Tesla
Global Producers
Novelis – Major supplier to Ford, BMW, Jaguar Land Rover
Arconic – Specializes in high-strength aluminium
Constellium – Leading in battery enclosures
Hydro (Norsk Hydro) – Focused on low-carbon aluminium
Chalco (China) – Produces ABS grades 6014, 6016
Thailand Context
No upstream aluminium smelting, but strong in downstream processing and stamping
EEC hosts rolling mills and distributors importing engineering grades (5083, 6061)
Global Outlook (2026–2035)
EV Penetration: Aluminium as the standard for battery enclosures and thermal management systems
Gigacasting & Megacasting: Reducing part counts and long-term production costs
Green Aluminium & Circular Economy: Recycling reduces production energy by up to 95%, aligning with CBAM and global environmental tariffs
Advanced Alloys & Multi-Material Integration: New alloys combining lightweight design with high crash resistance
Key Market Drivers
EV Conversion: Rising aluminium demand alongside EV growth
Carbon Regulations: Environmental tariffs pushing adoption of green aluminium
Supply Chain Consolidation: Upstream mergers, e.g., Alcoa acquiring bauxite/alumina assets
Asia-Pacific Dominance: China remains the leader in production and consumption
Thailand Supply Chain Impact
Opportunities: Thailand as the “Detroit of Asia,” attracting EV investments exceeding USD 4.1 billion
Challenges:
Heavy reliance on ABS imports
Production costs ~30% higher than China
Chinese supply chains establishing local bases, intensifying competition
Solution: Integration into hybrid and EV supply chains through technology investment and recycling
Conclusion
Aluminium is no longer just a substitute for steel—it is a strategic material shaping the future of EVs and clean energy. Investment in green aluminium, gigacasting, and advanced alloys will define competitiveness in the coming decade. Thailand must adapt quickly to secure its place in the global supply chain.
SO OK TRADING: Your Trusted Business Partner FAST • SHARP • RELIABLE VISIT US: www.sooktrading.com FACEBOOK: SO OK TRADING SO OK TRADING: The Leader in Non-Ferrous Business