Global Plastic Crisis! Naphtha Shortage Shakes Industries Worldwide — From Petrochemical Shock, War, Energy, and Environment to a Major Transformation of the Plastic Industry : SO OK TRADING : 29 APR 2026
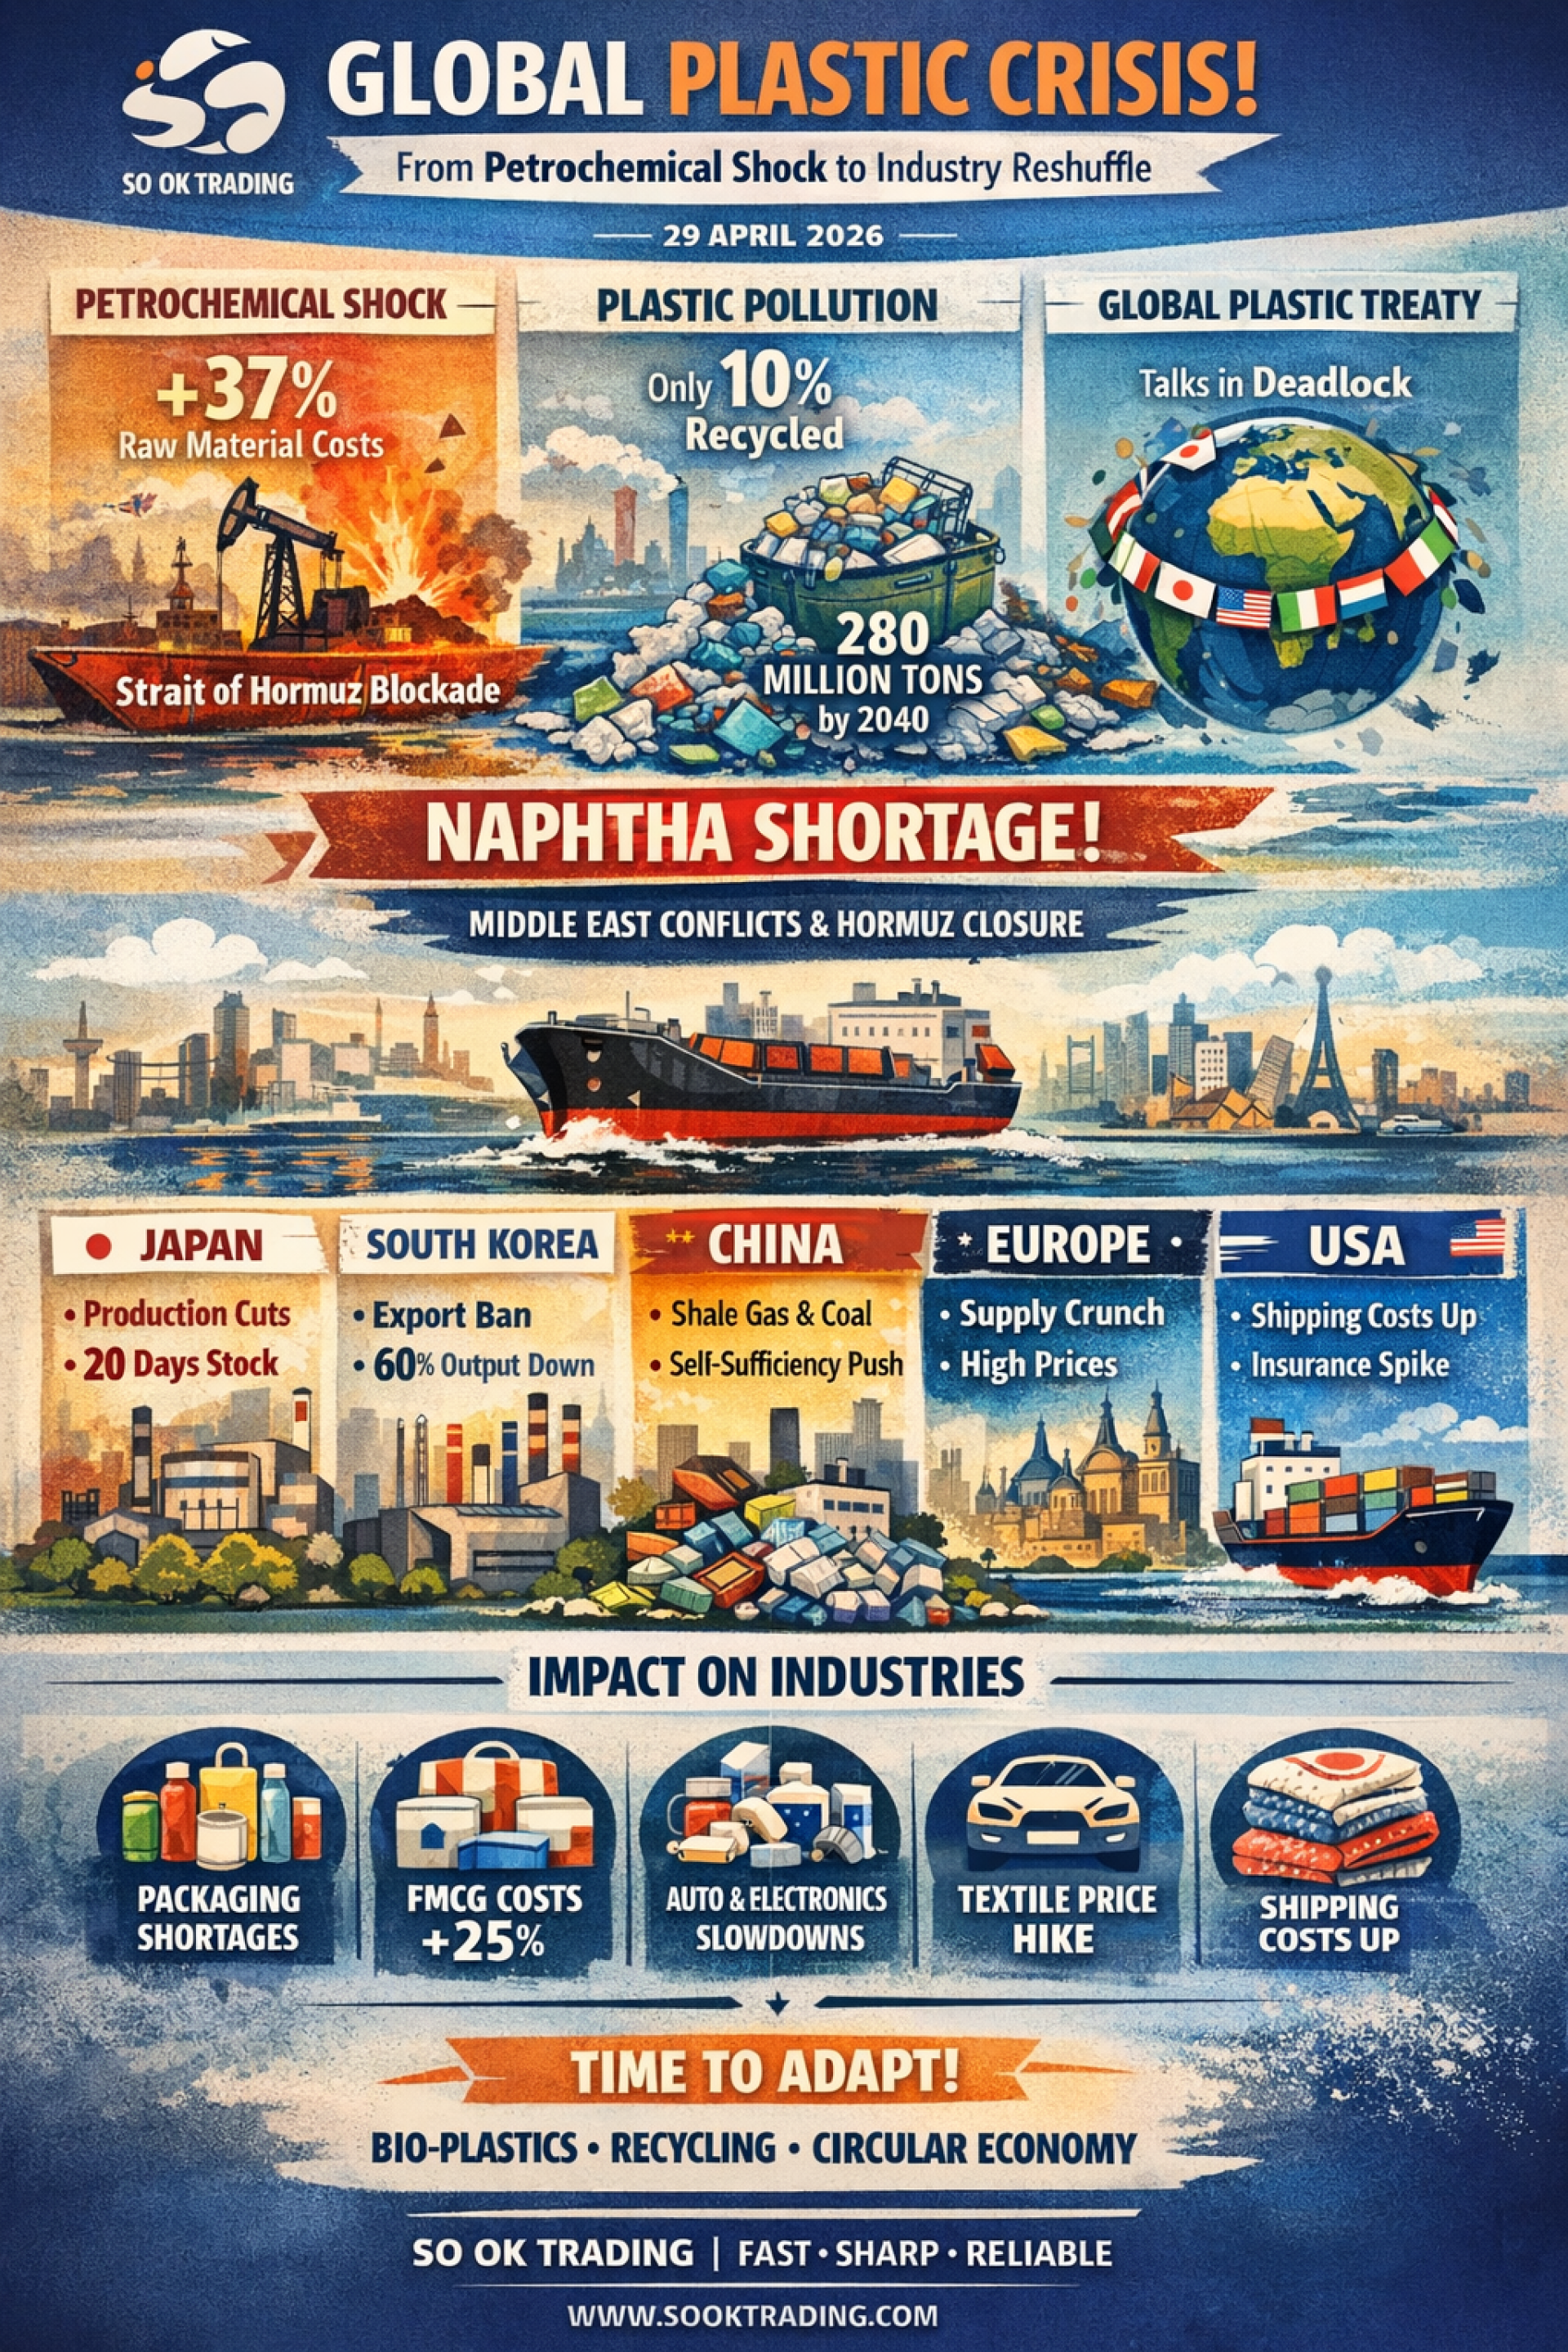
Global Plastic Crisis! Overlapping Shocks Shake the Industry – From Petrochemical Shock to a Major Structural Transformation Economic Crisis: “Petrochemical Shock” : SO OK TRADING : 29 APRIL 2026
Petrochemical Shock: Economic Crisis
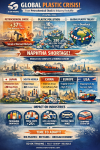
At the beginning of 2026, the world faced what is now called the “Petrochemical Shock.” Plastic raw material prices surged by more than 37%. The main cause was conflict in the Middle East and the closure of the Strait of Hormuz, which led to a severe shortage of naphtha (Naphtha)—the essential feedstock for plastics. This impact rippled across industries, from food and beverage packaging to automotive and electronics.
Environmental Crisis: Overflowing Plastic Waste
At the same time, the world is grappling with an environmental crisis. Despite ongoing campaigns, plastic waste management remains insufficient. Currently, only 10% of plastics are successfully recycled, while more than 90% are landfilled, incinerated, or leaked into the environment. Without improvement, global plastic pollution could reach 280 million tons per year by 2040. Alarmingly, microplastics have already entered the food chain and the human body.
Global Policy: Plastic Treaty → Circular Economy
The United Nations Environment Programme (UNEP) is negotiating a Global Plastic Treaty to end plastic pollution from upstream to downstream. However, talks remain deadlocked: EU countries demand strict measures, while oil-producing nations oppose production limits.
Naphtha Shortage: Prices Hit Multi-Year Highs
The closure of the Strait of Hormuz disrupted more than 1.2 million barrels per day of naphtha supply. Japan and South Korea, which rely on Middle Eastern imports for 60–77% of their needs, were forced to cut production, with some plants declaring Force Majeure. In April 2026, global naphtha prices rose more than 70% year-on-year, with premiums hitting their highest level in two years. The crisis remains unresolved, with high uncertainty due to Middle East conflicts and the ongoing blockade by both Iran and the United States.
Country Impacts
Japan Relies on Middle Eastern imports for 74%. Half of its ethylene plants have reduced output, with stockpiles lasting only about 20 days if the Strait remains closed. The government is seeking supply from the U.S. and Southeast Asia, emphasizing a four-month reserve, and planning structural reforms in Chiba and Kawasaki to reduce dependence.
South Korea The government banned naphtha exports to secure domestic stability. LG Chem and Yeochun NCC cut production to 60–66% and warned of possible Force Majeure. Strategic reserves are being used, while companies seek imports from Russia and the UAE.
China Though facing higher import costs, China managed better than Japan and Korea by stockpiling naphtha and using alternatives such as shale gas and coal. Inefficient cracker plants are being shut down, with a shift toward high-value specialty chemicals. The government is also strengthening domestic supply chains.
Europe Europe is the hardest hit, with plastic prices at the world’s highest levels. Imports from Russia have been cut, and Middle Eastern supply halted. Many plants have suspended operations, severely impacting packaging and automotive industries. Recycling investments are underway but remain insufficient.
United States The U.S. benefits slightly from cheap ethane feedstock, but transport costs have surged more than 30%, and shipping insurance premiums jumped from 0.05% to 7.5%. Overall costs remain high due to global market volatility.
Industry Impacts
Food & Beverage Packaging: PET bottles and plastic bags are in short supply, hitting small producers hardest.
FMCG: Packaging costs rose from 10–15% to 25% of product prices.
Automotive & Electronics: Engineering plastics are scarce, slowing production lines.
Textiles & Apparel: PX and PTA shortages drove polyester prices higher.
✅ Conclusion: The Naphtha Crisis
The global plastic crisis of 2026 is a double shock—economic and environmental. Japan and South Korea remain in deep crisis, relying on emergency measures and restructuring. China has eased pressure through alternative energy and self-sufficiency. Europe suffers the most from soaring prices and production halts, while the U.S., despite structural advantages, cannot escape rising transport costs.
This is not just a temporary shortage—it is a structural turning point for the global plastic industry. Companies that adapt quickly—embracing Bio-based Plastics, Chemical Recycling, and the Circular Economy—will lead the new markets emerging from this transformation.
SO OK TRADING: Your Trusted Business Partner FAST • SHARP • RELIABLE www.sooktrading.com Facebook: SO OK TRADING