Global Plastic Crisis 2026: Rising Costs as War and Naphtha Shake the Industry
Last updated: 5 Apr 2026
8774 Views
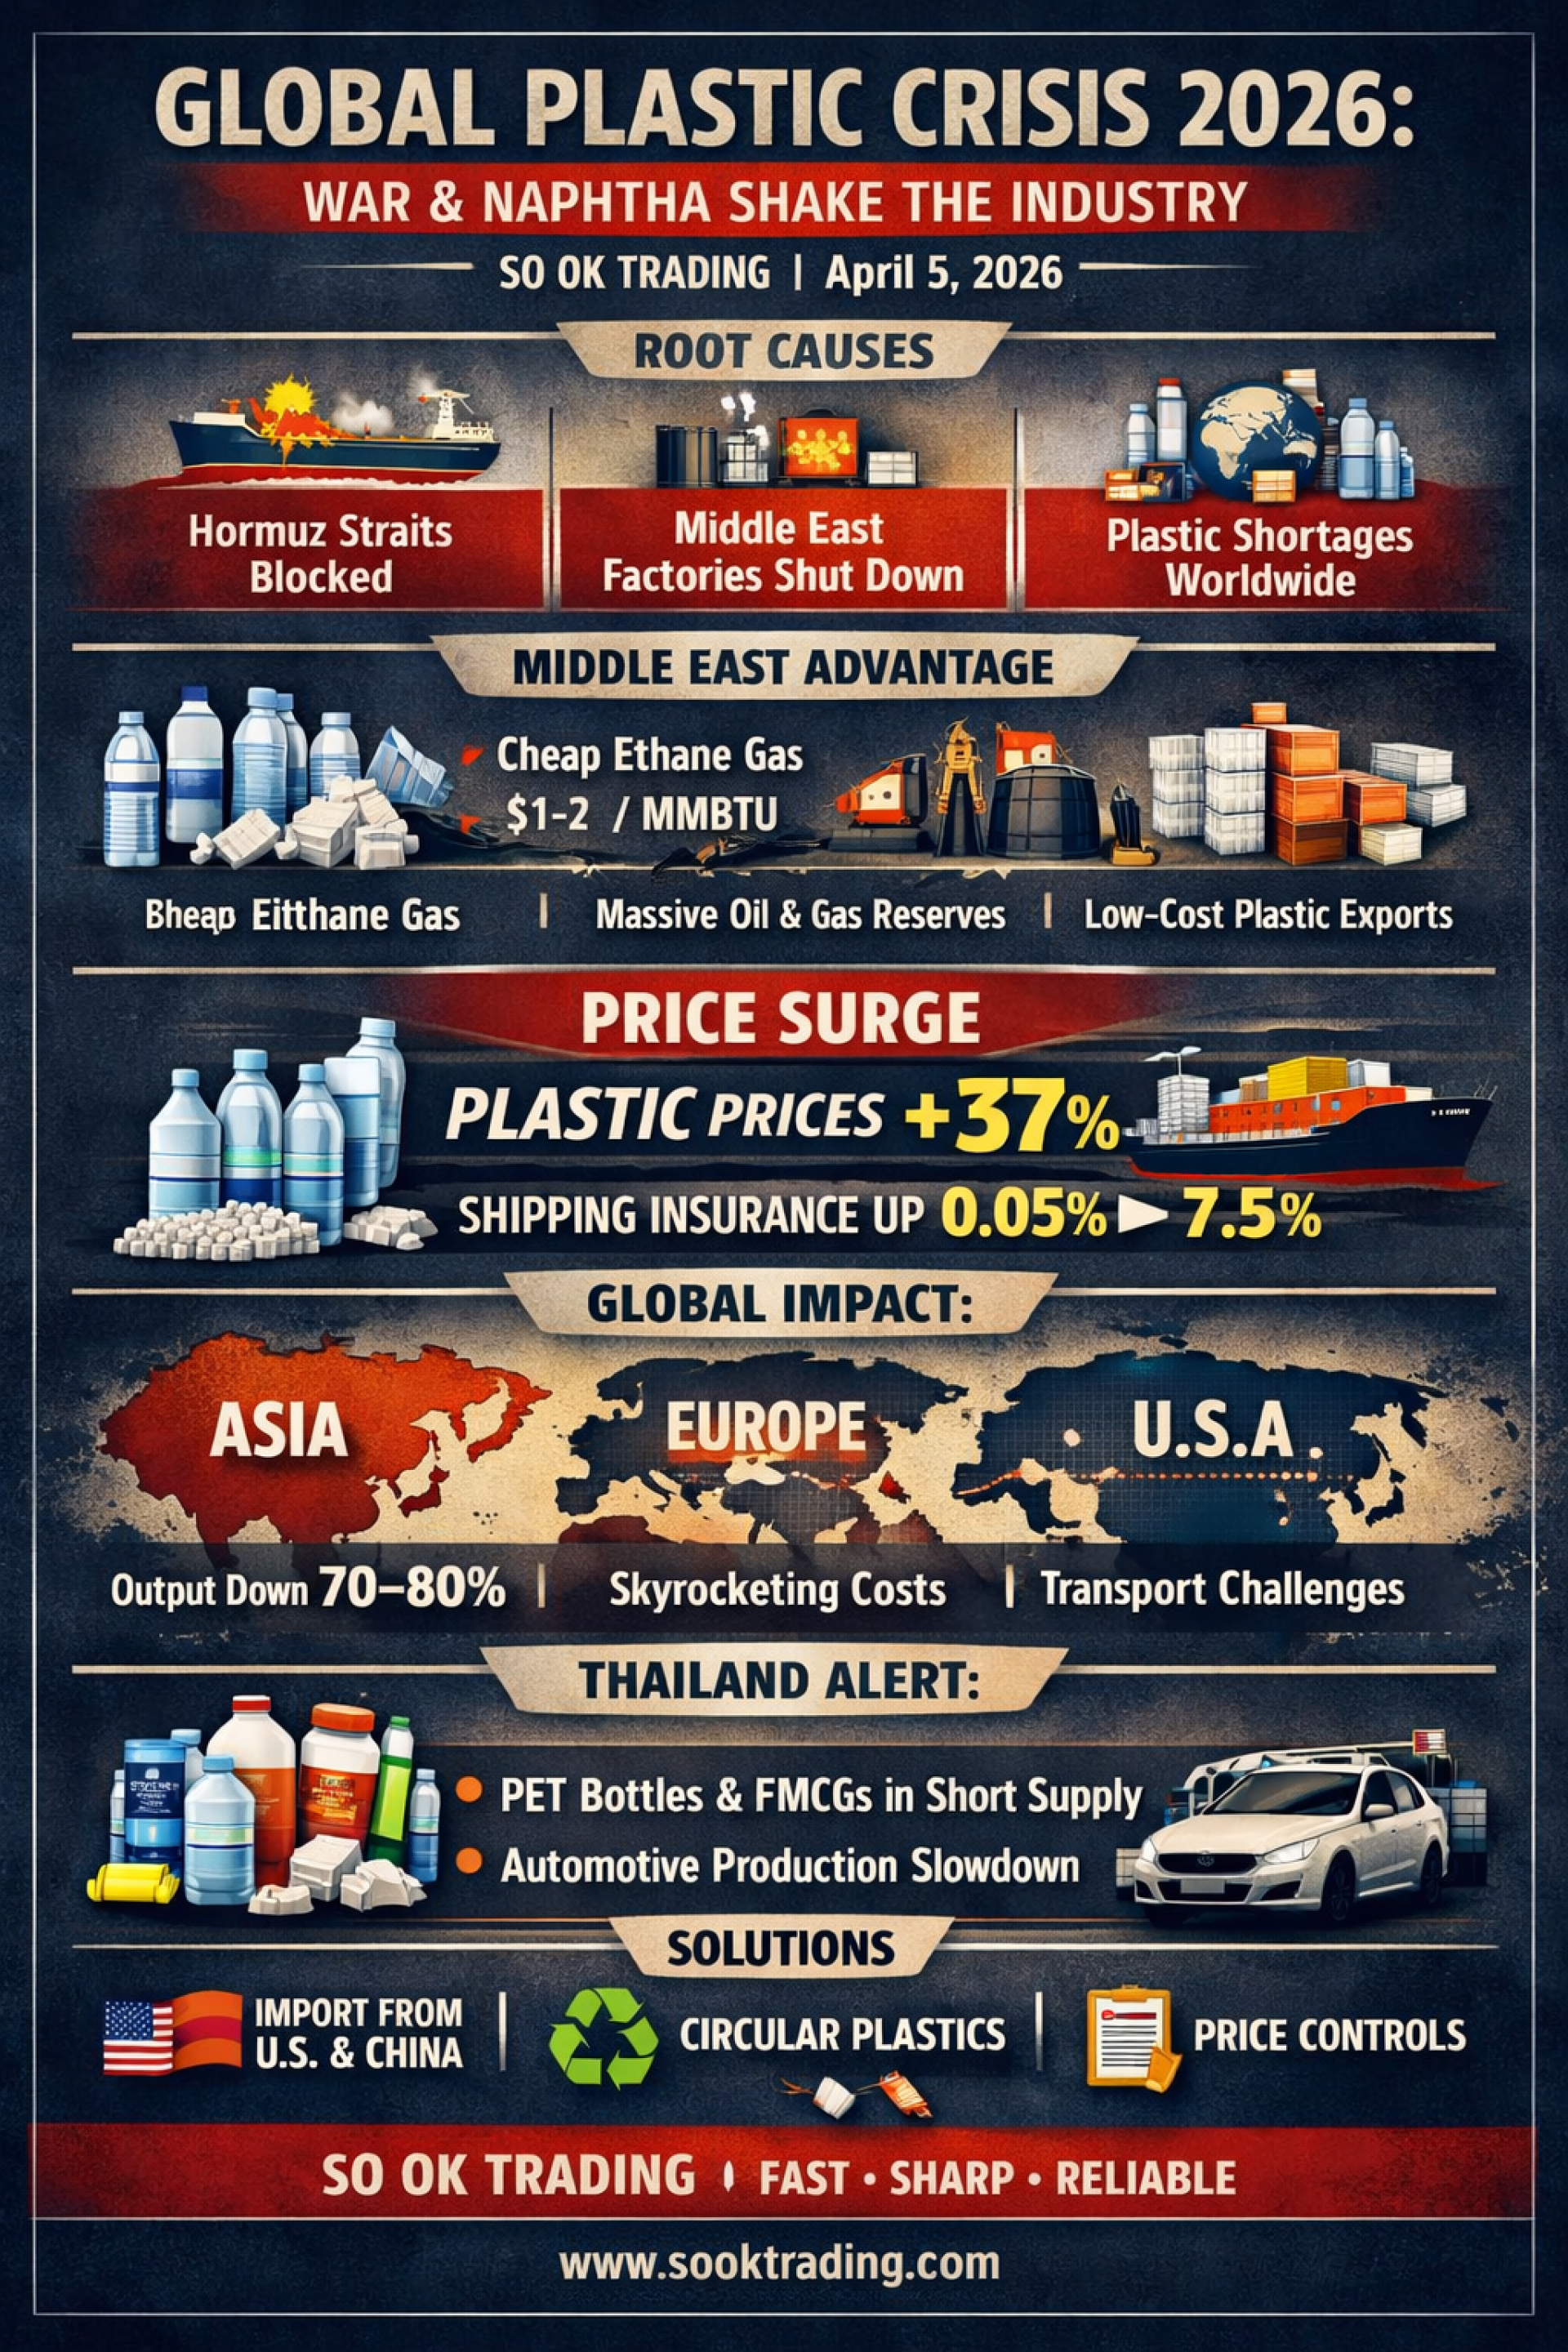
Global Plastic Crisis 2026: How War and Naphtha Shook the Industry
Article by SO OK TRADING | April 5, 2026
Plastic — once considered a basic raw material of everyday life — has now become a “scarce commodity” shaking the world in April 2026. The Middle East conflict and the global naphtha shortage have delivered a heavy blow to the petrochemical industry, driving plastic prices sharply upward and impacting every sector, from food packaging to automotive components.
Roots of the Crisis
Middle East War: The Hormuz Strait blockade halted over 84% of Polyethylene (PE) export capacity.
Factory Shutdowns: Plants in Iran and neighboring countries ceased operations due to attacks and power shortages.
“Money Can’t Buy It”: Plastic granules disappeared from the market, leaving buyers empty-handed despite soaring prices.
Why the Middle East is the Heart of Plastics
Vast reserves of oil and natural gas
Cheap ethane gas ($1–2/MMBTU) used for plastic production
Heavy investment in midstream industries, making the region the world’s lowest-cost exporter of plastic Yet, once export routes were blocked, shipping and insurance costs skyrocketed, erasing the advantage of low production costs.
Price and Cost Impact
Global plastic prices surged 37–38% in just one month
Shipping insurance jumped from 0.05% to 7.5% of vessel value
Naphtha shortage: Asia and Europe, heavily dependent on naphtha, face costs 5–10 times higher than Middle East ethane-based production
Regional Impact
Asia (Thailand, Japan, South Korea): Petrochemical plants cut output to 70–80%. PET bottles and plastic bags are in severe shortage.
Europe: With Russian imports cut and Middle East supply disrupted, Europe faces the world’s highest plastic prices. Many factories have idled.
United States: Slightly advantaged by ethane use, but still hit by rising transport costs and global volatility.
Thailand’s Situation
Stock Running Out: Experts warn reserves may last only until after Songkran.
Industries Hit Hard:
Food & Beverage Packaging: PET bottles and bags scarce; small producers struggle.
FMCG: Packaging costs rose from 10–15% to nearly 25% of product price; refill packs promoted.
Automotive & Electronics: Engineering-grade plastics short; assembly lines slowed.
Government Measures: “Blue Flag” program to stabilize prices and promote recycled plastics (rPET/rHDPE).
Solutions Moving Forward
Import negotiations with the U.S. and China despite higher transport costs
Circular Plastics: Boosting recycled plastic use to reduce reliance on virgin materials
Price Controls: Ministry of Commerce monitoring to prevent unfair price hikes
Conclusion
This crisis is not just about “rising costs” — it is about “shortages” that are reshaping industries worldwide. Unless the Middle East conflict eases soon, petrochemical recovery may take until the end of 2026, with global production and consumption patterns undergoing dramatic change in the meantime.
SO OK TRADING Your Trusted Business Partner FAST • SHARP • RELIABLE www.sooktrading.com


Related Content
China: The Global Aluminum Powerhouse
SO OK TRADING | 28 SEP 2026
As the world moves toward clean energy and future technologies, aluminum has become one of the most strategic metals of our time. From electric vehicles (EVs) and renewable energy infrastructure to aerospace and sustainable packaging, aluminum plays a vital role across industries.
China, as the world’s largest producer and exporter of aluminum, accounts for more than half of global output. It is also the hub of cutting-edge manufacturing technologies. Unsurprisingly, China is recognized as the “Global Aluminum Powerhouse”, shaping the direction of the international market.
This article by SO OK TRADING provides an in-depth look into China’s aluminum market — covering production structures, key players, pricing references, and market outlook for 2026–2027. It also explores opportunities and strategies for Thai businesses to manage costs and mitigate risks in the evolving global metals landscape.
SO OK TRADING — FAST • SHARP • RELIABLE
Your trusted partner in the world of strategic metals.
28 Sept 2026
Global Metal Market Powerhouses: LME vs ShFE
(London Metal Exchange & Shanghai Futures Exchange)
SO OK TRADING : October 4, 2026
Introduction
In the global trade of non-ferrous metals, two exchanges dominate the stage in setting world-standard prices — the London Metal Exchange (LME) from the United Kingdom and the Shanghai Futures Exchange (ShFE) from China.
These two markets stand as the “twin pillars” of the global metals industry, reflecting both the pulse of the world economy and the industrial heartbeat of China.
LME serves as the international hub for metal trading, using the US dollar (USD) as the benchmark currency and providing the global reference price relied upon by industries worldwide.
ShFE mirrors China’s domestic supply and demand, trading in renminbi (RMB) with value-added tax (VAT) included, and driven by the power of Chinese producers and industrial enterprises.
As the world transitions toward clean energy and electric vehicles (EVs), demand for copper, nickel, and aluminium continues to surge. This makes both exchanges critical in shaping the direction of global raw material pricing.
Far from being rivals, LME and ShFE are strategic partners — bridging East and West, balancing international benchmarks with China’s domestic realities.
SO OK TRADING
Your trusted partner in NON-FERROUS METALS from Thailand
FAST • SHARP • RELIABLE
4 Oct 2026
