“Antimony Supply Chain in Indochina: The Strategic Mineral Shaking the World” SO OK TRADING | 13 OCT 2026
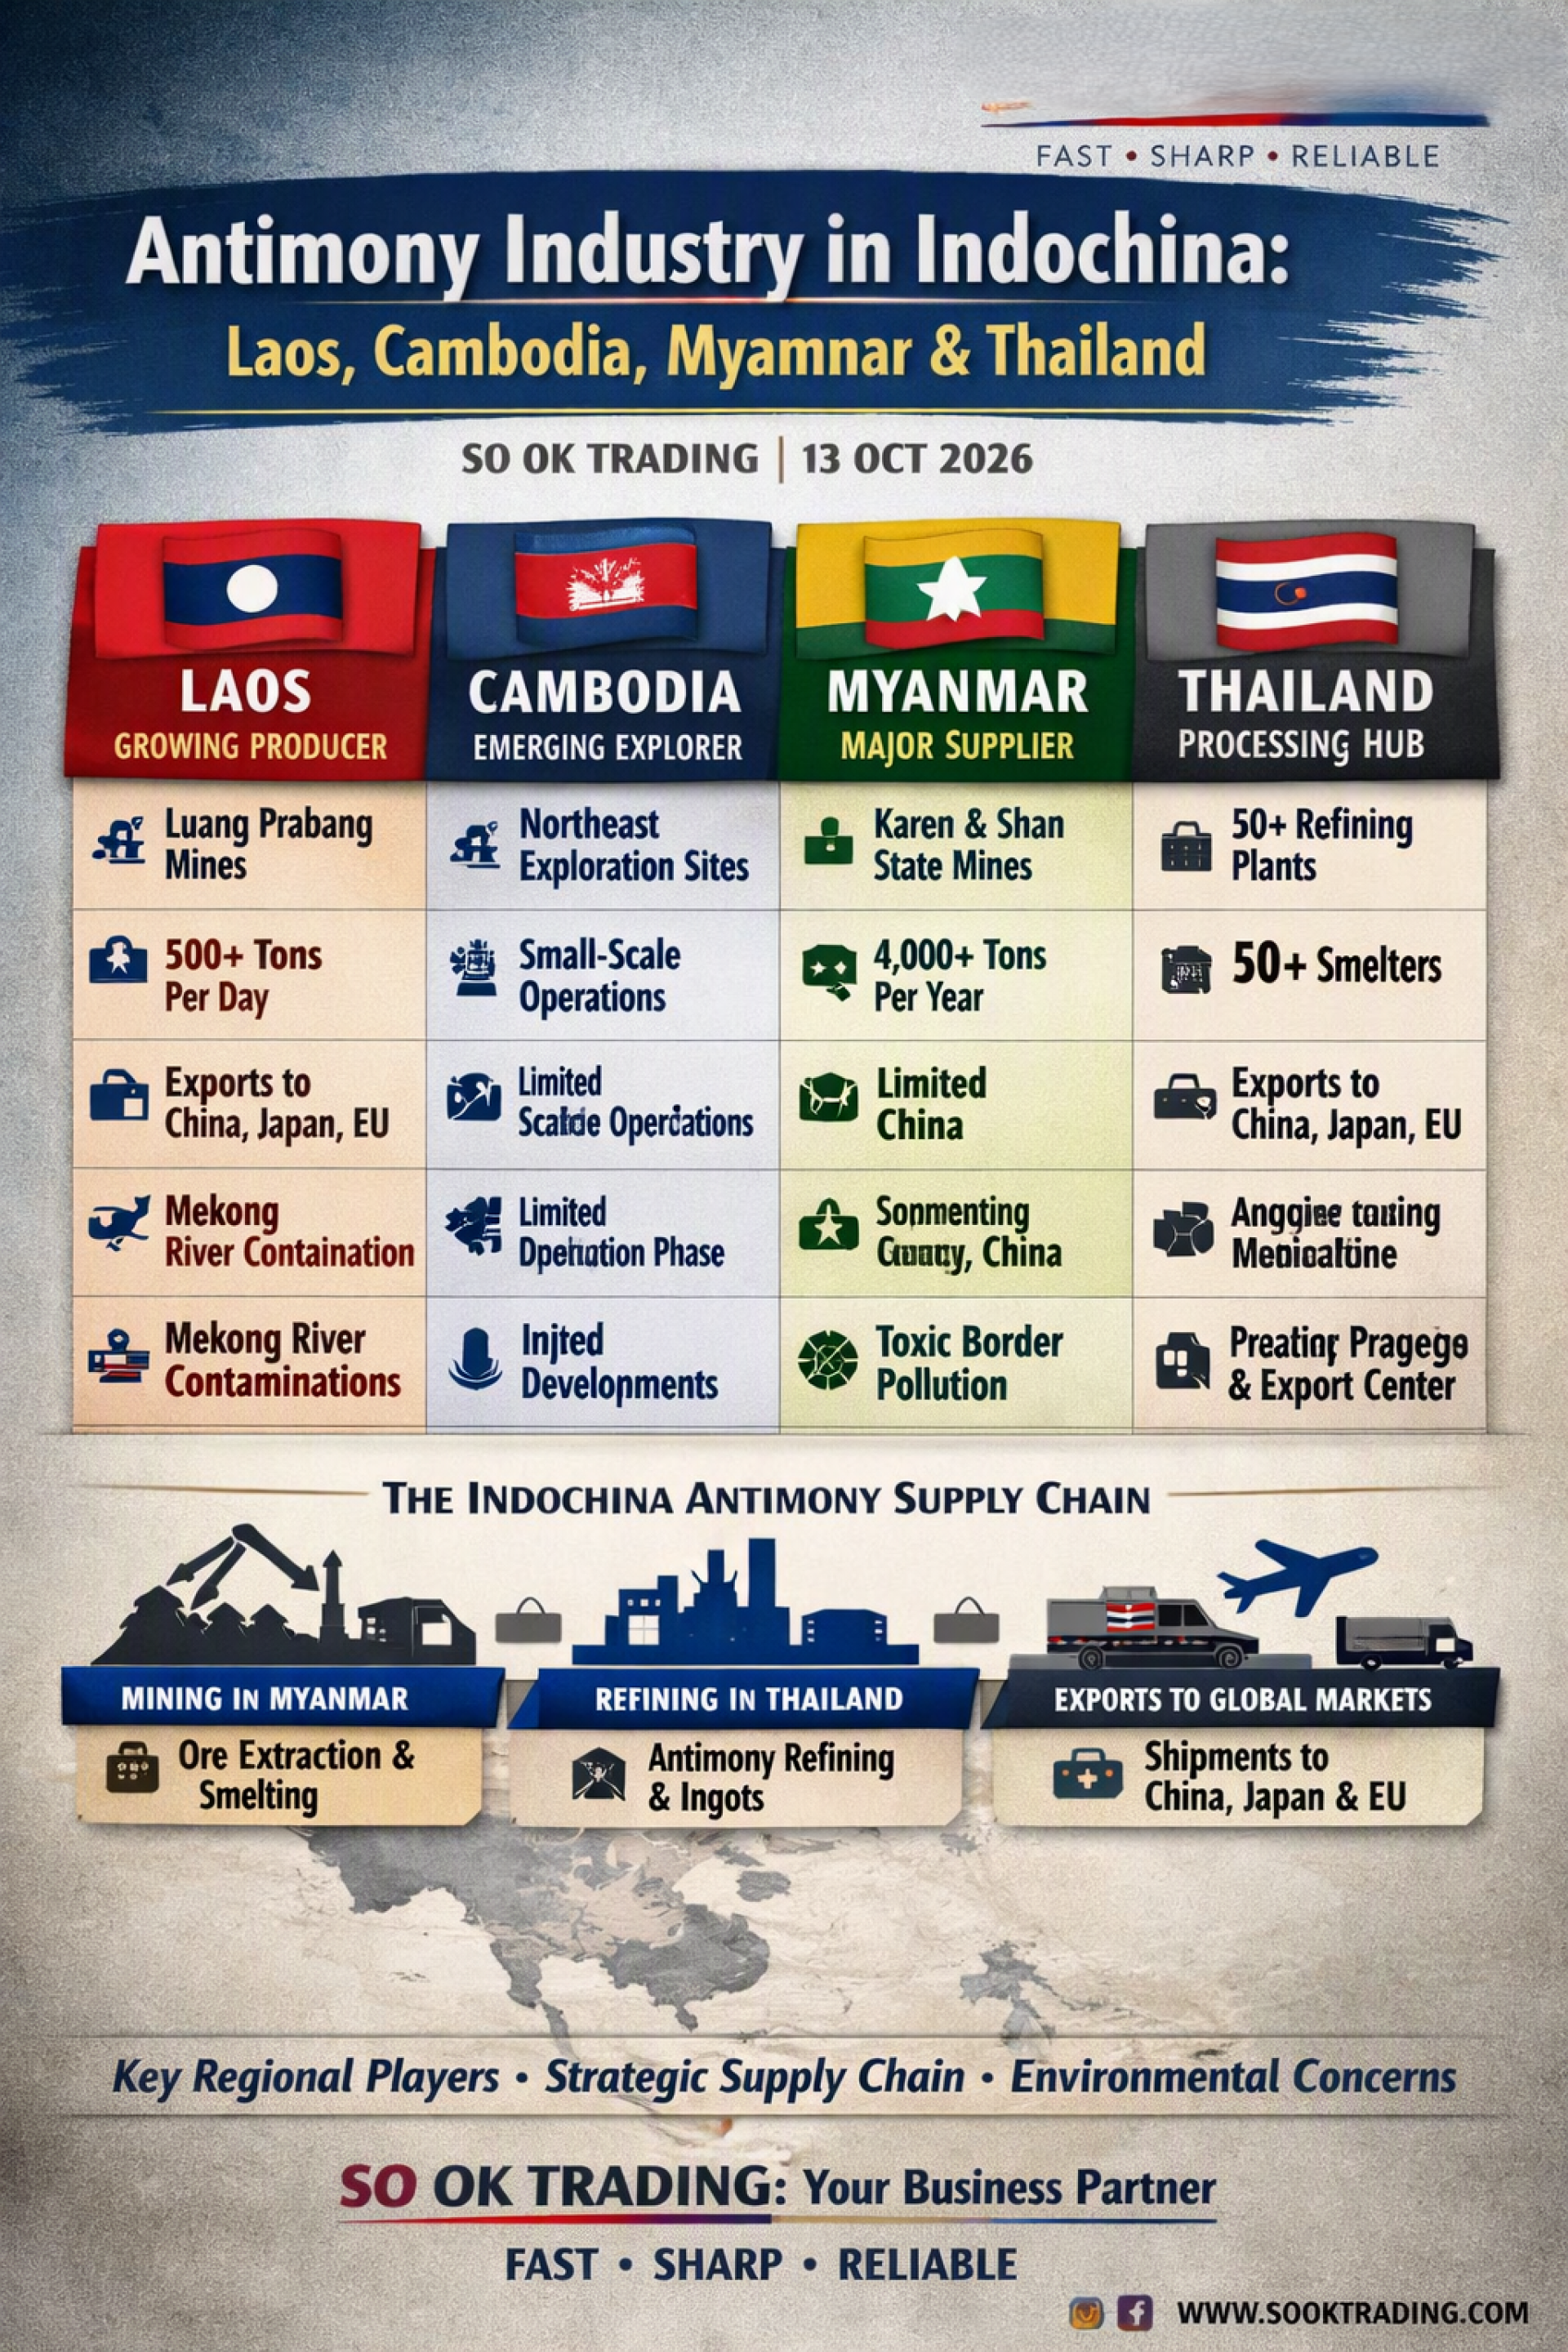
In‑Depth Summary: Antimony in Cambodia, Laos, Myanmar and Thailand’s Role
SO OK TRADING | 13 OCT 2026
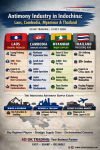
Antimony (Sb) has been elevated to a Critical Mineral, essential for clean energy, advanced technology, and defense industries. The Indochina region — Cambodia, Laos, and Myanmar — is increasingly tied to the global supply chain, while Thailand has risen as a powerful hub for processing and exports.
Laos: Rapidly Growing Production & Smelting Base
Resources & Deposits: Northern Laos, especially Luang Prabang, hosts high‑quality antimony reserves. Chinese and Thai investors continue exploration and mining.
Export Policy: Raw ore exports are banned; only refined or semi‑processed products are allowed.
Production Capacity: Processing plants handle up to 500 tons/day, producing ingots with 99.65–99.95% purity.
Markets: Exports to China, Japan, and Europe, with Chinese capital using Laos as a low‑cost smelting base.
Environmental Impact: Mining has caused arsenic and heavy‑metal contamination in the Mekong River, affecting ecosystems and communities.
Cambodia: Industry in Early Development
Exploration & Concessions: Government permits private companies to explore in northeastern provinces such as Ratanakiri and Mondulkiri.
Production Status: Not yet competitive with Laos or Myanmar; mostly small‑scale mines or ore collection for export.
Industry Structure: Limited reserves; focus remains on iron and gold. Antimony is processed mainly in Chinese‑owned smelters established in Cambodia.
Myanmar: One of the World’s Largest Producers
Reserves: Estimated at 140,000 metric tons; annual production averages 4,000–4,500 metric tons.
Key Deposits: Karen State (Thabyu Mine, Three Pagodas Pass) and Shan State (Muse–Tachileik corridor).
Profit Structure: Many mines are controlled by ethnic armed groups (EROs), with revenues funding ongoing conflicts.
Supply Chain: Antimony flows through Thailand to China, with Thailand as the main processing route.
Environmental Issues: Lack of standards leads to toxic discharges into the Salween, Kok, Ruak, and Sai rivers, affecting both Myanmar and Thailand.
Thailand: Processing & Export Hub
Role: More than a transit point — Thailand is a central hub for importing, refining, and exporting antimony ingots.
Smelting Plants: Over 50 companies, both Thai and Chinese, operate in northern, western, and central provinces (Tak, Kanchanaburi, Ratchaburi, Sukhothai, Lampang).
Production Process: Imports raw ore and ingots from Myanmar, refines them in high‑temperature furnaces (1,000–1,200 °C), then exports to China, Japan, and Europe.
Case Study: In 2026, a furnace explosion in Kanchanaburi highlighted risks from accelerated production and industrial waste.
Supply Chain: Unified structure — mining in Myanmar ➡ refining in Thailand ➡ exports to China.
Regional Connectivity
Laos & Cambodia: Emerging as supplementary bases to diversify supply chain risks.
Myanmar: A major producer with political and environmental complexities.
Thailand: The central hub linking Indochina’s supply chain to global markets.
✨ Overall Summary
Laos: Growing into an international ingot production base.
Cambodia: Still in early stages, focused on exploration rather than commercial production.
Myanmar: A major producer with political and environmental challenges.
Thailand: The processing and export hub connecting Indochina to the global supply chain.
Indochina plays a critical role in the global antimony market — economically, strategically, and environmentally — with Thailand emerging as the strategic base chosen by multinational capital for refining and exports.
SO OK TRADING – Your Business Partner FAST • SHARP • RELIABLE www.sooktrading.com Facebook: SO OK TRADING