“ASEAN Reshaping the Global Metals Game 2026: Thailand Rising as the Low-Carbon Hub for Copper & Aluminium Recycling” Industry Insight by SO OK TRADING | 10 OCT 2026
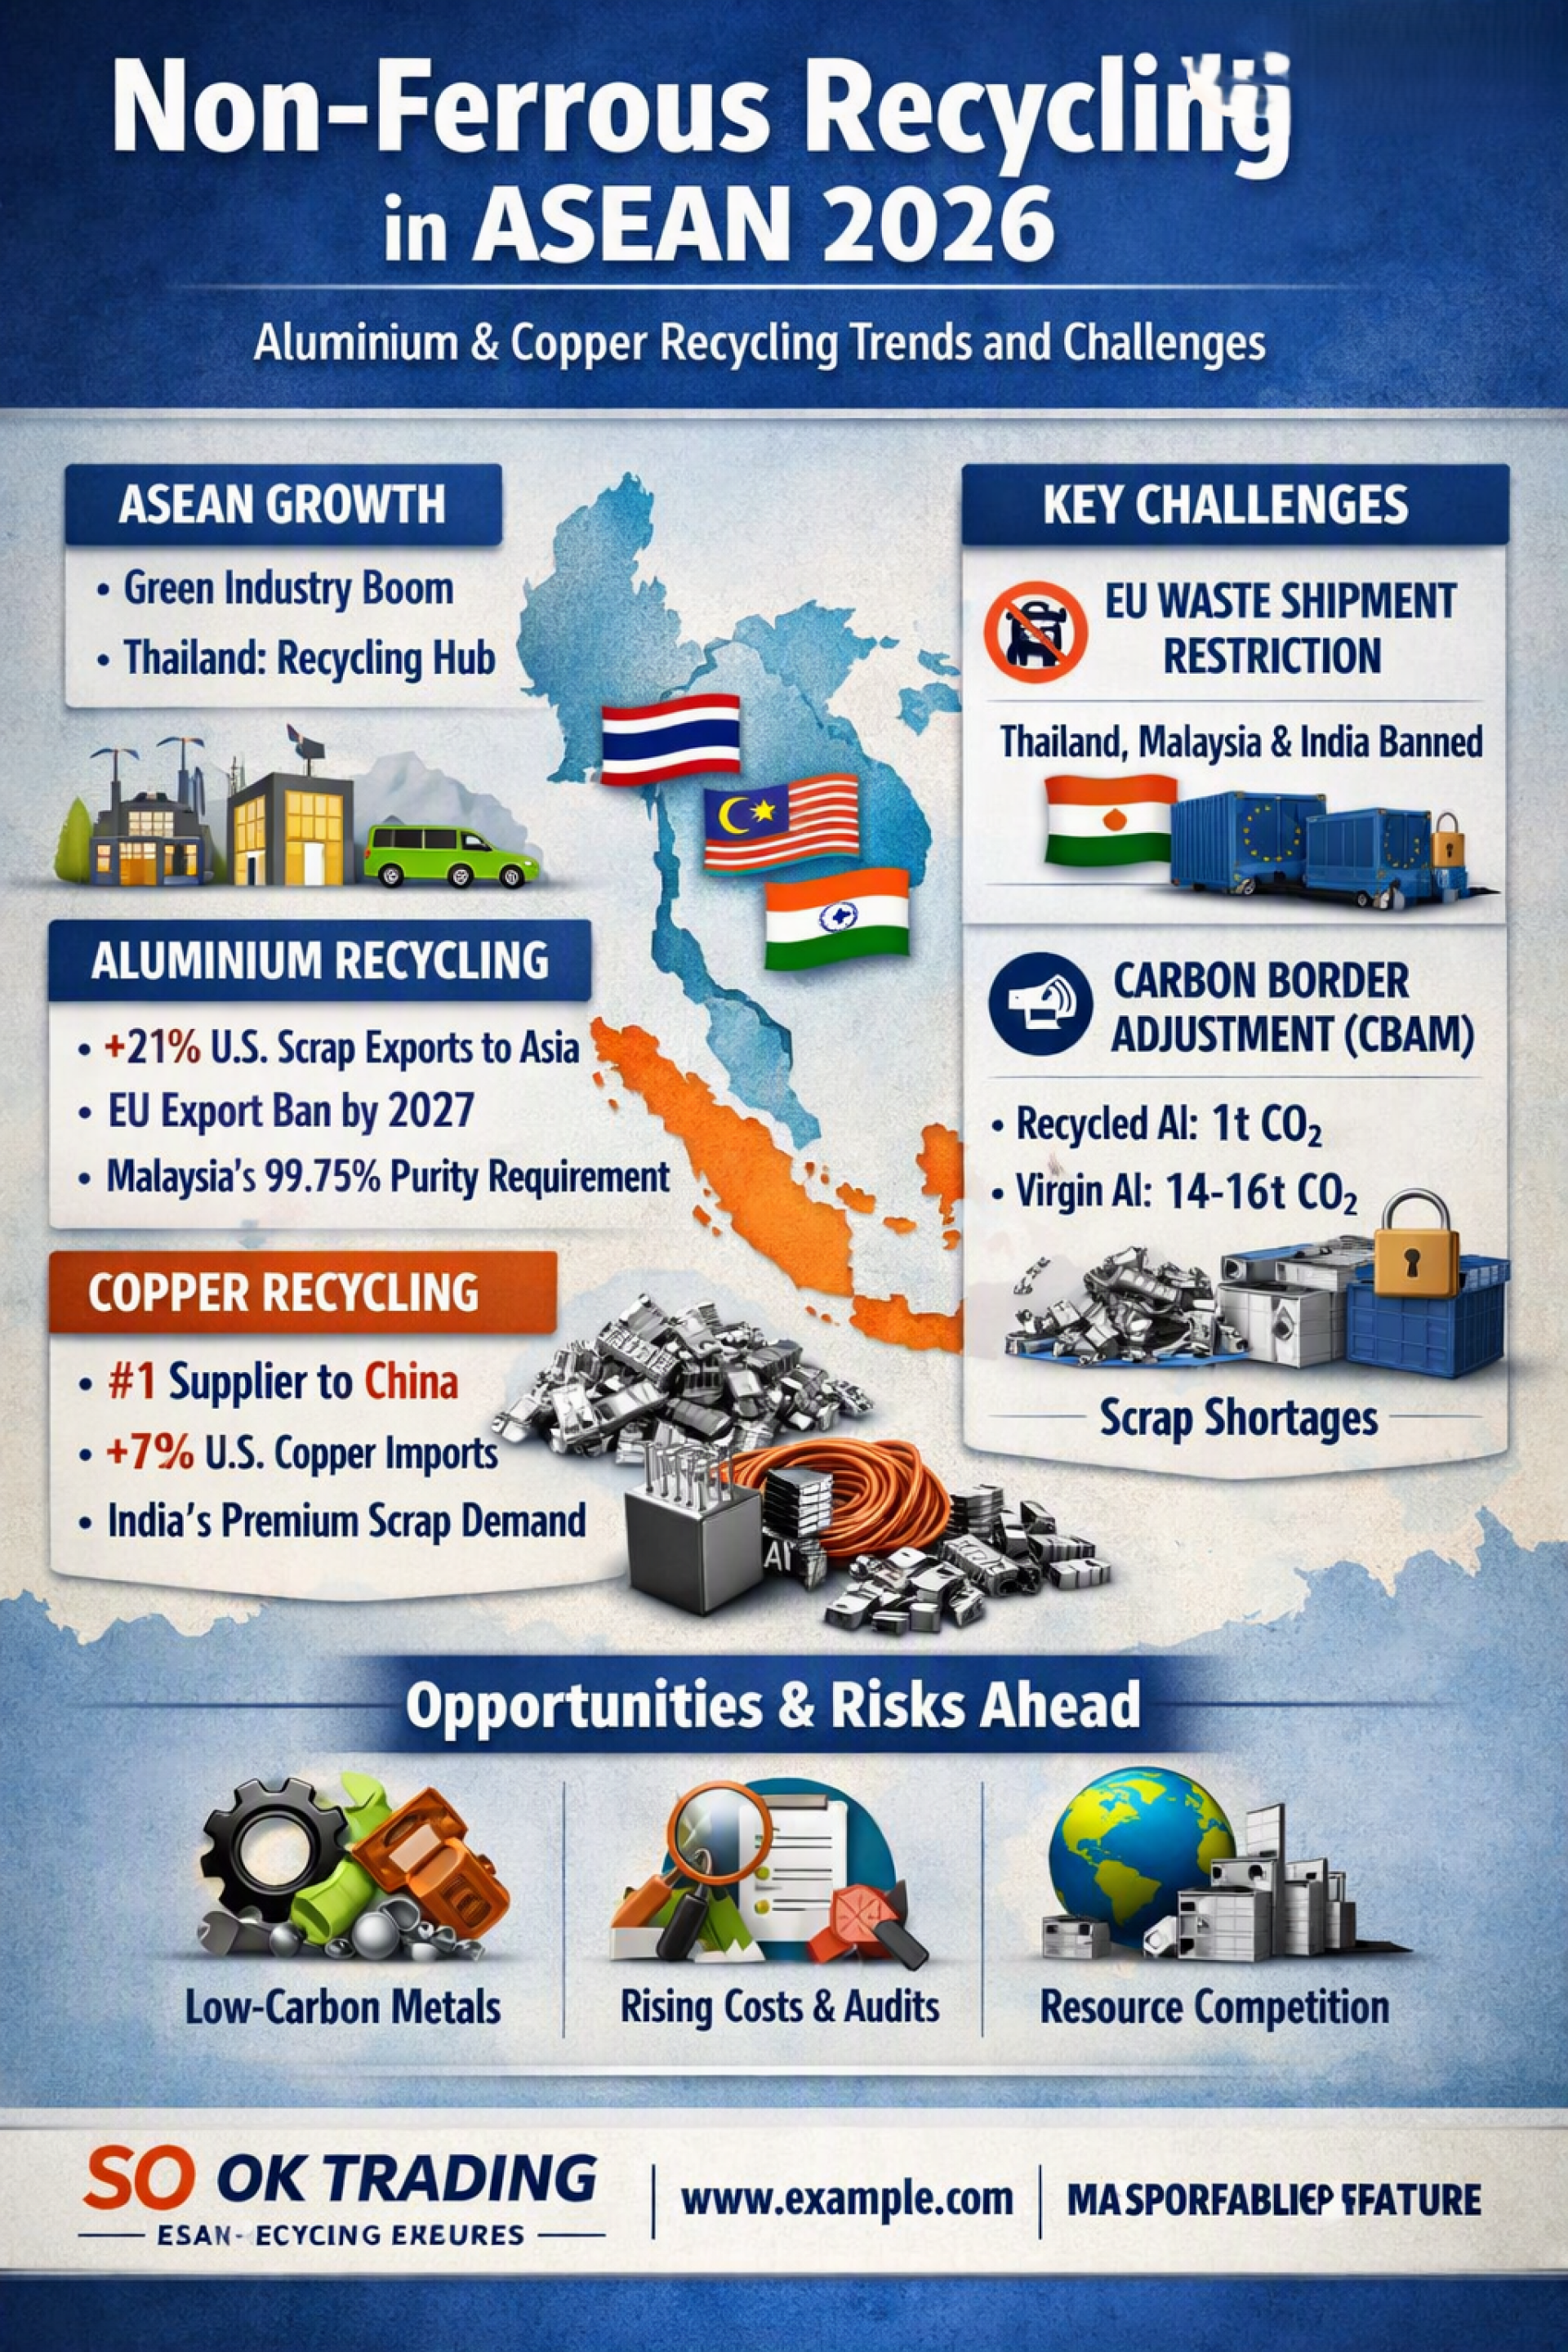
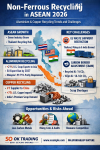
Non-Ferrous Recycling in ASEAN 2026
SO OK TRADING | 10 OCT 2026
Introduction
The year 2026 marks a turning point for the non-ferrous recycling industry in ASEAN. Aluminium and copper have been elevated to the status of strategic global raw materials. ASEAN is no longer just a production and processing base — it is emerging as a central hub in the global supply chain, connecting with major economies such as China, India, the United States, and the European Union. Yet, tightening environmental regulations and international trade measures are placing immense pressure on factories and operators across the region.
Overview
ASEAN is now one of the fastest-growing recycling ecosystems in the world, driven by urban expansion and the green industry boom. Thailand is being positioned as a recycling hub, supported by investments in EV battery industrial estates and circular economy models. However, stricter inspections of mixed scrap (zorba, e-waste) at Thai and Malaysian ports have led shipping lines such as Maersk to suspend operations.
Aluminium Recycling Market
Aluminium is a strategic metal in high demand for EVs and lightweight packaging.
U.S. exports of aluminium scrap to Asia surged by over 21%, with Thailand leading imports at 268,000 tons in the first half of the year.
EU regulations will ban exports of scrap to Thailand, Malaysia, and India starting May 2027 due to environmental compliance issues.
Malaysia enforces strict purity standards (99.75%), causing large volumes of containers to be rejected.
Copper Recycling Market
Copper has earned the title of “New Gold” in the era of clean energy and AI.
Thailand is China’s top supplier, exporting an average of 35,000–36,700 tons per month, accounting for over 16% of China’s imports, valued at nearly USD 2 billion.
U.S. exports of copper scrap to Thailand rose by 17%, surpassing 100,000 tons in the first half of the year.
India is competing for premium-grade copper scrap after Middle Eastern countries restricted exports.
Outlook and Industry Directions
Impact of EU Waste Shipment Regulation (WSR) 2027
Thailand, Malaysia, and India will lose access to European scrap imports, leading to:
A 20% reduction in premium raw materials
Rising inspection and audit costs
Greater reliance on supply from the U.S. and the Middle East
CBAM and the Scrap Paradox
The EU’s Carbon Border Adjustment Mechanism (CBAM) encourages recycled metals to reduce carbon taxes:
Virgin aluminium emits 14–16 tons of CO₂ per ton produced
Recycled aluminium emits less than 1 ton of CO₂ per ton produced
Yet, the Scrap Paradox emerges: while CBAM promotes scrap use, the EU and U.S. retain high-quality scrap for domestic consumption, leaving ASEAN short of raw materials. Meanwhile, China has established smelting plants in Thailand to produce ingots for re-export, lowering its own carbon footprint but driving scrap prices higher in Thailand.
Conclusion
In 2026, ASEAN’s non-ferrous recycling industry — particularly Thailand — faces both opportunities and risks:
Opportunities: Factories that adapt quickly, adopt renewable energy, and implement precise scrap sorting systems can supply low-carbon metals in high demand globally.
Risks: Shortages of premium raw materials and rising audit costs may erode competitiveness if standards are not upgraded.
If Thailand successfully transitions to a circular economy with green standards, it can secure a strategic role in the global recycling metals market and gain a competitive edge in the era of clean energy and low-carbon economies.
SO OK TRADING: Your Business Partner FAST • SHARP • RELIABLE
VISIT US: www.sooktrading.com FACEBOOK: SO OK TRADING