SO OK TRADING INSIGHT: Global Economic Turning Point Q4/2026 — As Superpowers Slow, ASEAN Emerges as the New Growth Engine of Southeast Asia 15 SEP 2026
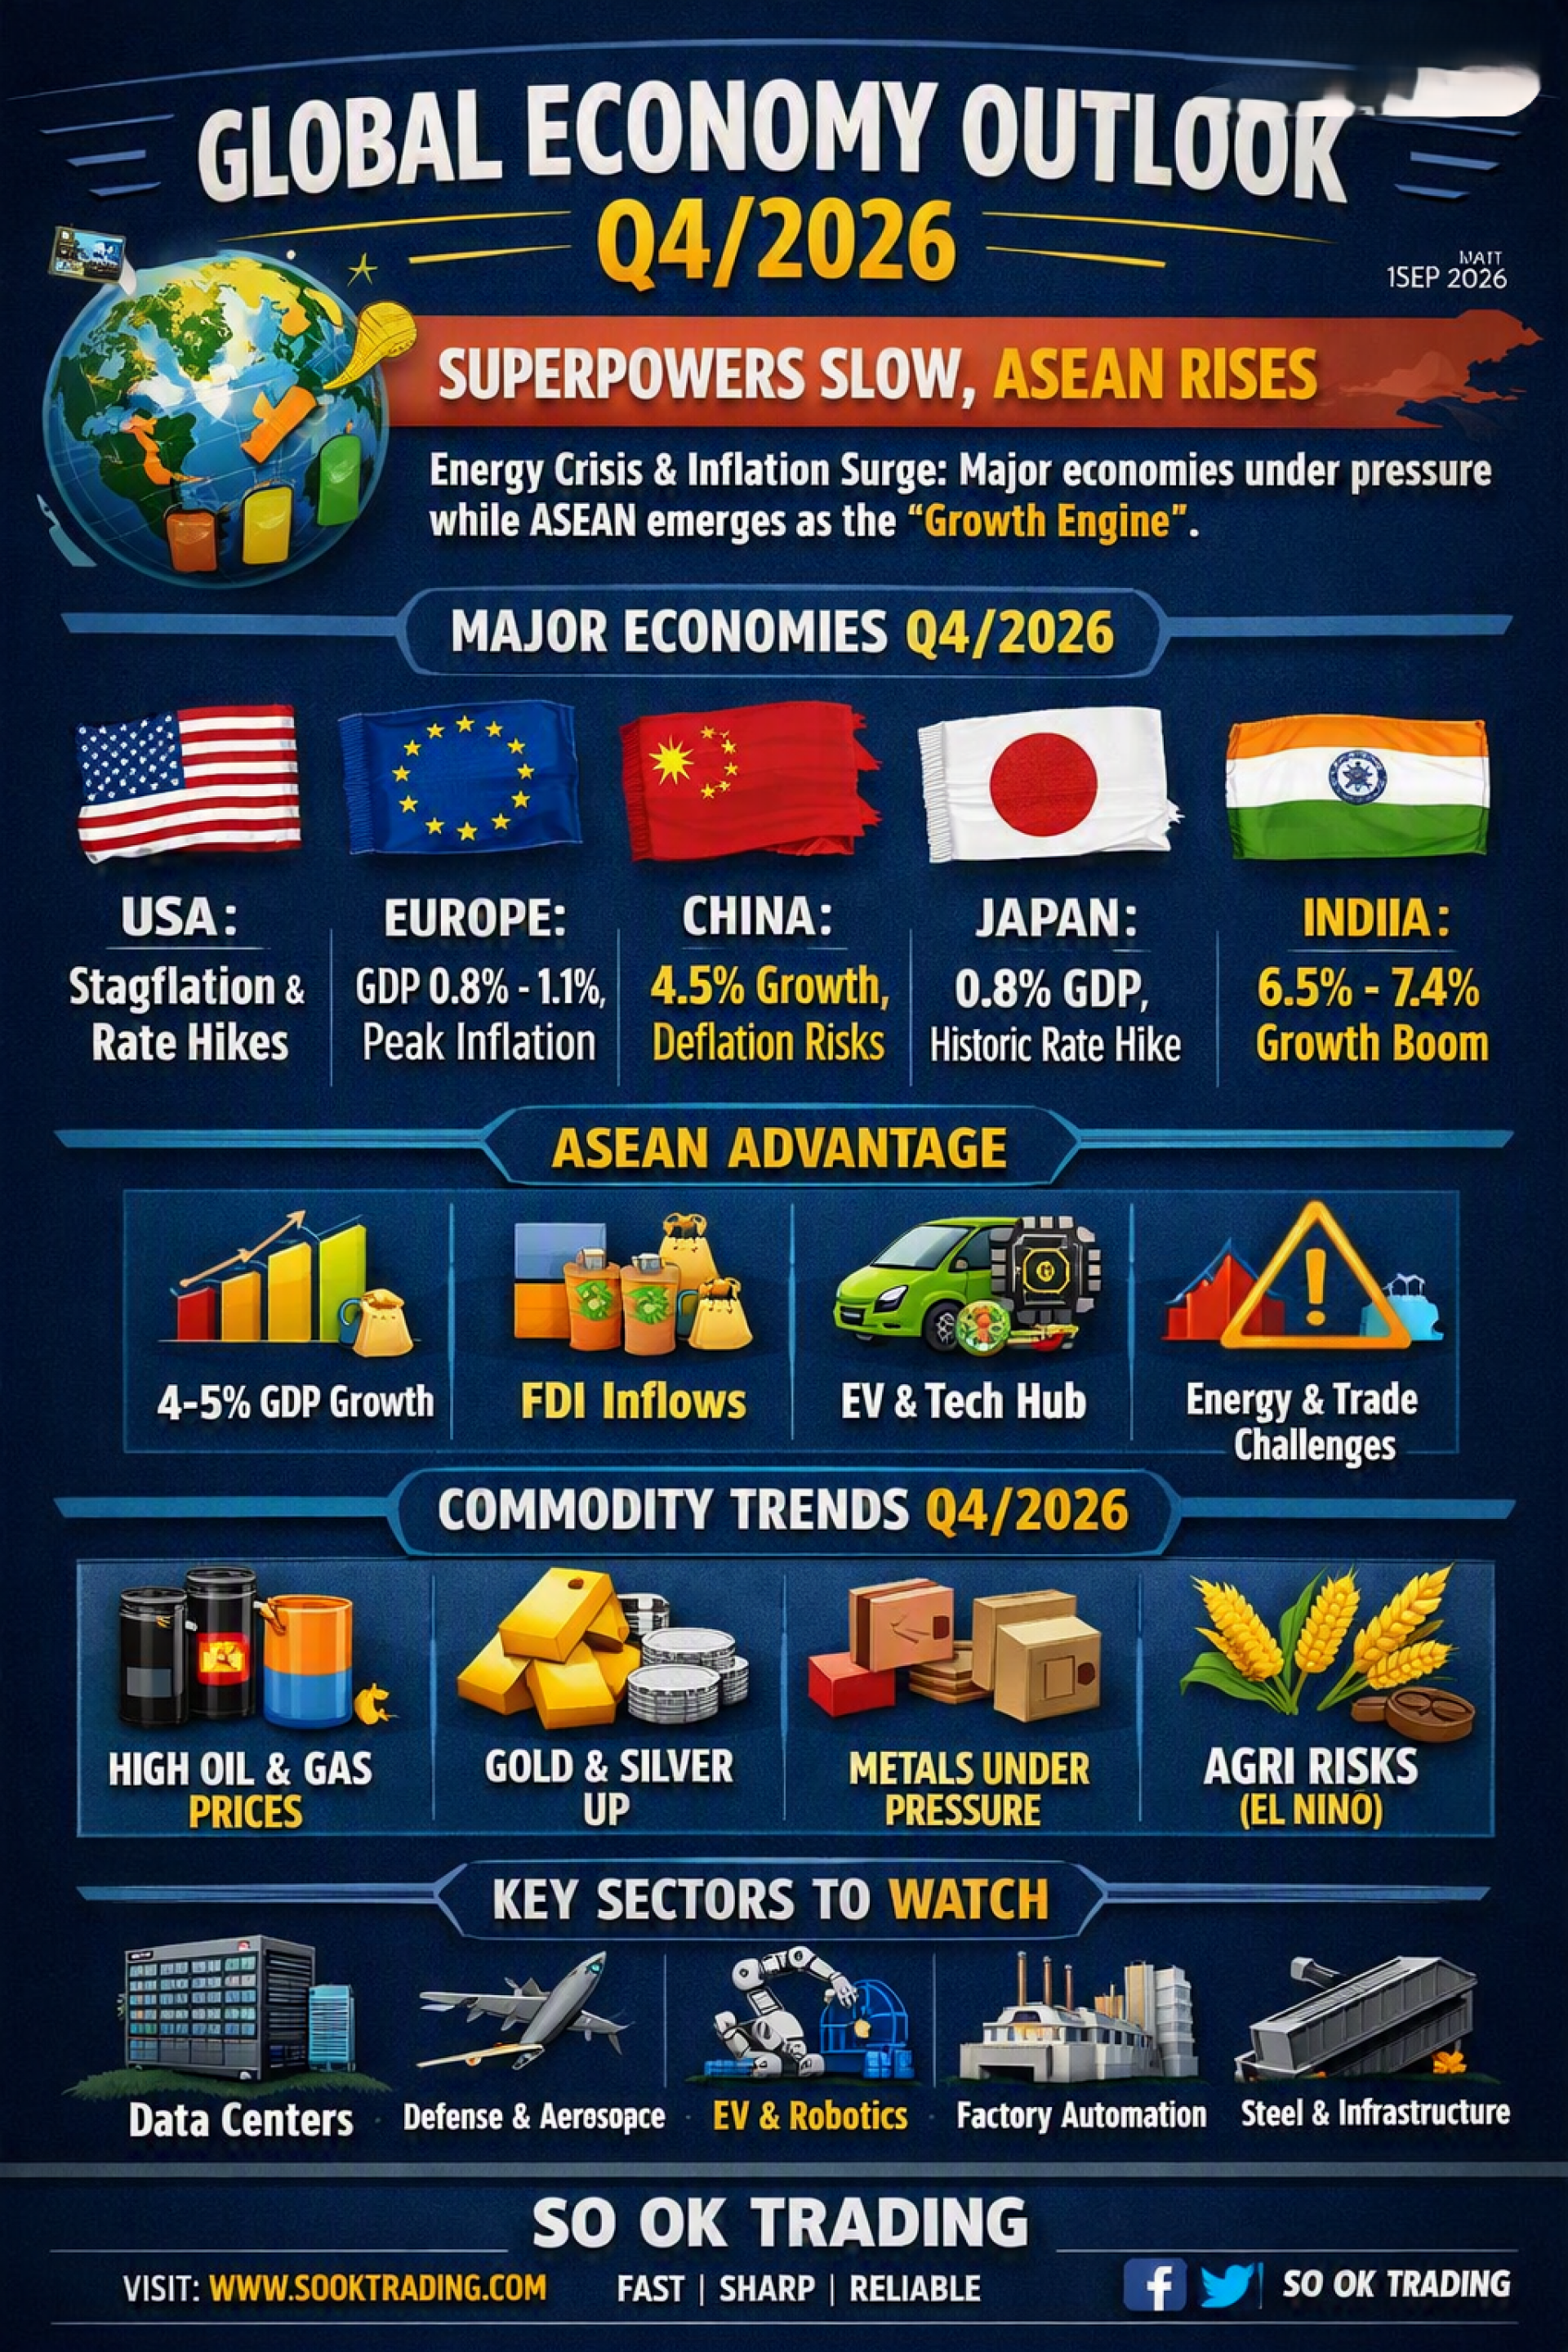
Global Economy Q4/2026: When Superpowers Slow, ASEAN Still Soars
SO OK TRADING: September 15, 2026
A Turning Point for the Global Economy
The fourth quarter of 2026 marks a critical turning point for the global economy, pressured by a new energy price crisis stemming from Middle East tensions and a resurgence of inflation that has forced many central banks back into tightening mode. Major powers—the United States, Europe, China, Japan, and India—each face unique challenges. Yet ASEAN stands out as a region with positive momentum, increasingly seen as the next “Growth Engine” of the global economy.
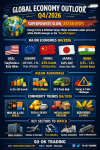
Outlook for Major Economies Q4/2026
United States: Facing stagflation risks, with Core PCE inflation near 3.4%. The Fed signals rate hikes. Vulnerabilities include a tech/AI stock bubble and high public debt.
Europe: GDP growth only 0.8–1.1%, inflation rising to 3.6%. The ECB keeps rates high to combat energy costs. Infrastructure and defense spending provide support.
China: GDP target cut to ~4.5%, deflation risks loom. Government stimulus continues, but Western tariffs weigh heavily.
Japan: GDP ~0.8%, inflation ~2.2%. The BOJ makes a historic rate hike to stabilize the weak yen.
India: Strong GDP growth of 6.2–7.4%, driven by domestic demand and FDI. Risks remain from food and energy inflation.
Future Directions
US/EU: High inflation and volatile energy costs persist. Tech and infrastructure investment remain pillars, while traditional manufacturing struggles.
China: Domestic slowdown continues, but clean energy and EV exports to emerging markets expand, fueling ongoing friction with the West.
Japan: Industrial restructuring and automation investment help maintain competitiveness, despite high energy costs.
India: The standout performer, benefiting from “China+1” supply chain shifts, with potential to become a hub for electronics and infrastructure manufacturing.
ASEAN in Comparison
While major powers face headwinds, ASEAN demonstrates distinct strengths:
Growth: Averaging 4–5%, higher than Europe and Japan but below India.
Drivers: FDI flows into Thailand, Vietnam, and Indonesia, fueled by the China+1 trend.
Risks: High energy prices and competition from low-cost Chinese goods pressuring traditional manufacturing.
Opportunities: Relocation of EV, semiconductor, and green industry production positions ASEAN as a key stage for the global economy’s future.
Commodity Trends Q4/2026
Energy (Oil/Gas): Prices remain elevated due to Middle East tensions and Europe’s winter demand.
Precious Metals (Gold/Silver): Strong upward trend driven by stagflation risks and central bank gold accumulation.
Industrial Metals (Copper/Aluminum): Pressured by China’s economic slowdown.
Agriculture: Risks from El Niño/La Niña weather patterns and high fertilizer costs.
Key Industries vs. Watchlist
United States: Key = Data Centers, Semiconductors, Advanced Manufacturing | Watch = Traditional Automobiles
Europe: Key = Defense & Aerospace, Cleantech | Watch = Chemicals, Primary Steel
China: Key = High-Tech & Robotics, EV Exports | Watch = Real Estate, Construction Materials
Japan: Key = Electronic Components, Factory Automation | Watch = Domestic Consumer Goods
India: Key = Steel & Infrastructure, Electronics Assembly
Conclusion
Q4/2026 is a period where global markets face new inflationary waves + energy crises, yet it also opens investment opportunities in gold, energy, and infrastructure industries. At the same time, ASEAN’s rise in EVs, clean technology, and advanced manufacturing could become a pivotal force shaping the global economy in the coming decade.
SO OK TRADING: Your Business Partner SO OK TRADING: FAST SHARP RELIABLE VISIT US AT: WWW.SOOKTRADING.COM FACEBOOK: SO OK TRADING