“Higher for Longer – The World Trapped in Stagnation and Stubborn Inflation: A New Era for Investors” Article by SO OK TRADING : April 30, 2026
“Higher for Longer – The World Trapped in Expensive but Stagnant Growth” Article by SO OK TRADING : April 30, 2026
Big Picture: Global Economy, April 2026
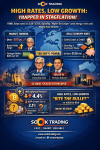
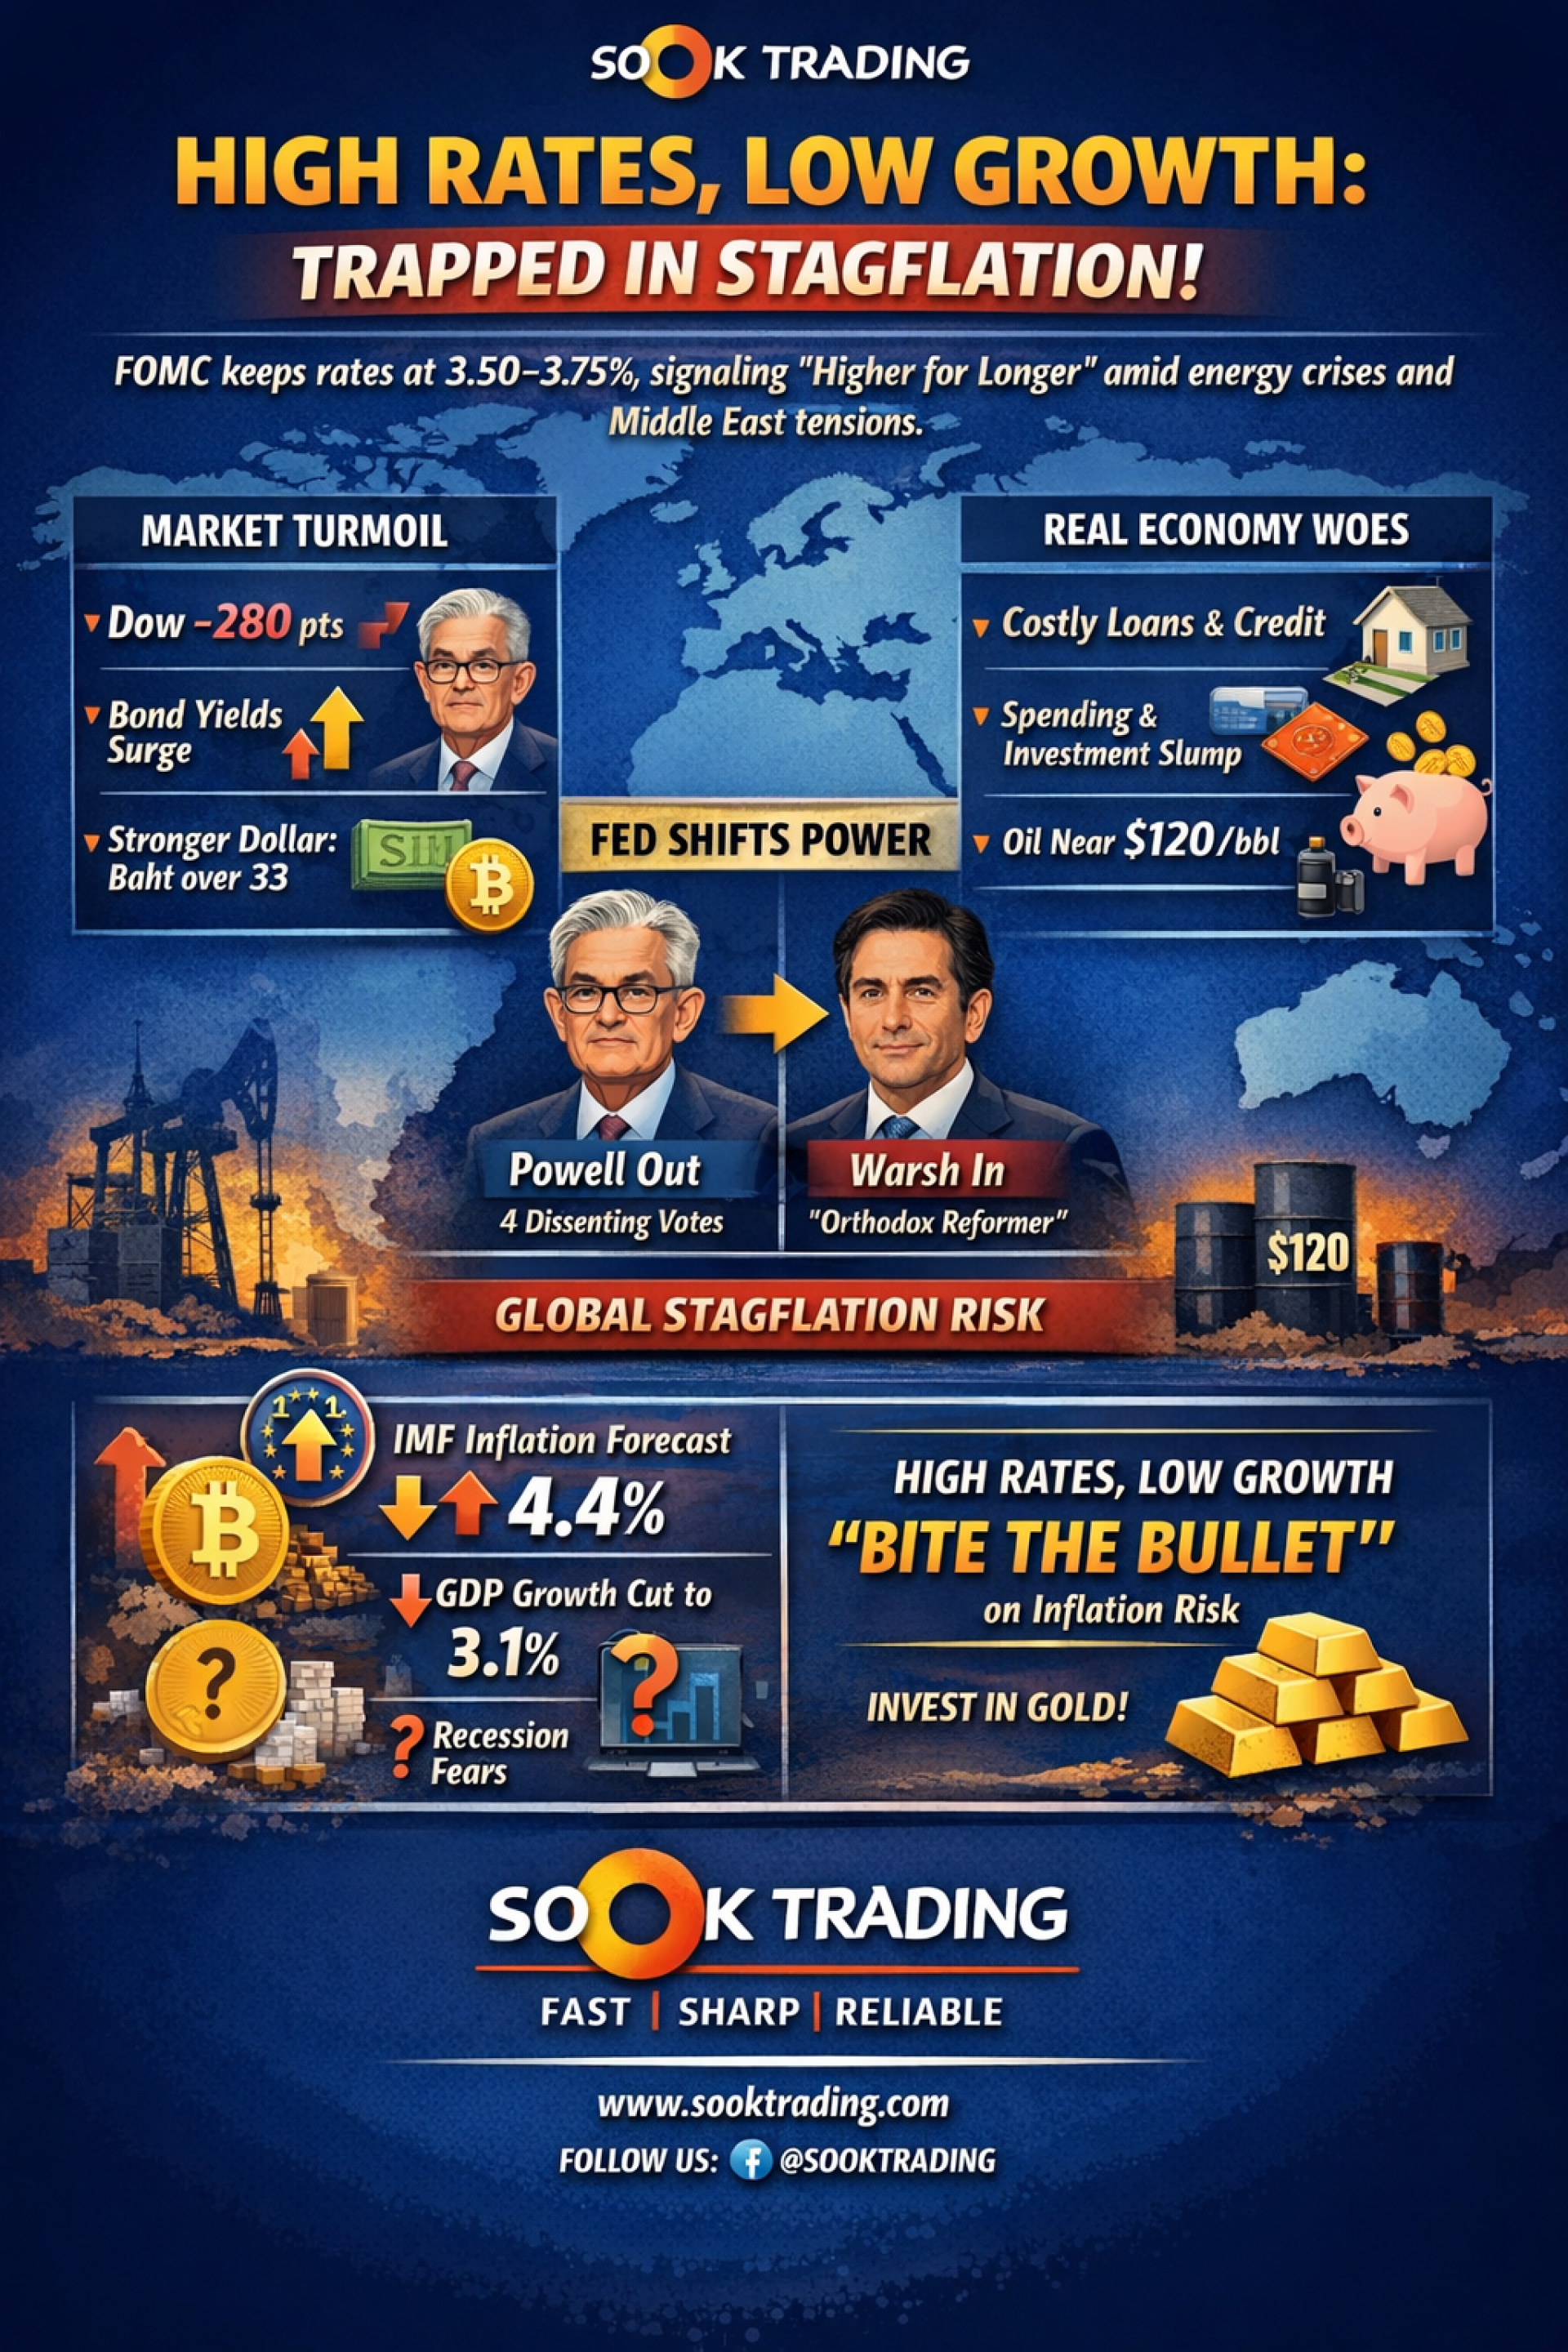
The FOMC meeting on April 28–29, 2026 marked a turning point. The Fed decided to keep interest rates at 3.50–3.75% for the third consecutive time, sending a clear signal that the world is entering the era of Higher for Longer — high interest rates maintained to fight stubborn inflation driven by surging energy prices and Middle East conflicts.
Financial Markets: Volatility to Watch
U.S. Stocks: Dow Jones fell 280 points as investors worried about costly financing.
Bonds: Treasury yields surged, reflecting expectations that rate cuts won’t come soon.
Currencies: The U.S. dollar strengthened, pressuring emerging market currencies; the Thai baht weakened past 33.
Crypto: Bitcoin dropped below $76,000 immediately after the meeting.
Real Economy: Debt Burden Persists
High Borrowing Costs: Mortgages, credit cards, and business loans remain expensive.
Consumption & Investment Slowdown: Households prioritize saving, businesses delay expansion.
Oil Prices Surge: Brent crude nears $120 per barrel amid Middle East tensions.
Fed Division – Powell Hands Over to Warsh
This meeting saw 4 dissenting votes, the highest since 1992.
It was Jerome Powell’s final meeting before handing leadership to Kevin Warsh.
Warsh is viewed as an “Orthodox Reformer”: strict on balance sheet reduction but flexible on rate cuts if the economy slows.
Global Interest Rates: Wait-and-See
ECB (Europe): Deposit rate held at 2.00%, with possible hikes if energy inflation persists.
BoE (UK): Cut rates to 3.75%, but the close vote highlights uncertainty.
BoJ (Japan): Held at 0.75%, though calls to raise to 1.0% are growing.
⚠️ Stagflation Risk: A Perfect Storm
Global Inflation: IMF raised its 2026 forecast to 4.4%.
Global GDP: Growth outlook cut to 3.1%, with risks of dropping to 2% if conflicts drag on.
Policy Dilemma: Rate hikes risk recession, while rate cuts risk fueling inflation.
Conclusion
The world is sliding into the trap of “high prices but no growth.” Central banks are choosing to maintain high rates to curb inflation, even at the risk of recession — ushering in the Higher for Longer era.
Investors should be cautious with risk assets and consider inflation-hedging options such as gold.
SO OK TRADING: Your Business Partner FAST • SHARP • RELIABLE www.sooktrading.com Facebook: SO OK TRADING