“Energy Shock 2026: The LPG/LNG Crisis from the Middle East — Beyond the Oil Supply Shortage” When Qatar’s gas production facilities were attacked, the world faced consequences it could not ignore Article by SO OK TRADING | March 20, 2026
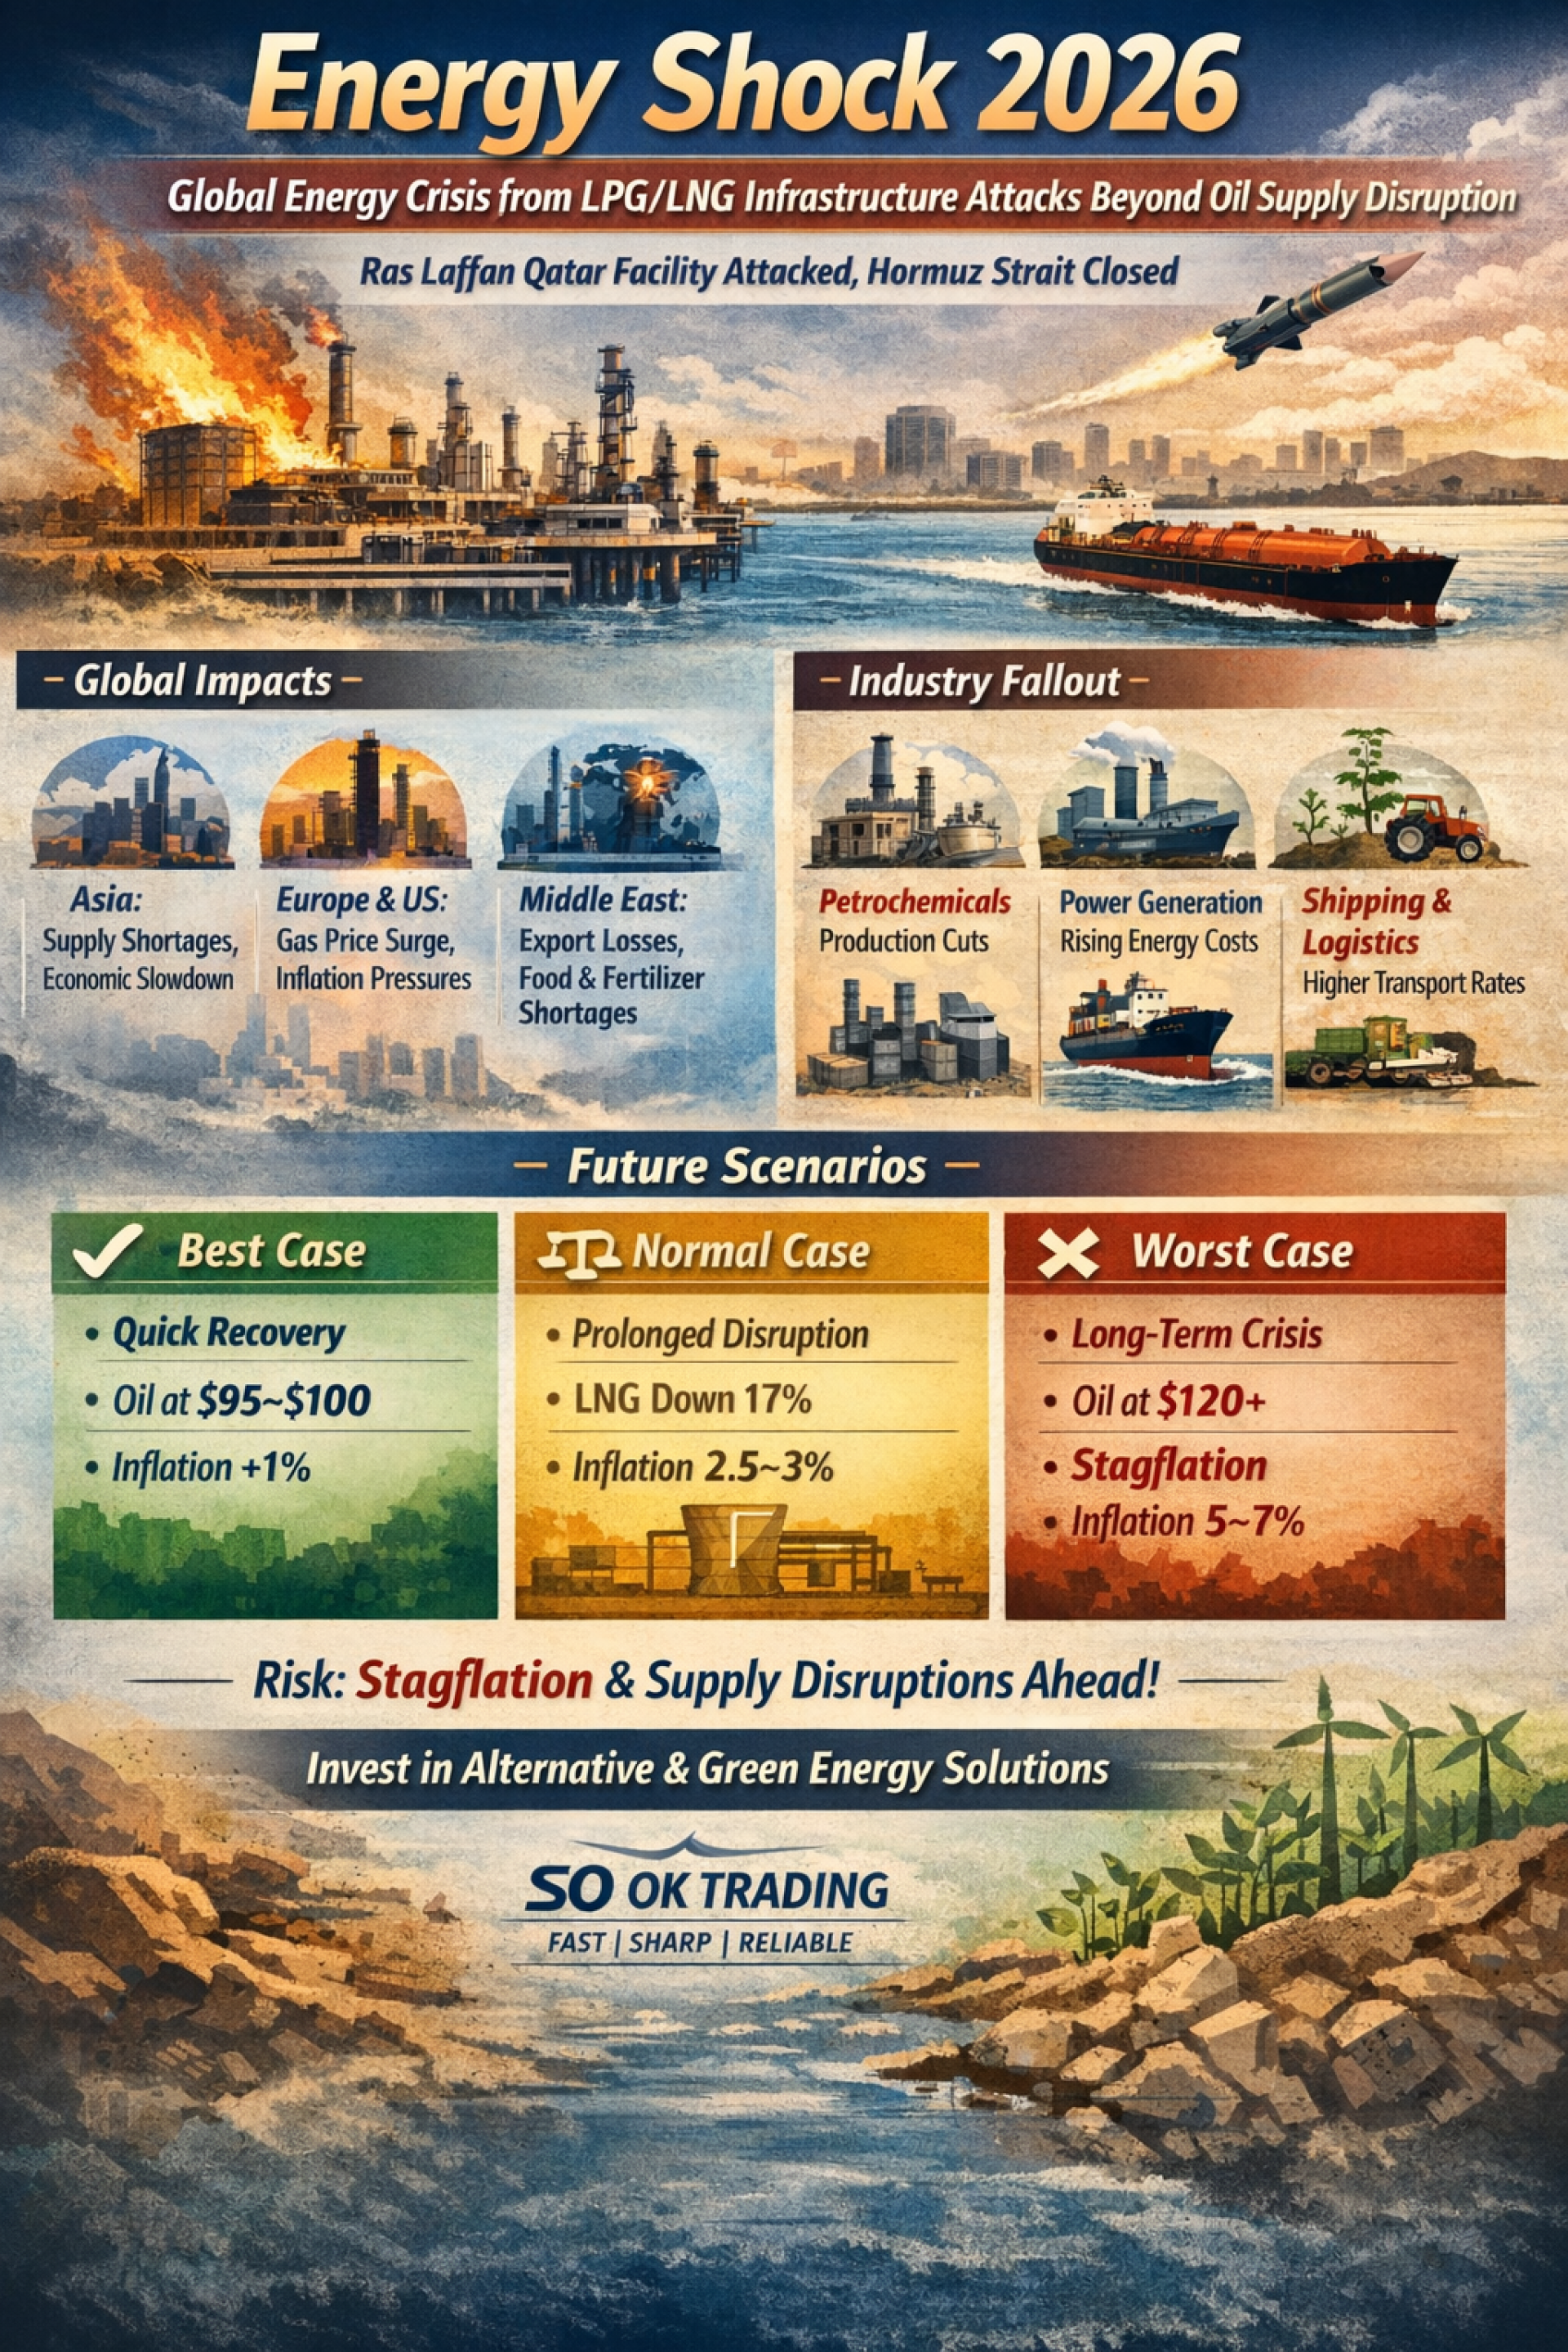
Energy Shock 2026: The Global Energy Crisis from LPG/LNG Infrastructure Attacks — Beyond Oil Supply Shortages
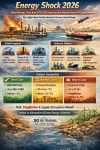
Analytical Article by SO OK TRADING | March 20, 2026In March 2026, the world faced one of the most severe shocks to the economy and energy security in recent years. Qatar’s gas production facilities, particularly the Ras Laffan industrial hub — the heart of the nation’s LNG output — were attacked, resulting in a 17% loss of LNG capacity, a 13% drop in LPG, and a 24% decline in condensate. This disruption not only crippled exports but also forced QatarEnergy to prepare a Force Majeure declaration, affecting long-term contracts for up to five years. At the same time, Iran closed the Strait of Hormuz, halting 20% of global oil shipments instantly.
Regional Impacts
Asia: The hardest hit. China continues massive energy imports despite efforts to reduce reliance. South Korea faces soaring transport costs, with the KOSPI plunging over 12%. Japan, importing more than 90% of its oil from the Middle East, is forced to release strategic reserves. Thailand risks surging inflation, with GDP contraction of 0.5–1% if the crisis persists.
Europe & USA: Europe saw gas prices spike 38% in a single day, competing with Asia for supplies from the U.S. and Australia. The U.S., despite shale gas and reserves, faces domestic inflation pressures preventing the Fed from cutting interest rates.
Middle East: Qatar and Saudi Arabia suffer export revenue losses, Ras Laffan infrastructure damage, and food/fertilizer shortages due to 90% import dependence. Regional retaliatory attacks intensify instability.
Other Regions: Australia’s stock market fell, but demand for its gas exports surged, positioning it as a key alternative supplier alongside Russia. India faces a household LPG crisis, with black-market prices doubling. Africa suffers shortages of refined oil, losing 1 million barrels per day.
Industry Fallout
Petrochemicals: Chinese plants cut output by 10–15%, driving global plastic and chemical costs higher.
Power Generation: LNG-dependent electricity production pushes energy tariffs upward across Asia.
Logistics & Shipping: Freight rates rise 15–20%, disrupting global trade hubs like Singapore.
Agriculture & Food: Qatar’s urea fertilizer plants shut down, raising fertilizer costs and food prices worldwide.
Households: Rising expenses from LPG, electricity, and plastic-based consumer goods strain living costs.
Scenarios
✅ Best Case: Attacks end within 1–2 months, partial recovery of production. Oil stabilizes at $95–$100, global inflation rises only 0.5–1%. Low probability.
⚖️ Normal Case: Repairs take 3–6 months, Qatar continues losing 17% LNG capacity. Spot cargo prices surge 2–3x, Thailand’s inflation reaches 2.5–3%, Chinese petrochemical plants cut output 10–15%. Most likely scenario.
❌ Worst Case: Hormuz Strait remains closed long-term, Qatar loses 13 million tons/year of LNG for 3–5 years. Oil prices soar to $120–130, global inflation rises 1.5–2.5%, Thailand hits 5–7% inflation, entering stagflation. Petrochemical plants worldwide shut down, India and Africa face severe household LPG crises.
Outlook
Short Term (1–3 months): Panic buying drives spot cargo prices sky-high.
Medium Term (3–6 months): If Qatar’s repairs stall, structural shortages emerge, petrochemical plants halt operations.
Long Term (6+ months): Continued Hormuz closure leads to energy-driven inflation and stagflation — economic stagnation with soaring costs.
✨ Conclusion
This is not just an oil shortage — it is a global energy shock rippling into food, logistics, and household costs. Within 3–6 months, living expenses will rise significantly, and in the worst case, the world could enter stagflation: economic stagnation combined with high inflation.
The lesson is clear: global energy security remains fragile. Diversification and investment in alternative energy will be the cornerstone of economic and business strategies in this decade. Green energy and other alternatives are the key to mitigating this crisis.
SO OK TRADING: Your Business Partner
SO OK TRADING: FAST | SHARP | RELIABLE
VISIT US AT WWW.SOOKTRADING.COM
Would you like me to also craft a short, punchy tagline version in English (ideal for LinkedIn or infographic use) to complement this full article?