“Thailand EV Tires: Game‑Changing Path to Becoming a Global Market Leader — The Golden Road to the Future by SO OK TRADING” : 15 SEP 2026
EV Tires: Thailand’s Golden Opportunity Amid Global Competition : SO OK TRADING : 15 SEP 2026
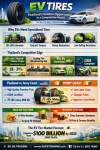
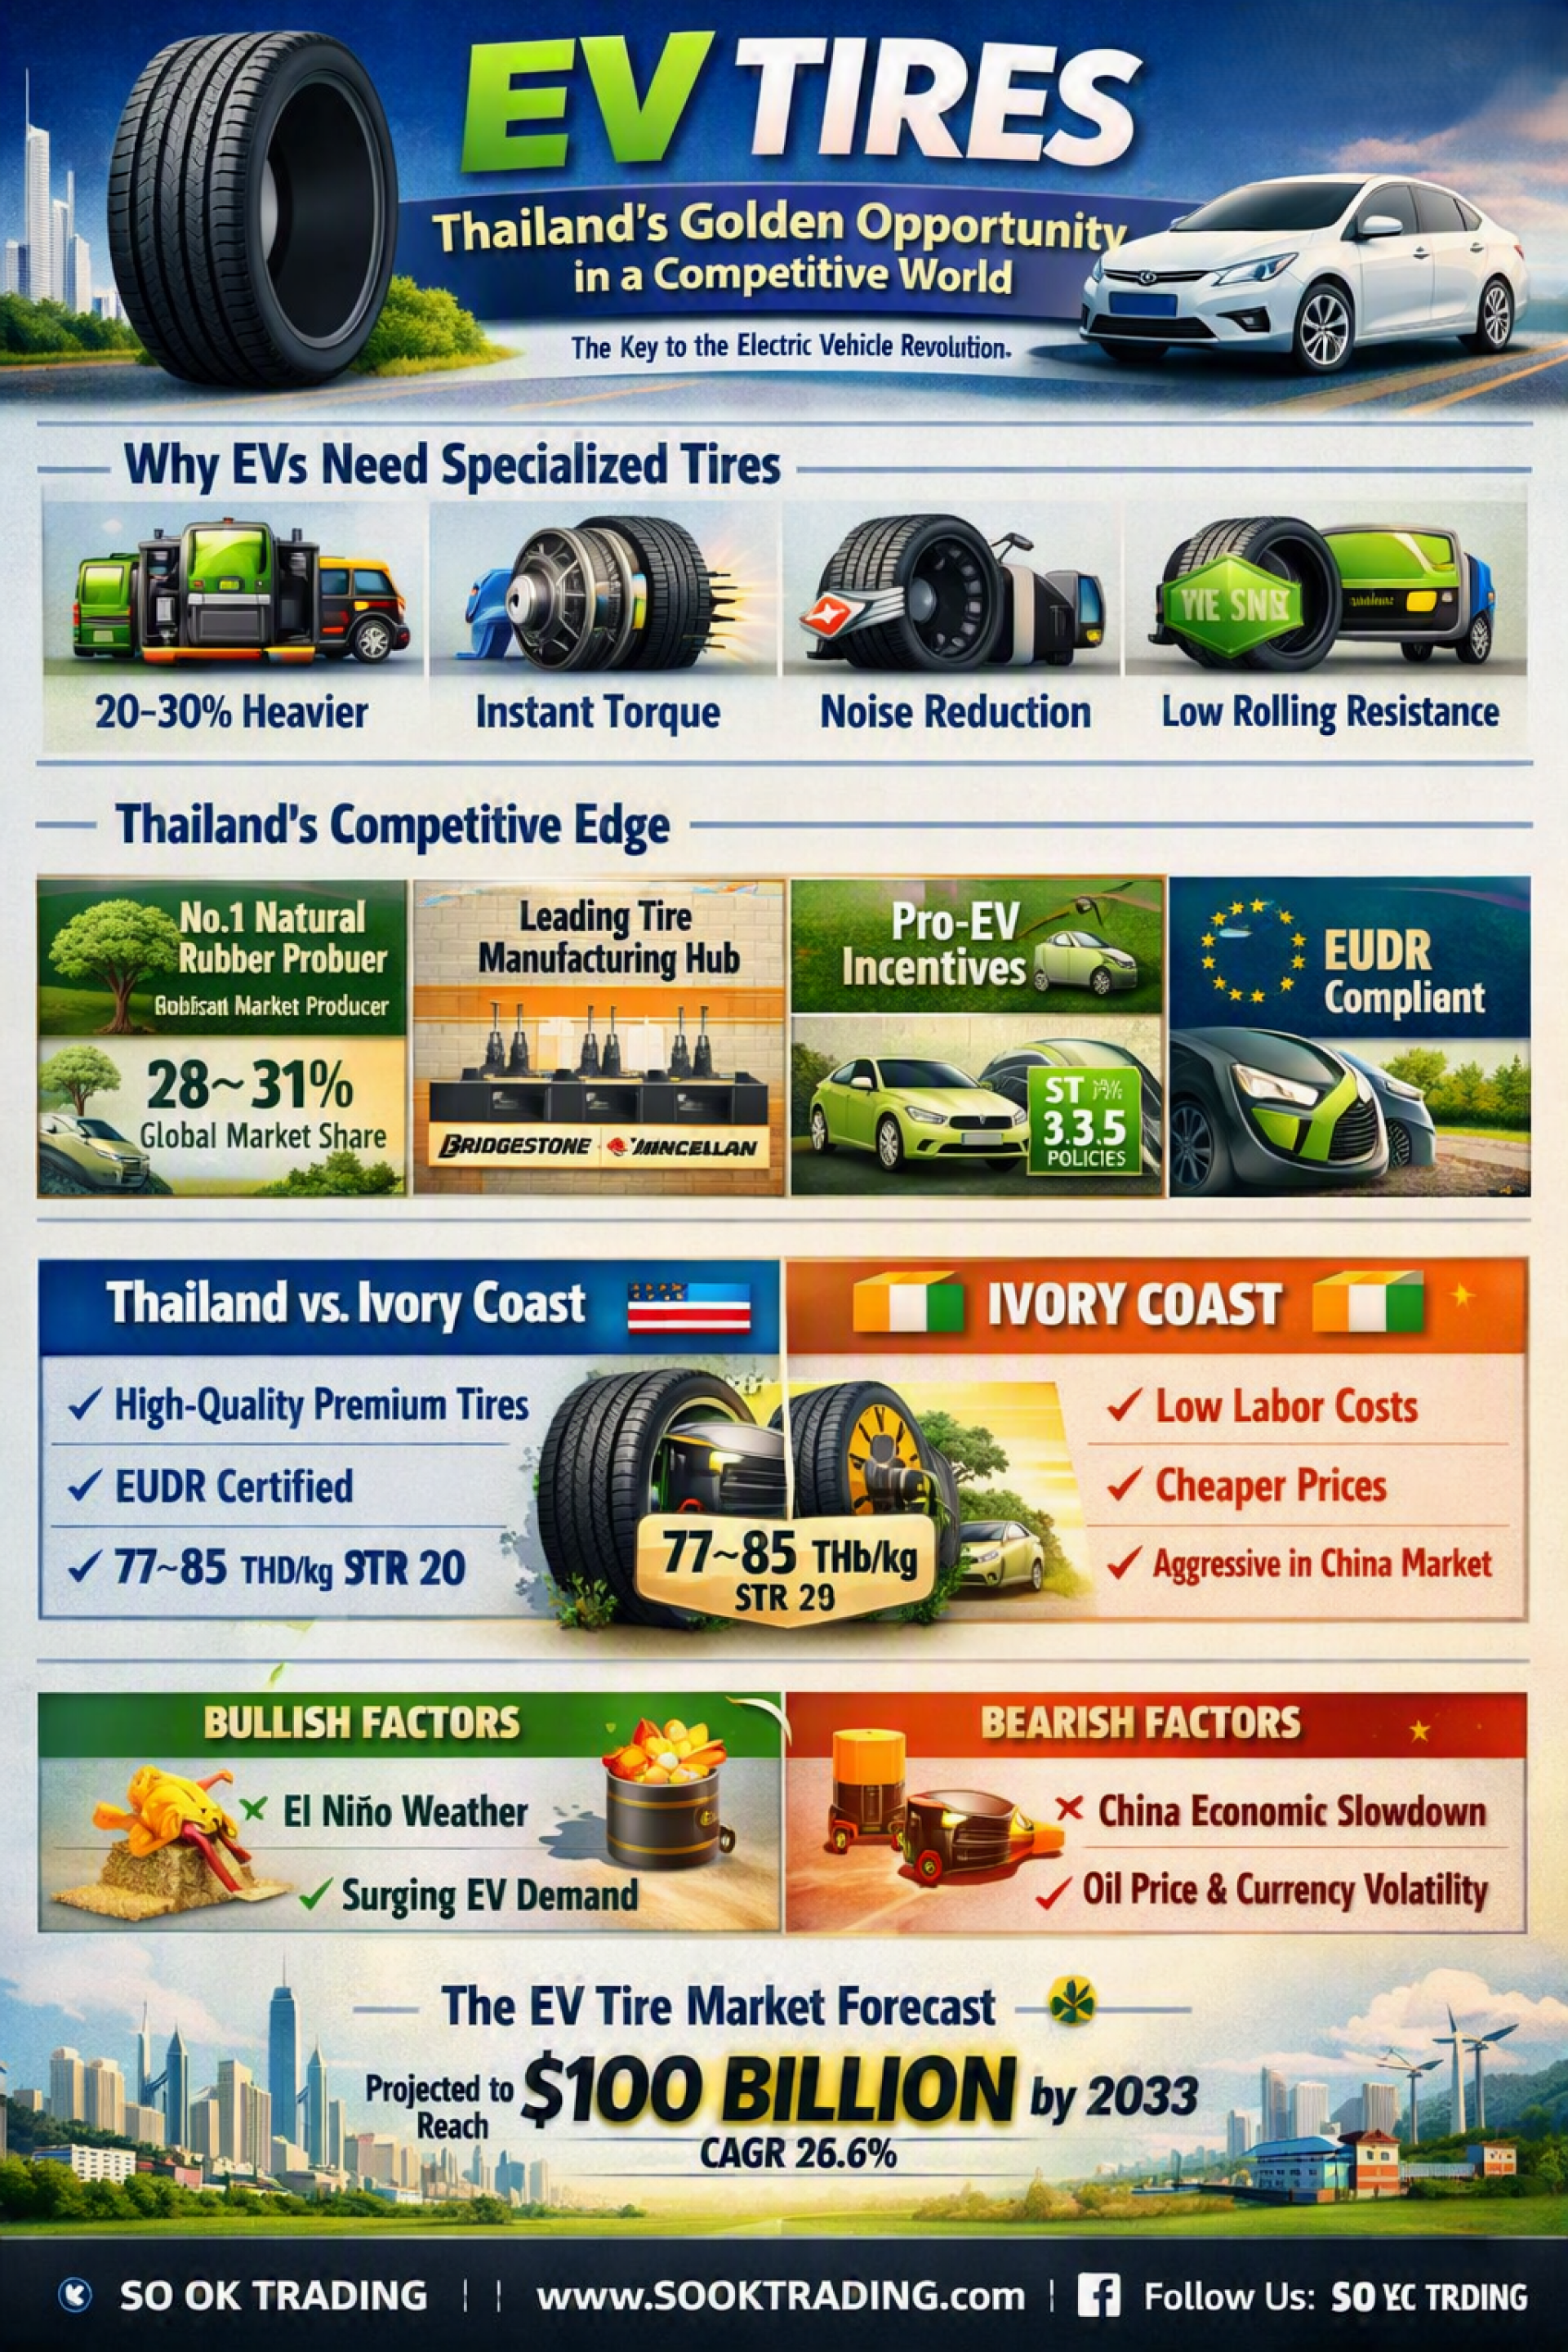
The electric vehicle (EV) industry is rapidly transforming the global automotive landscape, and one of its core components is the EV tire. EV tires must withstand heavier weight, higher torque, and help extend driving range per charge. As a result, EV tires carry 1.2–1.5 times higher added value compared to conventional tires. Thailand, as one of the world’s largest producers of natural rubber and tires, is directly benefiting from this transition.
Strengths of Thailand’s EV Tire Industry
Thailand is well-prepared with abundant raw materials and a complete automotive ecosystem. Global tire manufacturers such as Bridgestone, Michelin, Goodyear, Yokohama, and Continental have chosen Thailand as a production base to meet rising demand. Meanwhile, government policies under EV 3.0 and EV 3.5, along with the “old car for new car” initiative, are boosting domestic demand. Additionally, Thailand’s STR 20 rubber features a traceability system compliant with the EU’s EUDR regulation, enabling premium pricing and strengthening its global market position.
Why EVs Require Specialized Tires
EVs differ significantly from conventional vehicles, requiring specially designed tires to meet unique demands:
Heavier weight: EVs are 20–30% heavier due to batteries, requiring stronger tires
Instant torque: Electric motors deliver immediate torque, demanding special compounds to resist wear
Cabin quietness: With no engine noise, tires must reduce road noise (e.g., sound-absorbing foam)
Low rolling resistance: EV tires are engineered to save energy and extend driving range
Thailand vs Ivory Coast
Globally, Thailand remains the No.1 exporter of natural rubber, with a 28–31% market share, especially in premium and EV tire segments where quality and environmental standards are critical. In contrast, Ivory Coast enjoys nearly half the labor cost of Thailand and offers rubber at an average of 5 THB/kg cheaper, aggressively expanding into the Chinese market.
Comparison Summary:
Thailand → Advantage in quality and environmental standards, securing premium and EV markets
Ivory Coast → Competing on low-cost markets, particularly in China
STR 20 Price Outlook and Market Direction
In 2026, Thailand’s STR 20 prices have ranged between 77–85 THB/kg, with potential to remain high and volatile (Bullish Volatility). Under severe El Niño conditions, some grades may reach 100 THB/kg.
Price Support Factors
El Niño and climate volatility tightening supply
EVs consume 50% more natural rubber than gasoline cars
EU’s EUDR regulation driving advance orders for Thai premium rubber
Risks to Watch
China’s economic slowdown may cap price increases
Oil price and currency fluctuations impacting synthetic rubber costs
Overall Outlook
The EV tire industry is the fastest-growing high-value market worldwide, projected to reach USD 100 billion by 2033, with a CAGR of 26.6%. Thailand’s strengths in raw materials, quality, and environmental standards position it to become a global hub for EV tires. However, cost competition from rivals—especially Ivory Coast’s aggressive push into China—remains a challenge.
SO OK TRADING: Your Trusted Business Partner SO OK TRADING: FAST SHARP RELIABLE
VISIT US AT : WWW.SOOKTRADING.COM FACEBOOK : SO OK TRADING